Trend Following Channel Breakout Strategy with Moving Average and Trailing Stop
This is a breakout strategy based on price Channel, combined with moving average indicators and trailing stop/take profit for entry and exit. It uses moving average of high/low prices to construct the price Channel…
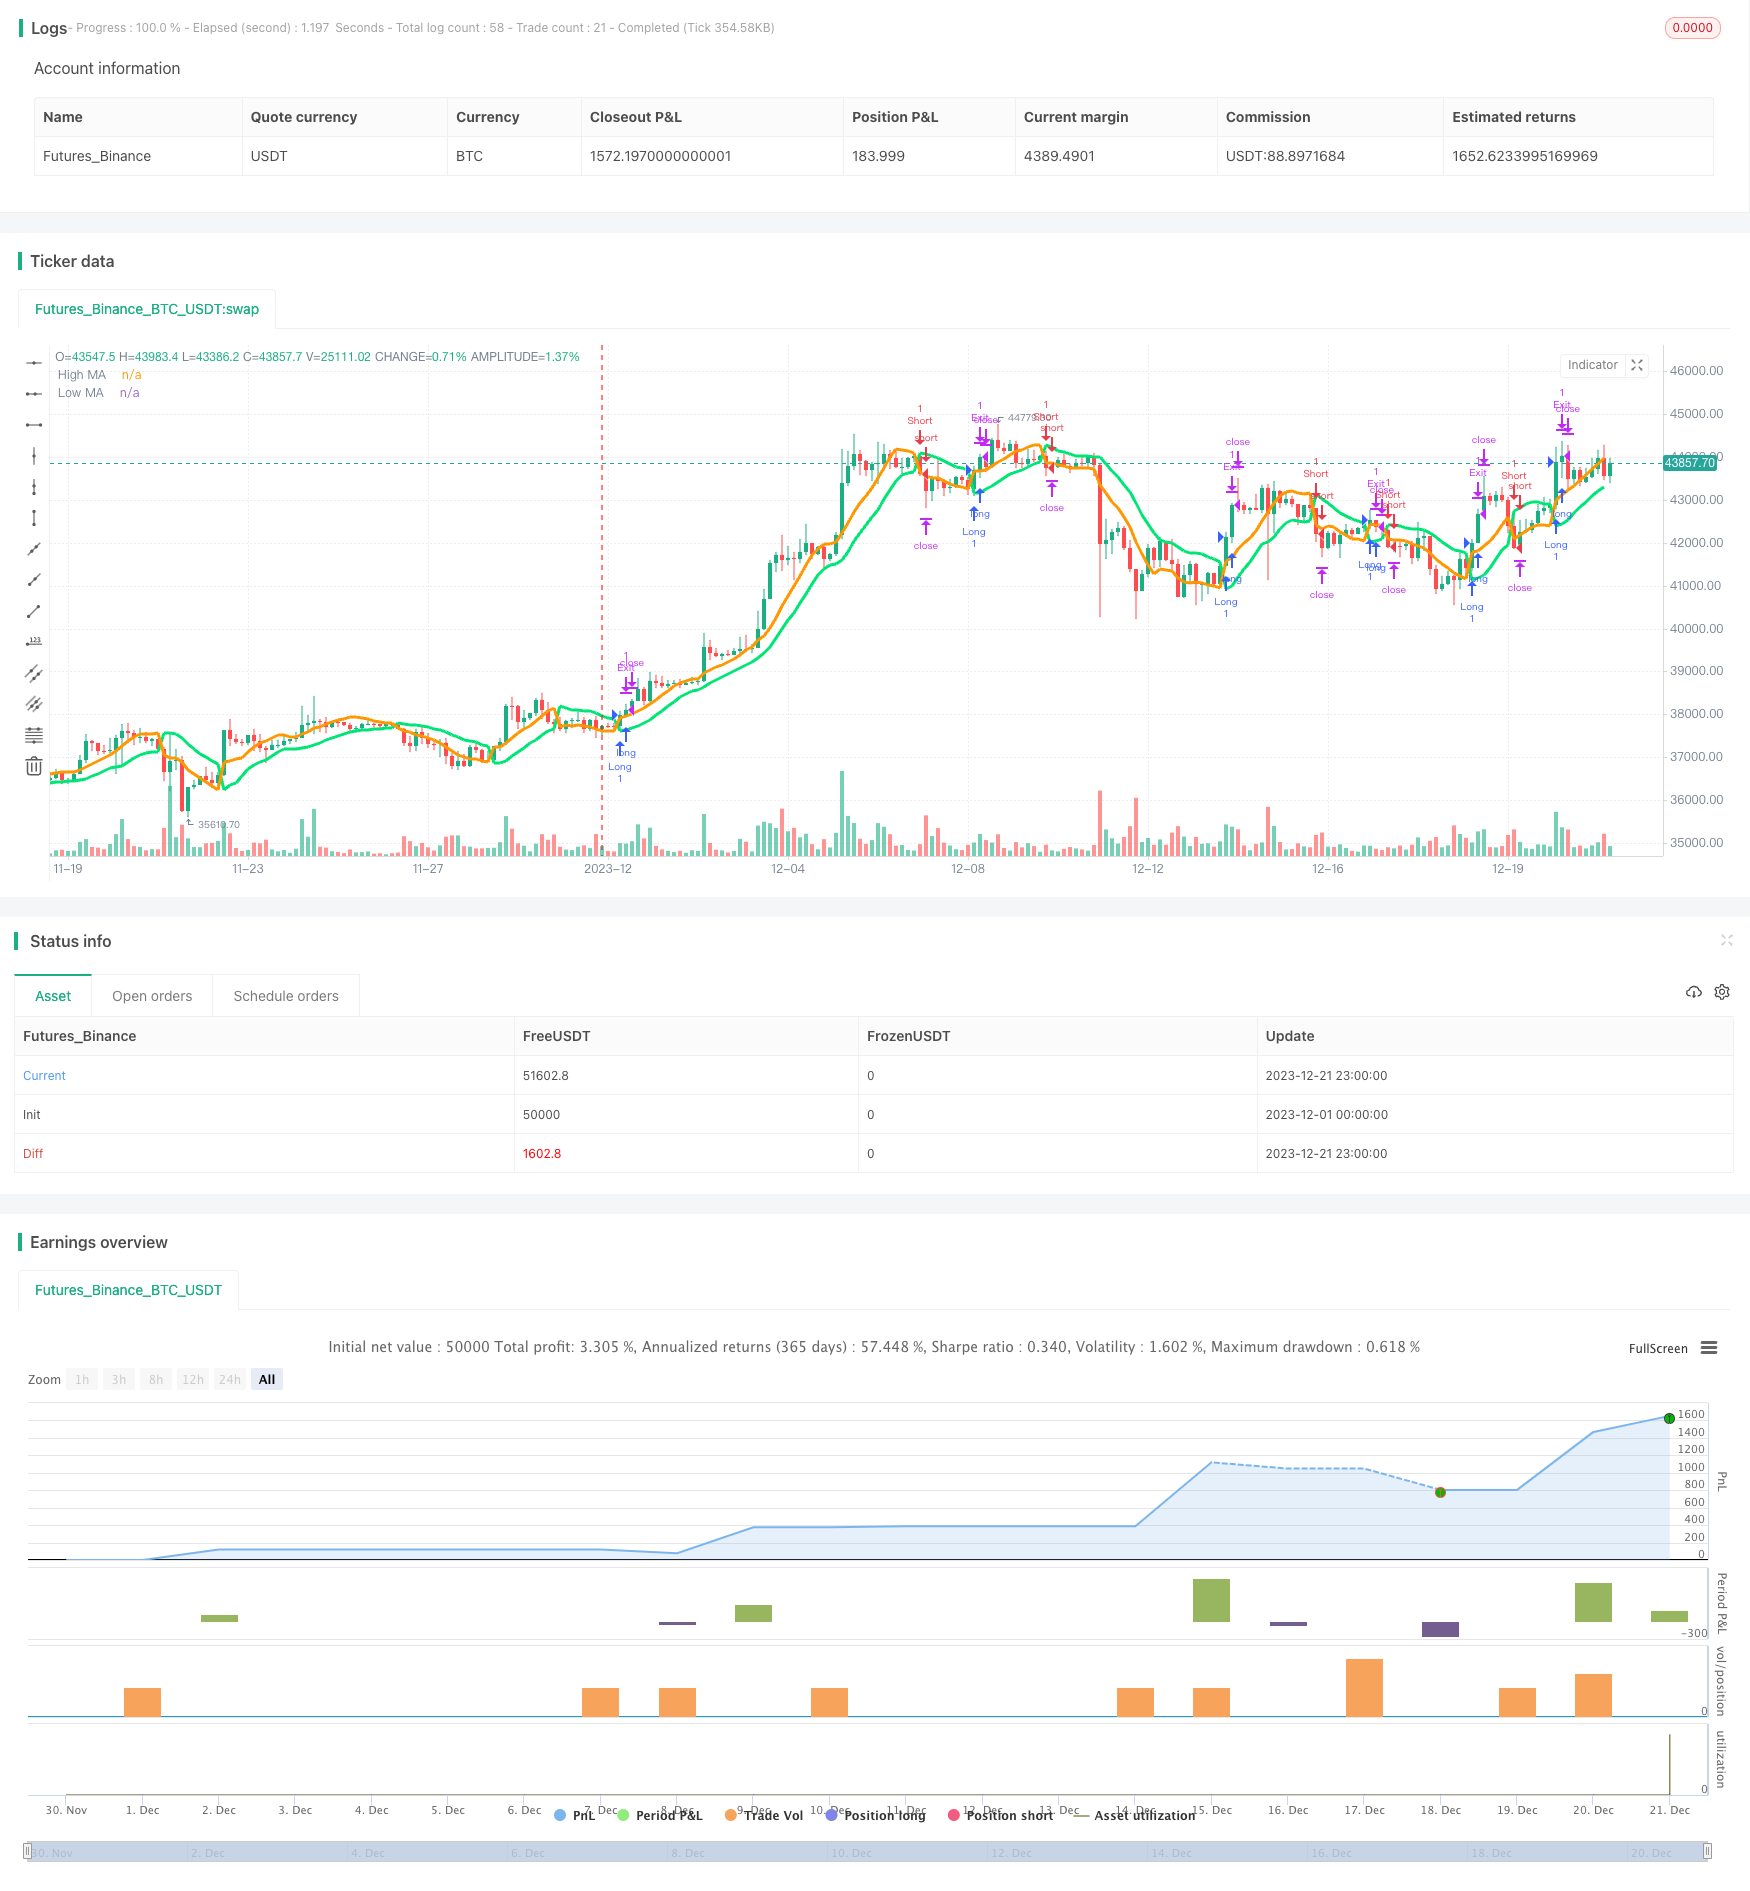
Overview
This is a breakout strategy based on price Channel, combined with moving average indicators and trailing stop/take profit for entry and exit. It uses moving average of high/low prices to construct the price Channel, and enter long/short when price breaks out of the Channel, with fixed stop loss or trailing stop to control risks.
Strategy Logic
The strategy calculates moving averages of high/low prices to form a price Channel. Specifically, it computes length 10 SMA of high/low prices to plot the upper and lower band of the Channel. When price breaks out above the lower band into the upper band, it enters long. When price breaks down from the upper band into the lower band, it enters short.
After entry, the strategy uses either fixed stop loss or trailing stop for exit. The trailing stop consists of two parameters: fixed take profit level, and activating offset. When price reaches the activating offset, the take profit level starts to trail the price. This allows locking in profits while keeping some open space.
The strategy also combines time range filter, only running backtest within specified historical timeframe, to test performance across different market stages.
Advantage Analysis
The strategy exploits price Channel and trend following with trailing stop, which allows it to capture mid-to-long term trend directions. Compared to simple moving average strategies, it avoids ineffective trades due to price fluctuations. With trailing stops, it can dynamically trail prices to lock in profits.
Overall, the strategy has clear logic, minimal indicators and parameters, easy to backtest, suitable for mid-to-long term trend trading, and can profit from strong trends.
Risk Analysis
The strategy tends to get stopped out easily during ranging, choppy markets, unable to sustain profits. Also during extreme moves, price may break out the stop loss aggressively leading to large losses.
The parameter tuning is quite subjective, requiring adjustments across different market stages. The fixed take profit and activating offset fails to adapt to varying market volatility.
Enhancement Opportunities
Other indicators such as volume, Bollinger Bands can be incorporated to filter entry signals, avoiding traps. Or dynamic stops can be used based on ATR or price volatility.
Exit rules may be upgraded to trailing stop or Chandelier Exit. Partial profit targets can be considered when price re-enters Channel. Optimizing entry filters and exit rules can greatly improve stability of the strategy.
Conclusion
In summary, this is a quantitative strategy based on price Channel, trend following, stop loss/profit taking management. It has clear logic flow, simple parameter structure, easy to understand and backtest. It is suitable to learn algorithmic trading concepts. The strategy can be enhanced in various aspects to improve stability and profitability. The core idea is to capture trend direction, and manage risks via stop loss and take profit. It can be applied to various products over different timeframes.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Lb |
| v_input_2 | 0 | MA Type: SMA | EMA | HMA | McG | WMA | Tenkan |
| v_input_3 | 300 | SL Activation |
| v_input_4 | true | SL Trigger |
| v_input_5 | 150 | TP Activation |
| v_input_6 | true | TP Trigger |
| v_input_7 | true | From Month |
| v_input_8 | true | From Day |
| v_input_9 | 2019 | From Year |
| v_input_10 | 6 | To Month |
| v_input_11 | 19 | To Day |
| v_input_12 | 2020 | To Year |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-21 23:59:59
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Generalized SSL Backtest w/ TSSL", shorttitle="GSSL Backtest", overlay=true )
// Generalized SSL:
//  This is the very first time the SSL indicator, whose acronym I ignore, is on Tradingview.
//  It is based on moving averages of the highs and lows.
//  Similar channel indicators can be found, whereas
//  this one implements the persistency inside the channel, which is rather tricky.
//  The green line is the base line which decides entries and exits, possibly with trailing stops.
//  With respect to the original version, here one can play with different moving averages.
//  The default settings are (10,SMA)
//
// Vitelot/Yanez/Vts March 2019

lb = input(10, title="Lb", minval=1)
maType = input( defval="SMA", title="MA Type", options=["SMA","EMA","HMA","McG","WMA","Tenkan"])

fixedSL = input(title="SL Activation", defval=300)
trailSL = input(title="SL Trigger", defval=1)
fixedTP = input(title="TP Activation", defval=150)
trailTP = input(title="TP Trigger", defval=1)

FromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2019, title = "From Year", minval = 2017)
ToMonth   = input(defval = 6, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 19, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 2020, title = "To Year", minval = 2017)
start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)  // backtest start window
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)        // backtest finish window
startTimeOk()  => true // create function "within window of time" if statement true
// QUANDL:BCHAIN/ETRVU is USD-denominated daily transaction value on BTC blockchain
// QUANDL:BCHAIN/MKTCP is USD-denominated Bitcoin marketcap

hma(sig, n) => // Hull moving average definition
    wma( 2*wma(sig,round(n/2))-wma(sig,n), round(sqrt(n)))

mcg(sig,length) => // Mc Ginley MA definition
    mg = 0.0
    mg := na(mg[1]) ? ema(sig, length) : mg[1] + (sig - mg[1]) / (length * pow(sig/mg[1], 4))

tenkan(sig,len) =>
    0.5*(highest(sig,len)+lowest(sig,len))

ma(t,sig,len) =>
    sss=na
    if t =="SMA"
        sss := sma(sig,len)
    if t == "EMA"
        sss := ema(sig,len)
    if t == "HMA"
        sss := hma(sig,len)
    if t == "McG" // Mc Ginley
        sss := mcg(sig,len)
    if t == "Tenkan"
        sss := tenkan(sig,len)
    if t == "WMA"
        sss := wma(sig,len)
    sss

base(mah, mal) =>
    bbb = na
    inChannel = close<mah and close>mal
    belowChannel = close<mah and close<mal
    bbb := inChannel? bbb[1]: belowChannel? -1: 1
    uuu = bbb==1? mal: mah
    ddd = bbb==1? mah: mal
    [uuu, ddd]

maH = ma(maType, high, lb)
maL = ma(maType, low, lb)

[up, dn] = base(maH,maL)

plot(up, title="High MA", color=lime, linewidth=3)
plot(dn, title="Low MA", color=orange, linewidth=3)

long = crossover(dn,up)
short = crossover(up,dn)

// === STRATEGY - LONG POSITION EXECUTION ===
strategy.entry("Long", strategy.long, when= long and startTimeOk())
strategy.exit("Exit", qty_percent = 100, loss=fixedSL, trail_offset=trailTP, trail_points=fixedTP)
strategy.exit("Exit", when= short)
// === STRATEGY - SHORT POSITION EXECUTION ===
strategy.entry("Short", strategy.short, when= short and startTimeOk())
strategy.exit("Exit", qty_percent = 100, loss=fixedSL, trail_offset=trailTP, trail_points=fixedTP)
strategy.exit("Exit", when= long)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Channel-Breakout-Strategy-with-Moving-Average-and-Trailing-Stop.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m