Strategy vault / Trend following
Trend Following Dual EMA Crossover Strategy with SMA Trend Filtering System
This strategy is a quantitative trading system that combines moving average (MA) crossovers with trend following. It utilizes a 15-period Simple Moving Average (SMA) as a trend filter, while using the crossover of…
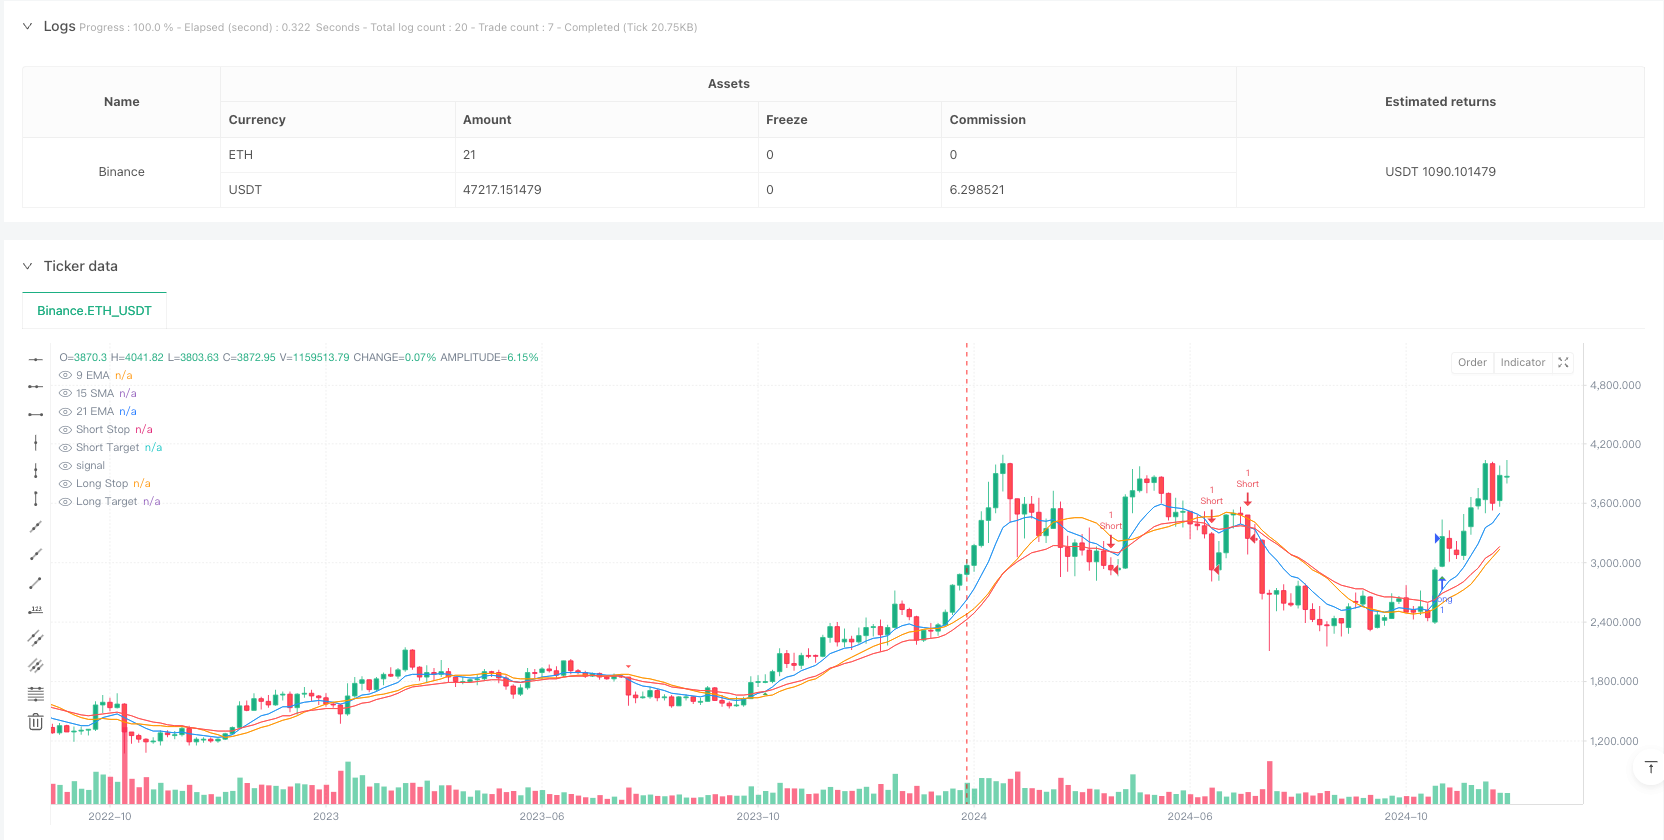
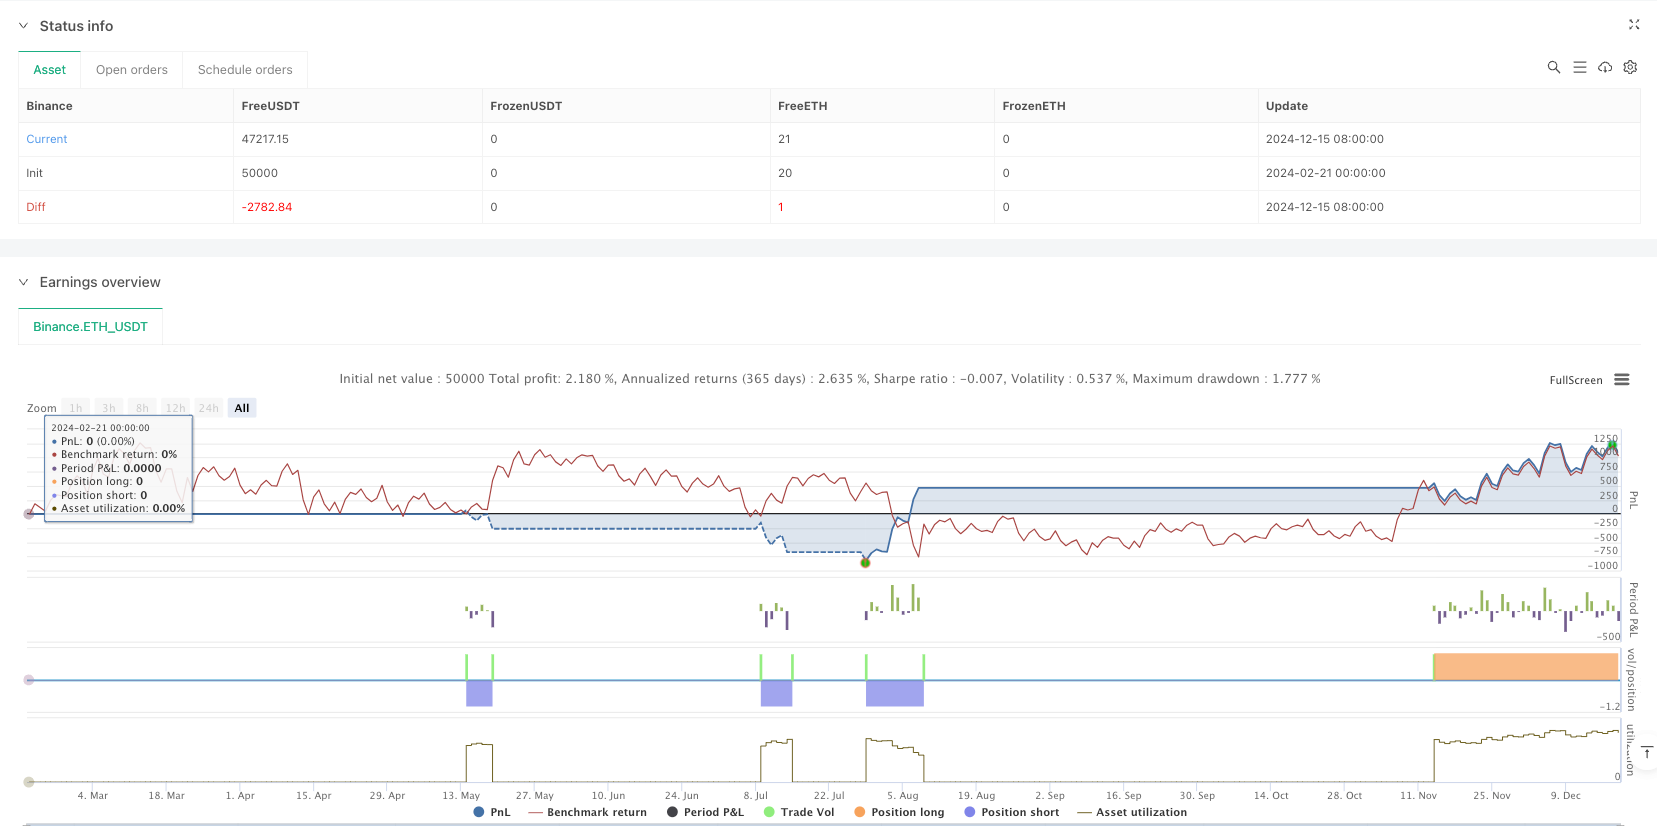
Overview
This strategy is a quantitative trading system that combines moving average (MA) crossovers with trend following. It utilizes a 15-period Simple Moving Average (SMA) as a trend filter, while using the crossover of 9-period and 21-period Exponential Moving Averages (EMA) to generate trading signals. The strategy employs strict entry conditions and a fixed 1:4 risk-reward ratio for risk management.
Strategy Principles
The core logic of the strategy is based on the following key elements:
- Trend Confirmation: Uses 15-period SMA as the primary trend indicator. Price above 15 SMA indicates uptrend, while below indicates downtrend.
- Trading Signals: Triggers trades through 9 EMA and 21 EMA crossovers. Long signals are generated when 9 EMA crosses above 21 EMA with other conditions met; short signals when 9 EMA crosses below 21 EMA with conditions met.
- Confirmation Conditions: Long entries require two consecutive bullish candles with both EMAs above 15 SMA; short entries require a bearish candle with both EMAs below 15 SMA.
- Risk Management: System automatically calculates stop-loss and profit targets using a 1:4 risk-reward ratio.
Strategy Advantages
- Strong Trend Following Capability: The 15 SMA trend filtering mechanism effectively avoids trading in ranging or counter-trend markets.
- Multiple Confirmation Mechanism: Combines moving average crossovers, candlestick patterns, and trend confirmation to reduce false signals.
- Comprehensive Risk Management: Fixed risk-reward ratio and automatic stop-loss/profit targets support long-term stability.
- Clear Visual Feedback: System provides clear visual indicators including trade signal markers and stop-loss/profit target levels.
Strategy Risks
- Lag Risk: Moving averages are inherently lagging indicators, potentially slow to react to rapid market reversals.
- False Breakout Risk: May generate false crossover signals in ranging markets.
- Fixed Risk Ratio Limitations: The 1:4 fixed risk-reward ratio may not suit all market conditions.
- Consecutive Loss Risk: May experience consecutive stops in choppy markets.
Strategy Optimization Directions
- Dynamic Period Optimization: Automatically adjust moving average periods based on market volatility.
- Volatility Filtering: Add ATR or other volatility indicators to optimize entry timing.
- Dynamic Risk Management: Adjust risk-reward ratio based on market conditions.
- Enhanced Market Context: Incorporate trend strength indicators to optimize trading conditions.
Summary
This is a well-designed, logically rigorous trend following strategy. Through the combination of multiple technical indicators and strict risk management, the strategy demonstrates good practicality. While inherent risks exist, the suggested optimization directions can further enhance strategy stability and profitability. The strategy is particularly suitable for trending markets and recommended for medium to long-term timeframes.
Source Pine Script
/*backtest
start: 2024-02-21 00:00:00
end: 2024-12-19 00:00:00
period: 4d
basePeriod: 4d
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=5
strategy("EMA Crossover Strategy with 15 SMA Trend", overlay=true, margin_long=100, margin_short=100)

// Calculate Indicators
sma15 = ta.sma(close, 15)
ema9 = ta.ema(close, 9)
ema21 = ta.ema(close, 21)

// Trend Detection
uptrend = close > sma15
downtrend = close < sma15

// Crossover Conditions
goldenCross = ta.crossover(ema9, ema21)
deathCross = ta.crossunder(ema9, ema21)

// Candle Conditions
twoBullish = (close > open) and (close[1] > open[1])
bearishCandle = (close < open)

// Entry Conditions
longCondition = goldenCross and uptrend and twoBullish and (ema9 > sma15) and (ema21 > sma15)
shortCondition = deathCross and downtrend and bearishCandle and (ema9 < sma15) and (ema21 < sma15)

// Risk Management
var float longStop = na
var float longTarget = na
var float shortStop = na
var float shortTarget = na

if longCondition
    longStop := low
    longTarget := close + 4*(close - longStop)
    strategy.entry("Long", strategy.long)
    strategy.exit("Long Exit", "Long", stop=longStop, limit=longTarget)

if shortCondition
    shortStop := high
    shortTarget := close - 4*(shortStop - close)
    strategy.entry("Short", strategy.short)
    strategy.exit("Short Exit", "Short", stop=shortStop, limit=shortTarget)

// Visual Elements
plot(sma15, "15 SMA", color=color.orange)
plot(ema9, "9 EMA", color=color.blue)
plot(ema21, "21 EMA", color=color.red)

// Plot trading levels
plot(longCondition ? longStop : na, "Long Stop", color=color.red, style=plot.style_linebr)
plot(longCondition ? longTarget : na, "Long Target", color=color.green, style=plot.style_linebr)
plot(shortCondition ? shortStop : na, "Short Stop", color=color.red, style=plot.style_linebr)
plot(shortCondition ? shortTarget : na, "Short Target", color=color.green, style=plot.style_linebr)

// Signal Markers
plotshape(longCondition, "Buy", shape.triangleup, location.belowbar, color=color.green, size=size.small)
plotshape(shortCondition, "Sell", shape.triangledown, location.abovebar, color=color.red, size=size.small)Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Dual-EMA-Crossover-Strategy-with-SMA-Trend-Filtering-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h