Strategy vault / Trend following
Trend Following Long Only Strategy
The Trend Following Long Only Strategy is a strategy that tracks price trends using dynamic moving averages. It determines the current trend by calculating the moving averages of highest and lowest prices over a…
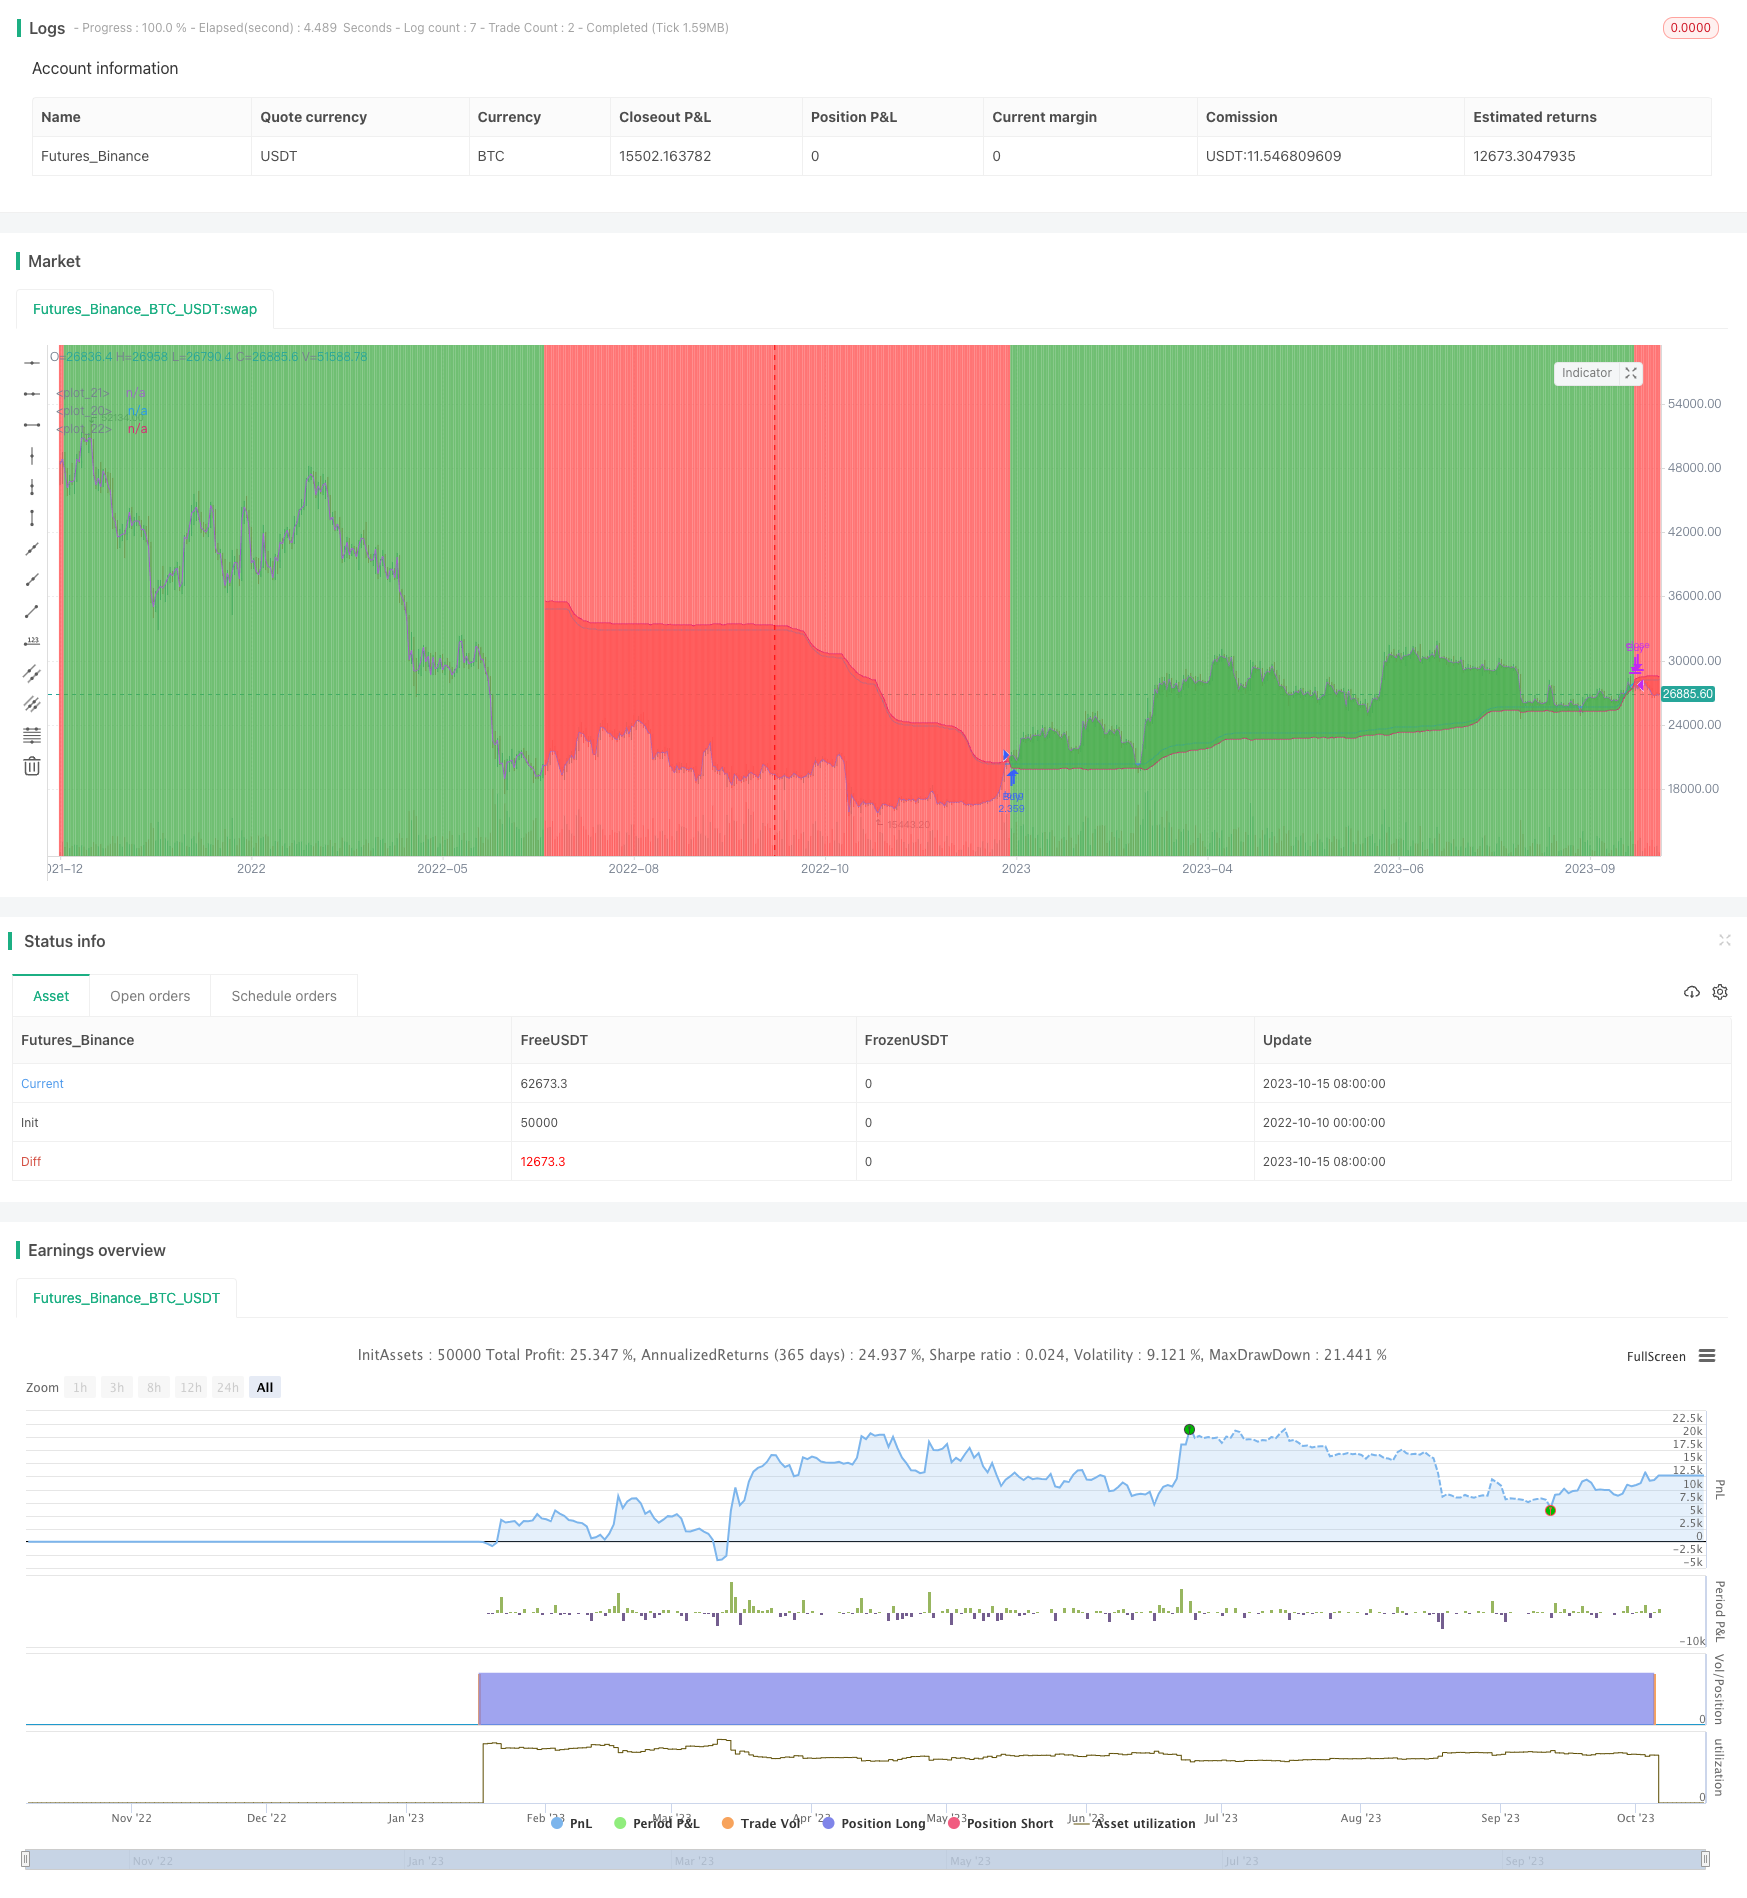
Overview
The Trend Following Long Only Strategy is a strategy that tracks price trends using dynamic moving averages. It determines the current trend by calculating the moving averages of highest and lowest prices over a period and combines it with ATR for dynamic stop loss and take profit. This strategy works well in trending markets by catching trend reversals in a timely manner for long-term holding.
Strategy Logic
The strategy first calculates the moving averages of highest and lowest prices over a period (default 200 days) and takes their midpoint as the baseline. Then it measures the deviation of price from the baseline. If price is above baseline by 1 ATR (0.5 times 10-day ATR by default), it is considered an uptrend. If price is below baseline by 1 ATR, it is considered a downtrend. Long or short positions are entered based on the trend state.
When price reverts to the baseline, exit signals are triggered. Also, the dynamic ATR allows stop loss and take profit to trail the major trend, avoiding over-trading on minor fluctuations.
Advantages
- Dynamic averages smooth price actions effectively to identify long-term trend direction
- ATR-based stops trail the major trend dynamically avoiding excessive sensitivity
- Timely catches of trend reversals reduce untimely capital waste
- Simple logic easy to implement
Risks and Mitigation
- May generate false signals in ranging markets
- Improper parameter tuning may miss trend reversals
- Divergence between market and individual stocks should be considered
Risks can be reduced by tweaking ATR parameters, adding filters for high probability setups, and evaluating market conditions and risk appetite.
Improvement Ideas
- Add secondary confirmation after initial entry signals using indicators like KDJ
- Optimize parameters based on volatility, fundamentals of individual stocks
- Fine tune ATR multiplier based on backtests to balance profit factor and turnover rate
- Introduce dynamic volatility adjustment in stop loss and take profit
- Utilize machine learning techniques for automated parameter optimization
Summary
The Trend Following Long Only Strategy is an easy-to-use trend trading system overall. It identifies trend direction using dynamic averages and sets risk controls with ATR-based stops. It can effectively catch profitable swings in trending markets. Ranging markets should be avoided to prevent whipsaws. Further improvements can be made through parameter tuning, adding filters and integrating machine learning techniques.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 200 | Lookback Length |
| v_input_2 | 5 | Smoother Length |
| v_input_3 | 10 | ATR Length |
| v_input_4 | 0.5 | ATR Multiplier |
Source Pine Script
/*backtest
start: 2022-10-10 00:00:00
end: 2023-10-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Trend Following Long Only Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

lookback_length = input(200, type=input.integer, minval=1, title="Lookback Length")
smoother_length = input(5, type=input.integer, minval=1, title="Smoother Length")
atr_length = input(10, type=input.integer, minval=1, title="ATR Length")
atr_multiplier = input(0.5, type=input.float, minval=0.5, title="ATR Multiplier")

vola = atr(atr_length) * atr_multiplier
price = sma(close, 3)

l = ema(lowest(low, lookback_length), smoother_length)
h = ema(highest(high, lookback_length), smoother_length)
center = (h + l) * 0.5
upper = center + vola
lower = center - vola
trend = ema(price > upper ? 1 : (price < lower ? -1 : 0), 3)
c = trend < 0 ? upper : lower

pcenter = plot(center, transp=100)
pclose = plot(close, transp=100)
pc = plot(c, transp=100)

buy_signal = crossover(trend, 0.0)
sell_signal = crossunder(trend, 0.0)

strategy.entry("Buy", strategy.long, when=buy_signal)
strategy.close("Buy", when=sell_signal)

bgcolor(trend >= 0 ? color.green : color.red, transp=95)
fill(pc, pclose, color=trend >= 0 ? color.green : color.red)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Long-Only-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h