Strategy vault / Trend following
Trend Following Maximized Moving Average Crossover Strategy
This strategy uses the crossover of two moving averages with different periods to generate trading signals. It belongs to trend following strategies. The strategy captures trending opportunities by using signals when…
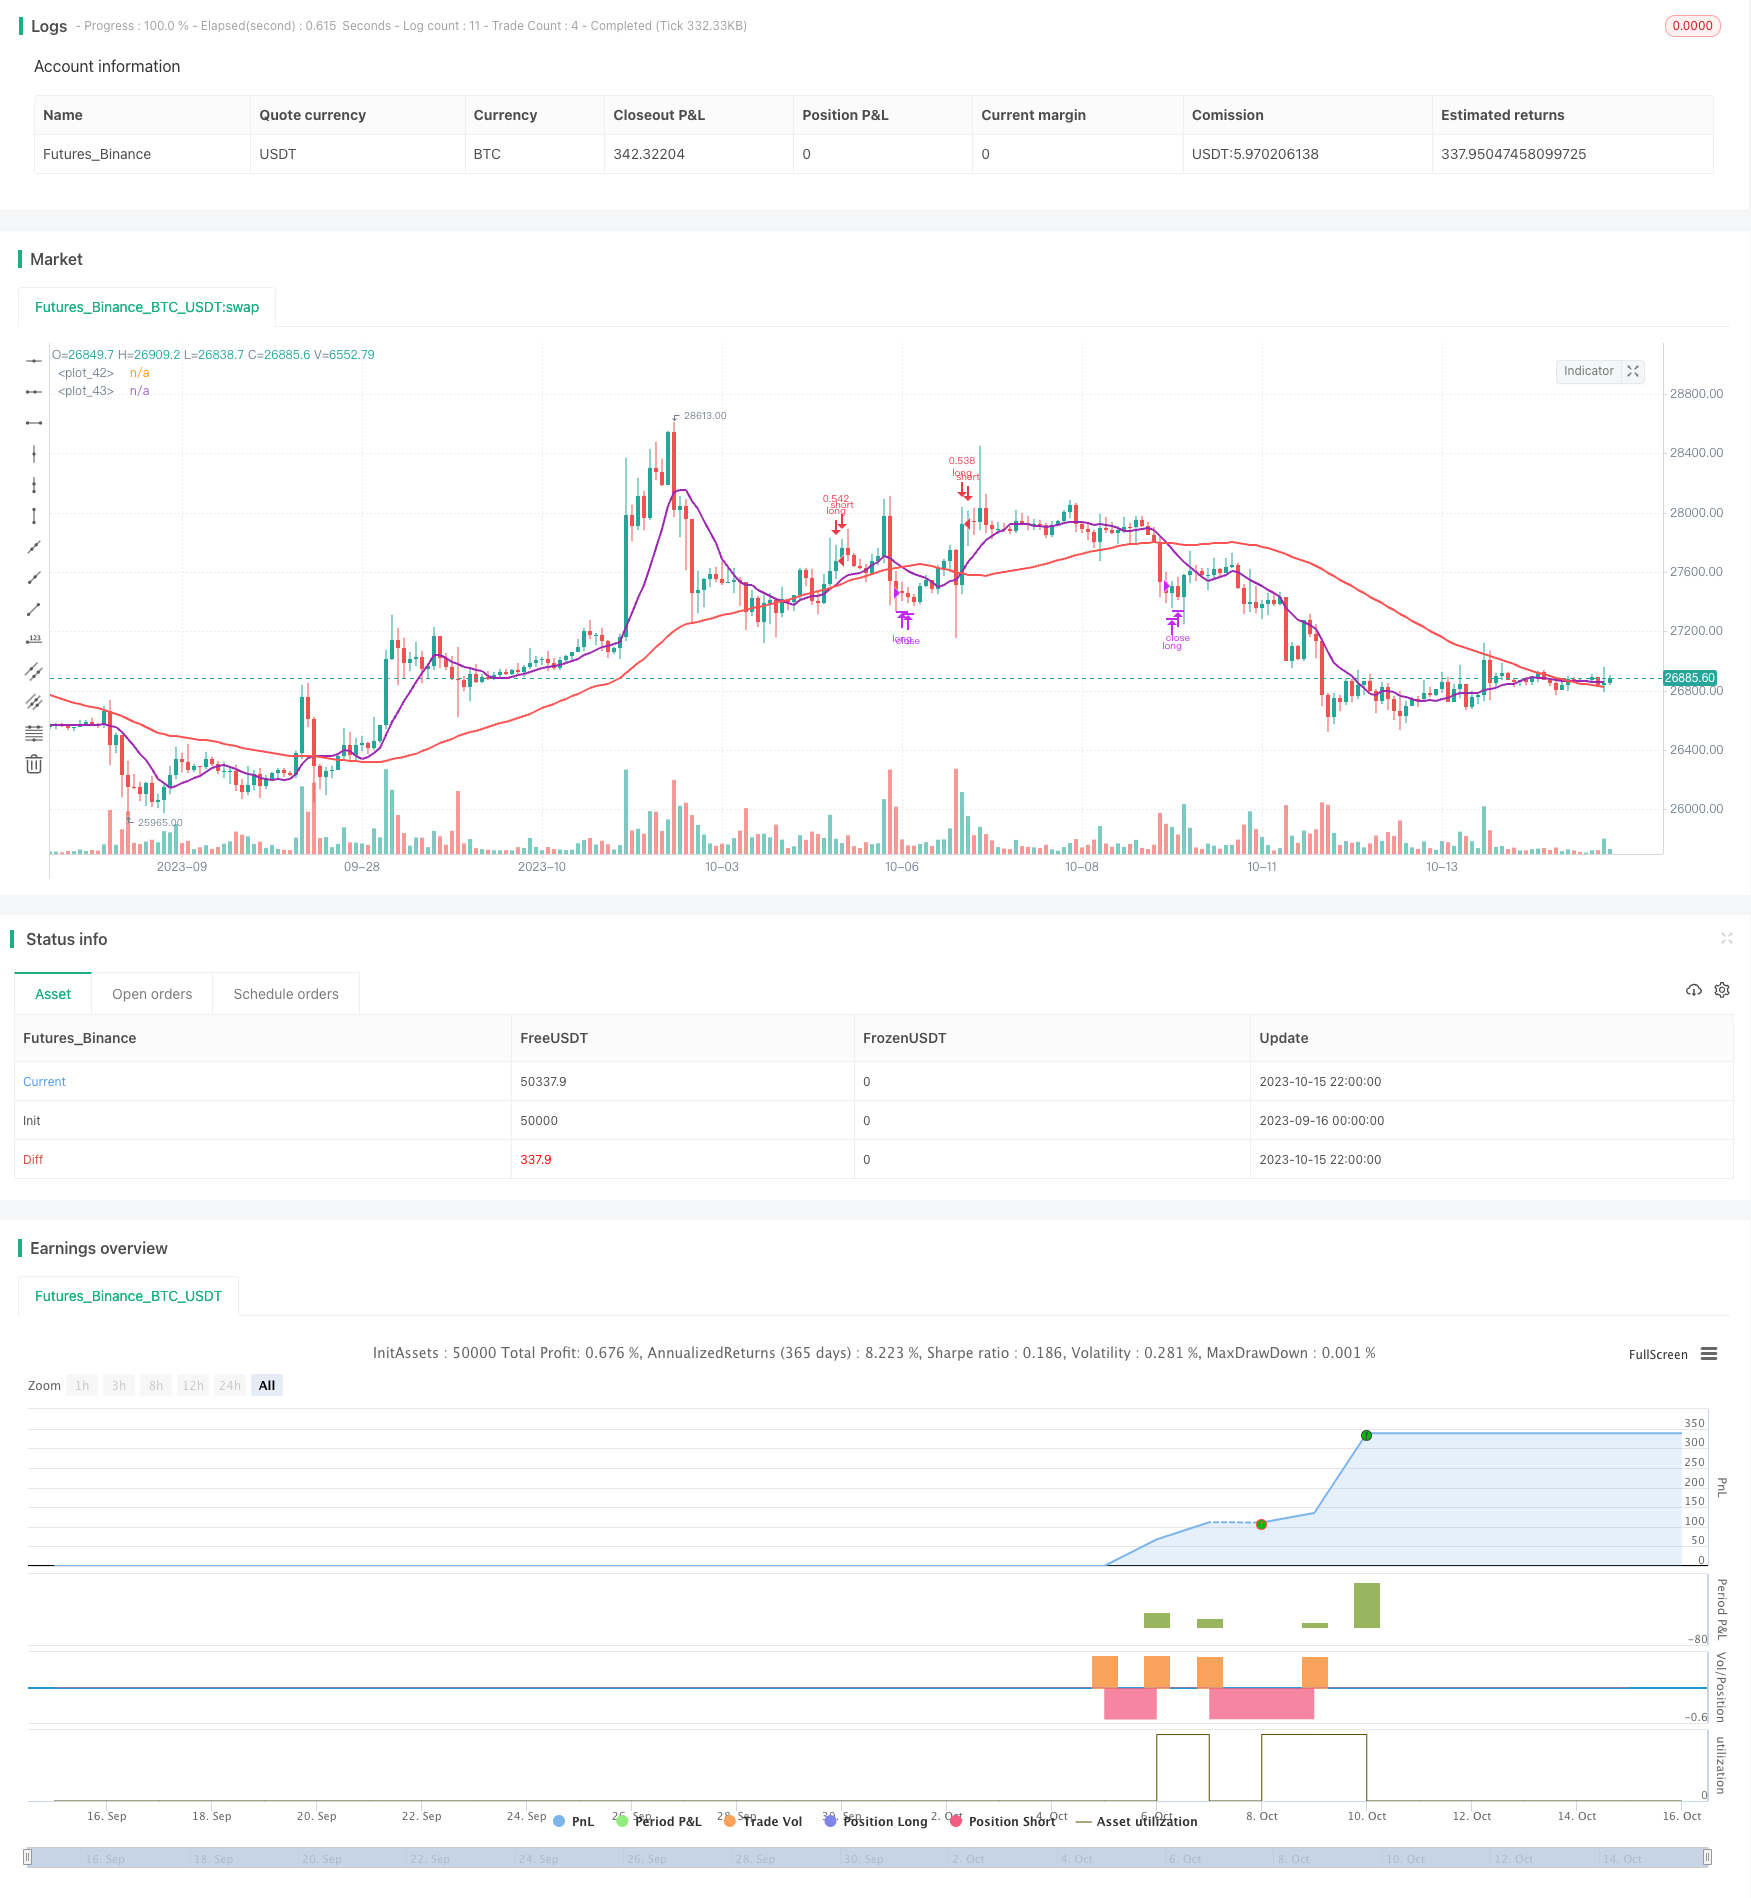
Overview
This strategy uses the crossover of two moving averages with different periods to generate trading signals. It belongs to trend following strategies. The strategy captures trending opportunities by using signals when a shorter period MA crosses a longer period MA.
Strategy Logic
The strategy uses a 9-period short term MA (SMA) and a 50-period long term MA (LMA). When the SMA crosses above the LMA, a buy signal is generated. When the SMA crosses below the LMA, a sell signal is generated.
The strategy also incorporates the RSI indicator to gauge the strength of the trend. Trading signals are only generated when RSI is above a threshold (default 55). This avoids incorrect signals when RSI is in overbought zones.
The strategy trades 30% of total capital each time, with only one position open at a time. 0.1% commission is accounted for.
Advantage Analysis
- Captures trending opportunities effectively using MA crossover trend signals.
- Incorporating RSI avoids incorrect signals when trend stalls.
- Default parameters are optimized and produce steady returns across various markets.
- Reasonable capital management avoids oversized position sizing.
Risk Analysis
- Prone to whipsaws and incorrect signals during range-bound markets without a trend.
- No profits without a significant trend as a trend following strategy.
- Excessive trading and commissions if parameters not tuned properly.
- Lack of stop loss exposes strategy to events risk.
Risks can be reduced via parameter optimization, using other indicators, strict capital management, and stop loss.
Enhancement Opportunities
- Test different MA combinations to find optimal parameters.
- Incorporate other indicators like MACD to confirm trend.
- Implement dynamic stop loss to control loss per trade.
- Adjust position sizing based on different markets.
- Use volume indicators to gauge trend strength.
Conclusion
The strategy captures trending opportunities using simple MA crossover system. Default parameters are optimized with steady returns, suitable for algorithmic trading. Further improvements can be made by adding other indicators, optimizing parameters, and implementing stop loss. Overall, it is an effective trend following strategy for trending markets using crossover signals.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2020 | From Year |
| v_input_4 | true | Thru Month |
| v_input_5 | true | Thru Day |
| v_input_6 | 2112 | Thru Year |
| v_input_7 | true | Show Date Range |
| v_input_8 | 50 | MA long period |
| v_input_9 | 9 | MA short period |
| v_input_10 | 55 | RSI Trigger |
Source Pine Script
/*backtest
start: 2023-09-16 00:00:00
end: 2023-10-16 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © relevantLeader16058

//@version=4
strategy(shorttitle='Maximized Moving Average Crossing ',title='Maximized Moving Average Crossing (by Coinrule)', overlay=true, initial_capital=1000,  default_qty_type = strategy.percent_of_equity, default_qty_value = 30, commission_type=strategy.commission.percent, commission_value=0.1)

//Backtest dates
fromMonth = input(defval = 1,    title = "From Month",      type = input.integer, minval = 1, maxval = 12)
fromDay   = input(defval = 1,    title = "From Day",        type = input.integer, minval = 1, maxval = 31)
fromYear  = input(defval = 2020, title = "From Year",       type = input.integer, minval = 1970)
thruMonth = input(defval = 1,    title = "Thru Month",      type = input.integer, minval = 1, maxval = 12)
thruDay   = input(defval = 1,    title = "Thru Day",        type = input.integer, minval = 1, maxval = 31)
thruYear  = input(defval = 2112, title = "Thru Year",       type = input.integer, minval = 1970)

showDate  = input(defval = true, title = "Show Date Range", type = input.bool)

start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => time >= start and time <= finish ? true : false       // create function "within window of time"

//MA inputs and calculations
inlong=input(50, title='MA long period')
inshort=input(9, title='MA short period')

MAlong = sma(close, inlong)
MAshort= sma(close, inshort)

// RSI inputs and calculations
lengthRSI = (14)

RSI = rsi(close, lengthRSI)
RSI_Signal = input(55, title = 'RSI Trigger', minval=1)

//Entry and Exit
bullish = crossover(MAshort, MAlong)
bearish = crossunder(MAshort, MAlong)

strategy.entry(id="long", long = true, when = bullish and RSI > RSI_Signal and window())
strategy.close(id="long", when = bearish and window())


plot(MAshort, color=color.purple, linewidth=2)
plot(MAlong, color=color.red, linewidth=2)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Maximized-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual SMA Crossover StrategyPine Script · Trend following · 5m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d