Trend Tracking EMA Breakout Strategy
This is a trend tracking breakout strategy based on Exponential Moving Average (EMA). It judges the trend direction on the monthly, weekly and daily time frames, and executes specific entry and exit actions on the…
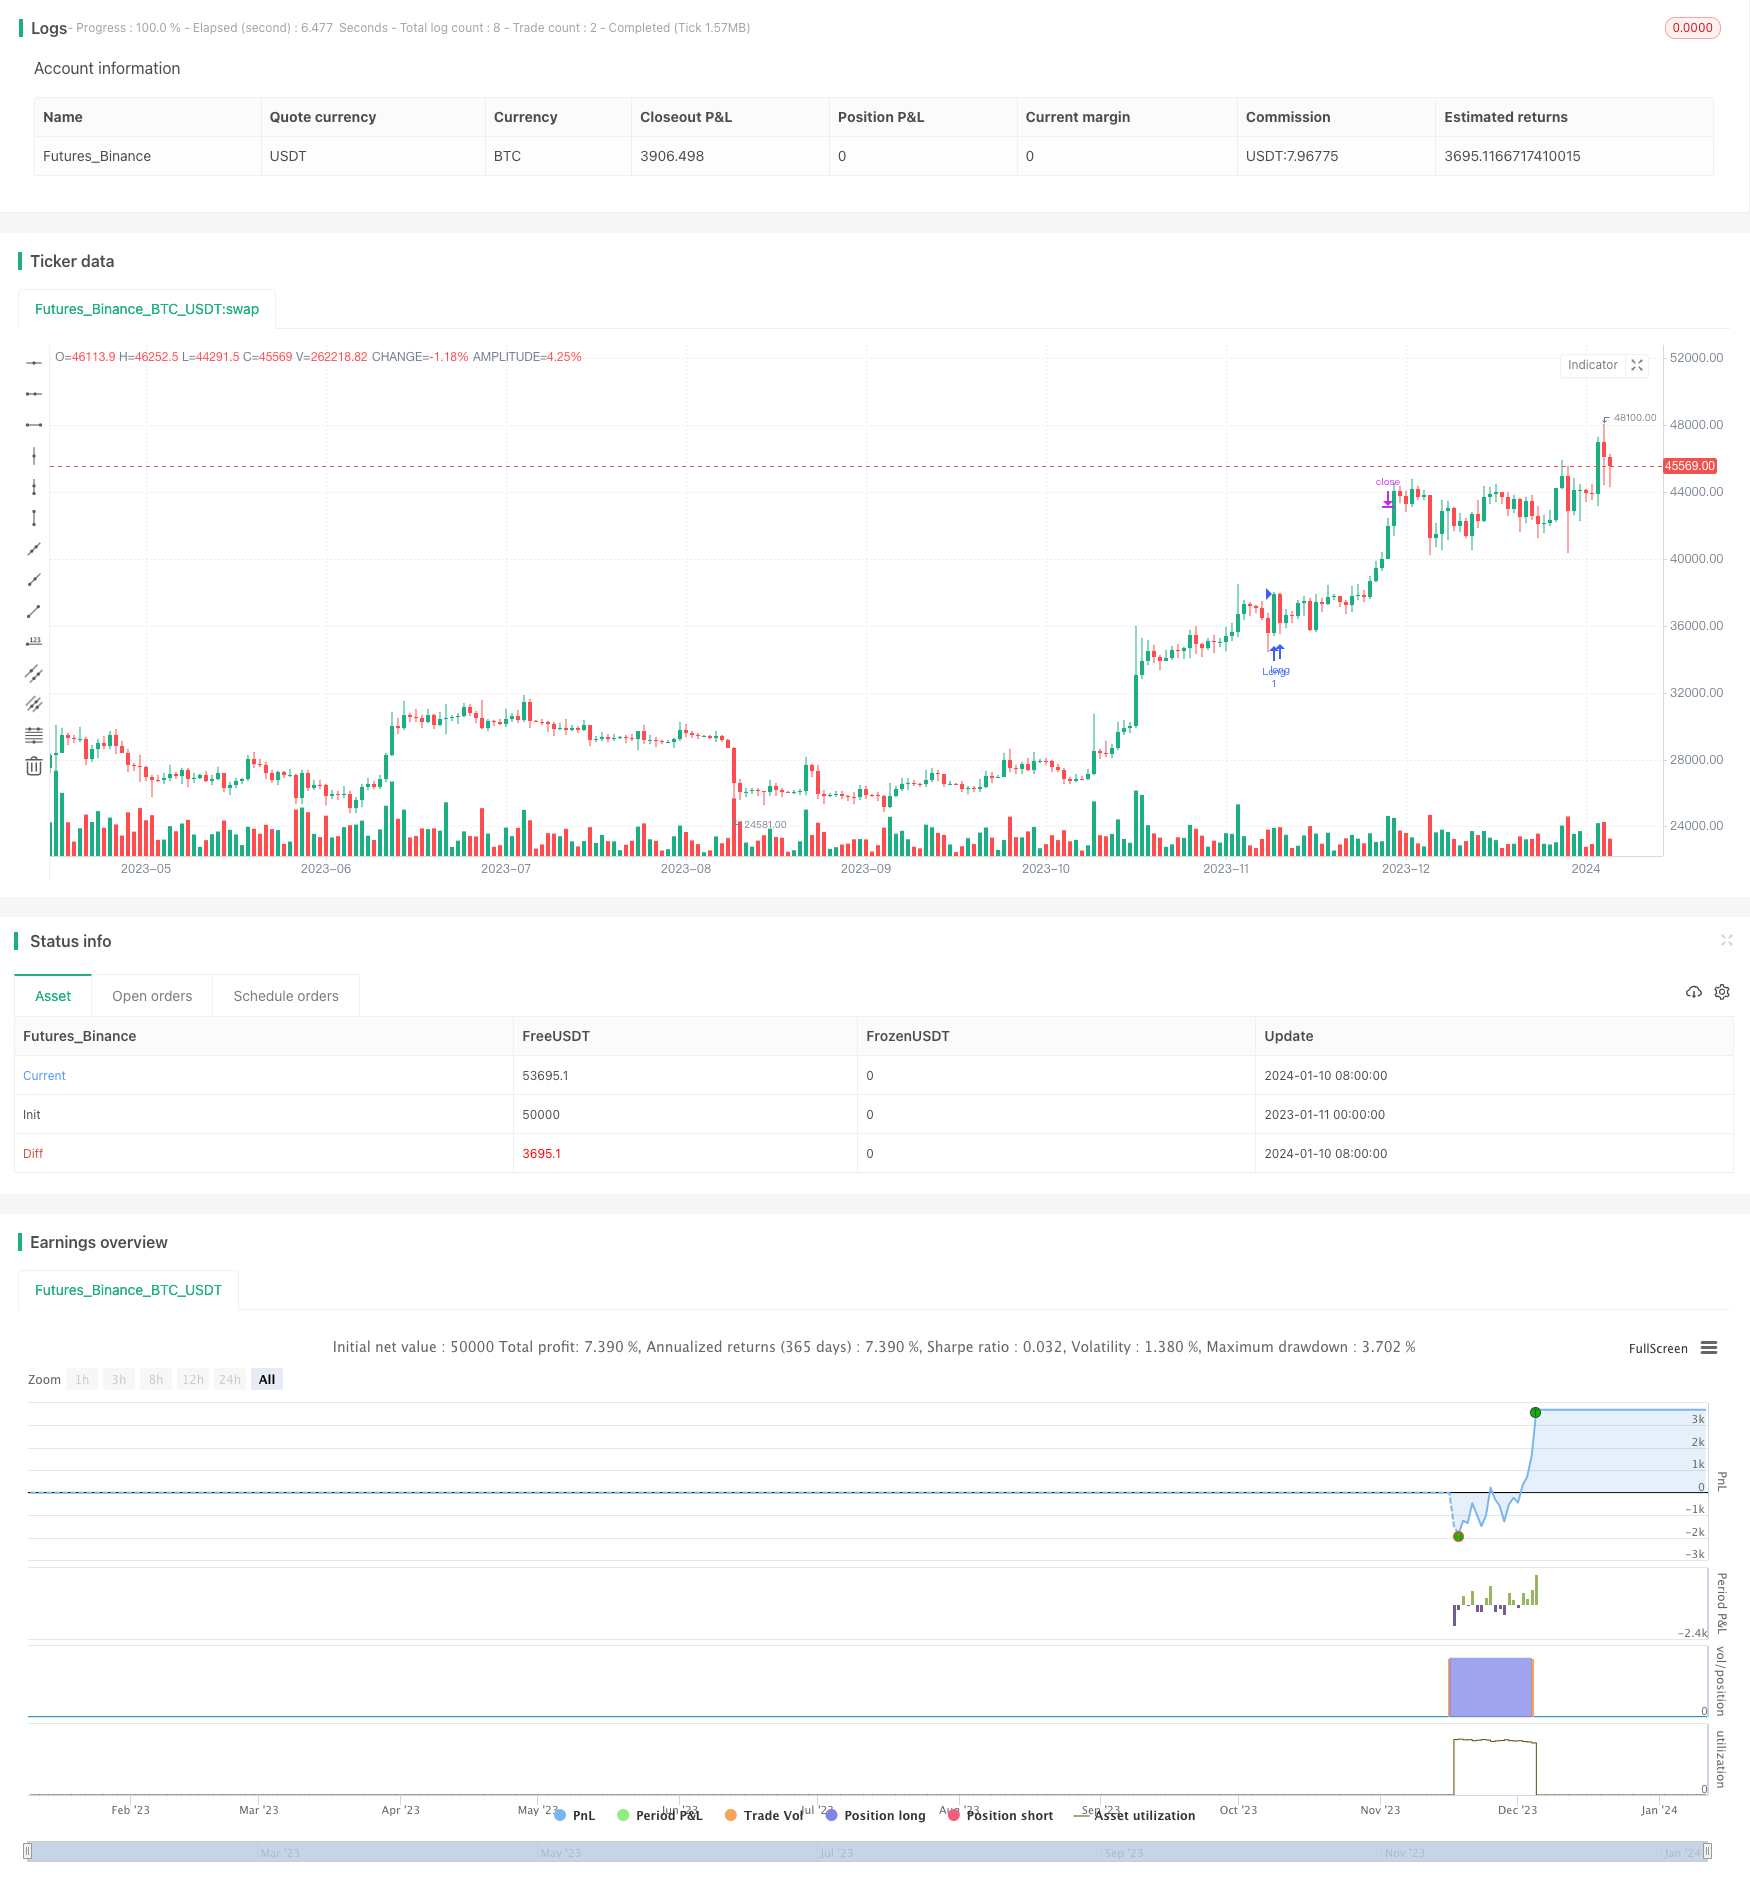
Overview
This is a trend tracking breakout strategy based on Exponential Moving Average (EMA). It judges the trend direction on the monthly, weekly and daily time frames, and executes specific entry and exit actions on the daily chart.
Strategy Logic
Trend Judgment
- On the monthly chart, price is above 8-day EMA and 8-day EMA is above 21-day EMA, indicating an uptrend;
- On the weekly chart, price is above 8-day EMA and 8-day EMA is above 21-day EMA, indicating an uptrend;
- On the daily chart, price is above 8-day EMA and 8-day EMA is above 21-day EMA, indicating an uptrend;
Entry Signal
- A pullback is seen on the daily chart with the low point touching yesterday's 8-day EMA;
- The pullback forms a Ring Low pattern with lower high and lower low;
- The closing price is higher than the previous day's high, forming a trend reversal signal.
Exit Signal
Set profit taking and stop loss standards for exiting.
Advantage Analysis
- Judging the trend on three time frames improves accuracy;
- Pullback to EMA forms support and increases entry certainty;
- Tracking trend runs has high profit potential;
Risk Analysis
- Inconsistent judgments across time frames may cause false signals;
- Excessive pullback magnitude may invalidate the strategy;
- Stop loss sweep may occur during flash crashes.
Optimization Directions
- Add MACD, RSI for supplementary judgment;
- Optimize EMA parameter settings;
- Adjust profit taking and stop loss range based on volatility.
Summary
The strategy has very good profit potential when the trend is correctly judged. Need to watch out for inaccurate trend judgment and excessive pullback causing false signals. Meanwhile, optimizing profit taking and stop loss settings is key to further improving the edge.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 10 | Profit Target % |
| v_input_float_2 | 10 | Stop Loss % |
| v_input_bool_1 | false | Relaxed Entry Rules |
Source Pine Script
/*backtest
start: 2023-01-11 00:00:00
end: 2024-01-11 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © the_daily_trader

//@version=5
// ---------------------        Start of Code        ---------------------
strategy("Swing Trades Validator", overlay=true, margin_long=100, pyramiding = 0)

// Indicator Display Checks
TakeProfitPercent       = input.float(title="Profit Target %", defval=10, minval=1, step=0.05)
StopLossPercent         = input.float(title="Stop Loss %", defval=10, minval=1, step=0.05)
pullbackchoice          = input.bool(false, "Relaxed Entry Rules")

// EMAs
emaH            = ta.ema(close, 8)
emaHyest        = ta.ema(close[1], 8)
emaHyest1       = ta.ema(close[2], 8)
emaHyest2       = ta.ema(close[3], 8)
emaL            = ta.ema(close, 21)
emaLyest        = ta.ema(close[1], 21)
emaLyest1       = ta.ema(close[2], 21)
emaLyest2       = ta.ema(close[3], 21)
emaf            = ta.ema(close, 50)
emath           = ta.ema(close, 200)
emathhigh       = ta.ema(high, 200)
emathlow        = ta.ema(low, 200)
emaslowmonthly  = request.security(syminfo.tickerid, "M", emaL) // Monthly 21ema
emafastmonthly  = request.security(syminfo.tickerid, "M", emaH) // Monthly 8ema
emaslowweekly   = request.security(syminfo.tickerid, "W", emaL) // Weekly 21ema
emafastweekly   = request.security(syminfo.tickerid, "W", emaH) // Weekly 8ema
emaslowdaily    = request.security(syminfo.tickerid, "D", emaL) // Daily 21ema
emafastdaily    = request.security(syminfo.tickerid, "D", emaH) // Daily 8ema
emafdaily       = request.security(syminfo.tickerid, "D", emaf) // Daily 50ema
emathdaily      = request.security(syminfo.tickerid, "D", emath) // Daily ema
emathdailyhigh  = request.security(syminfo.tickerid, "D", emathhigh) // Daily ema High
emathdailylow   = request.security(syminfo.tickerid, "D", emathlow) // Daily ema Low
ema21yest       = request.security(syminfo.tickerid, "D", emaLyest) // Daily 21ema 1 day ago
ema21yest1      = request.security(syminfo.tickerid, "D", emaLyest1) // Daily 21ema 2 days ago
ema21yest2      = request.security(syminfo.tickerid, "D", emaLyest2) // Daily 21ema 3 days ago
ema8yest        = request.security(syminfo.tickerid, "D", emaHyest) // Daily 8ema 1 day ago
ema8yest1       = request.security(syminfo.tickerid, "D", emaHyest1) // Daily 8ema 2 days ago
ema8yest2       = request.security(syminfo.tickerid, "D", emaHyest2) // Daily 8ema 3 days ago


// Prices
monthopen       = request.security(syminfo.tickerid, 'M', open, barmerge.gaps_off, barmerge.lookahead_on)
monthclose      = request.security(syminfo.tickerid, 'M', close, barmerge.gaps_off, barmerge.lookahead_on)
weekopen        = request.security(syminfo.tickerid, 'W', open, barmerge.gaps_off, barmerge.lookahead_on)
weekclose       = request.security(syminfo.tickerid, 'W', close, barmerge.gaps_off, barmerge.lookahead_on)
dayopen         = request.security(syminfo.tickerid, 'D', open, barmerge.gaps_off, barmerge.lookahead_on)
dayclose        = request.security(syminfo.tickerid, 'D', close, barmerge.gaps_off, barmerge.lookahead_on)
threedayhigh    = request.security(syminfo.tickerid, 'D', high[3], barmerge.gaps_off, barmerge.lookahead_on)
twodayhigh      = request.security(syminfo.tickerid, 'D', high[2], barmerge.gaps_off, barmerge.lookahead_on)
yesthigh        = request.security(syminfo.tickerid, 'D', high[1], barmerge.gaps_off, barmerge.lookahead_on)
yestlow         = request.security(syminfo.tickerid, 'D', low[1], barmerge.gaps_off, barmerge.lookahead_on)

// Conditions
monthlybullish          = emafastmonthly > emaslowmonthly
monthlybullishprice     = close > emafastmonthly
monthlybullishcandle    = monthclose > monthopen
weeklybullish           = emafastweekly > emaslowweekly
weeklybullishprice      = close > emafastweekly
weeklybullishcandle     = weekclose > weekopen
dailybullish1           = emafdaily > emathdaily
dailybullish2           = emafastdaily > emaslowdaily
dailybullishprice       = close > emafastdaily
dailybullishcandle      = dayclose > dayopen
ringlow                 = yestlow <= ema8yest
aggropullback           = twodayhigh < threedayhigh
pullback                = (pullbackchoice ? aggropullback : 0)
pullbackfailure         = dayclose > yesthigh and yesthigh < twodayhigh or pullback
emasetup                = ema8yest > ema21yest and ema8yest1 > ema21yest1 and ema8yest2 > ema21yest2

// Target Profit and Stop Loss Inputs
// Input parameters can be found at the beginning of the code
ProfitTarget        = (close * (TakeProfitPercent / 100)) / syminfo.mintick
StopLoss            = (close * (StopLossPercent / 100)) / syminfo.mintick

longCondition = monthlybullish and monthlybullishprice and weeklybullish and weeklybullishprice and dailybullish1 and dailybullish2 and dailybullishprice and monthlybullishcandle and weeklybullishcandle and dailybullishcandle and ringlow and pullbackfailure and emasetup

if (longCondition)
    strategy.entry("Long", strategy.long)
    strategy.exit ("Exit", "Long", profit = ProfitTarget, loss = StopLoss)
    // strategy.close("Long", qty_percent = 100)


// -----------xxxxxxxxxxx------------- End of Code -----------xxxxxxxxxxx---------------Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Tracking-EMA-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- MA Trendline Breakthrough StrategyPine Script · Breakout · 1d
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Multi Technical Indicator Dynamic Wave Trading StrategyPine Script · Breakout · 1h