Strategy vault / Trend following
Triple Moving Average Crossover Strategy
The triple moving average crossover strategy uses the crossover of moving averages over different time periods as trading signals, belonging to trend-following strategies. It uses three moving averages, including…
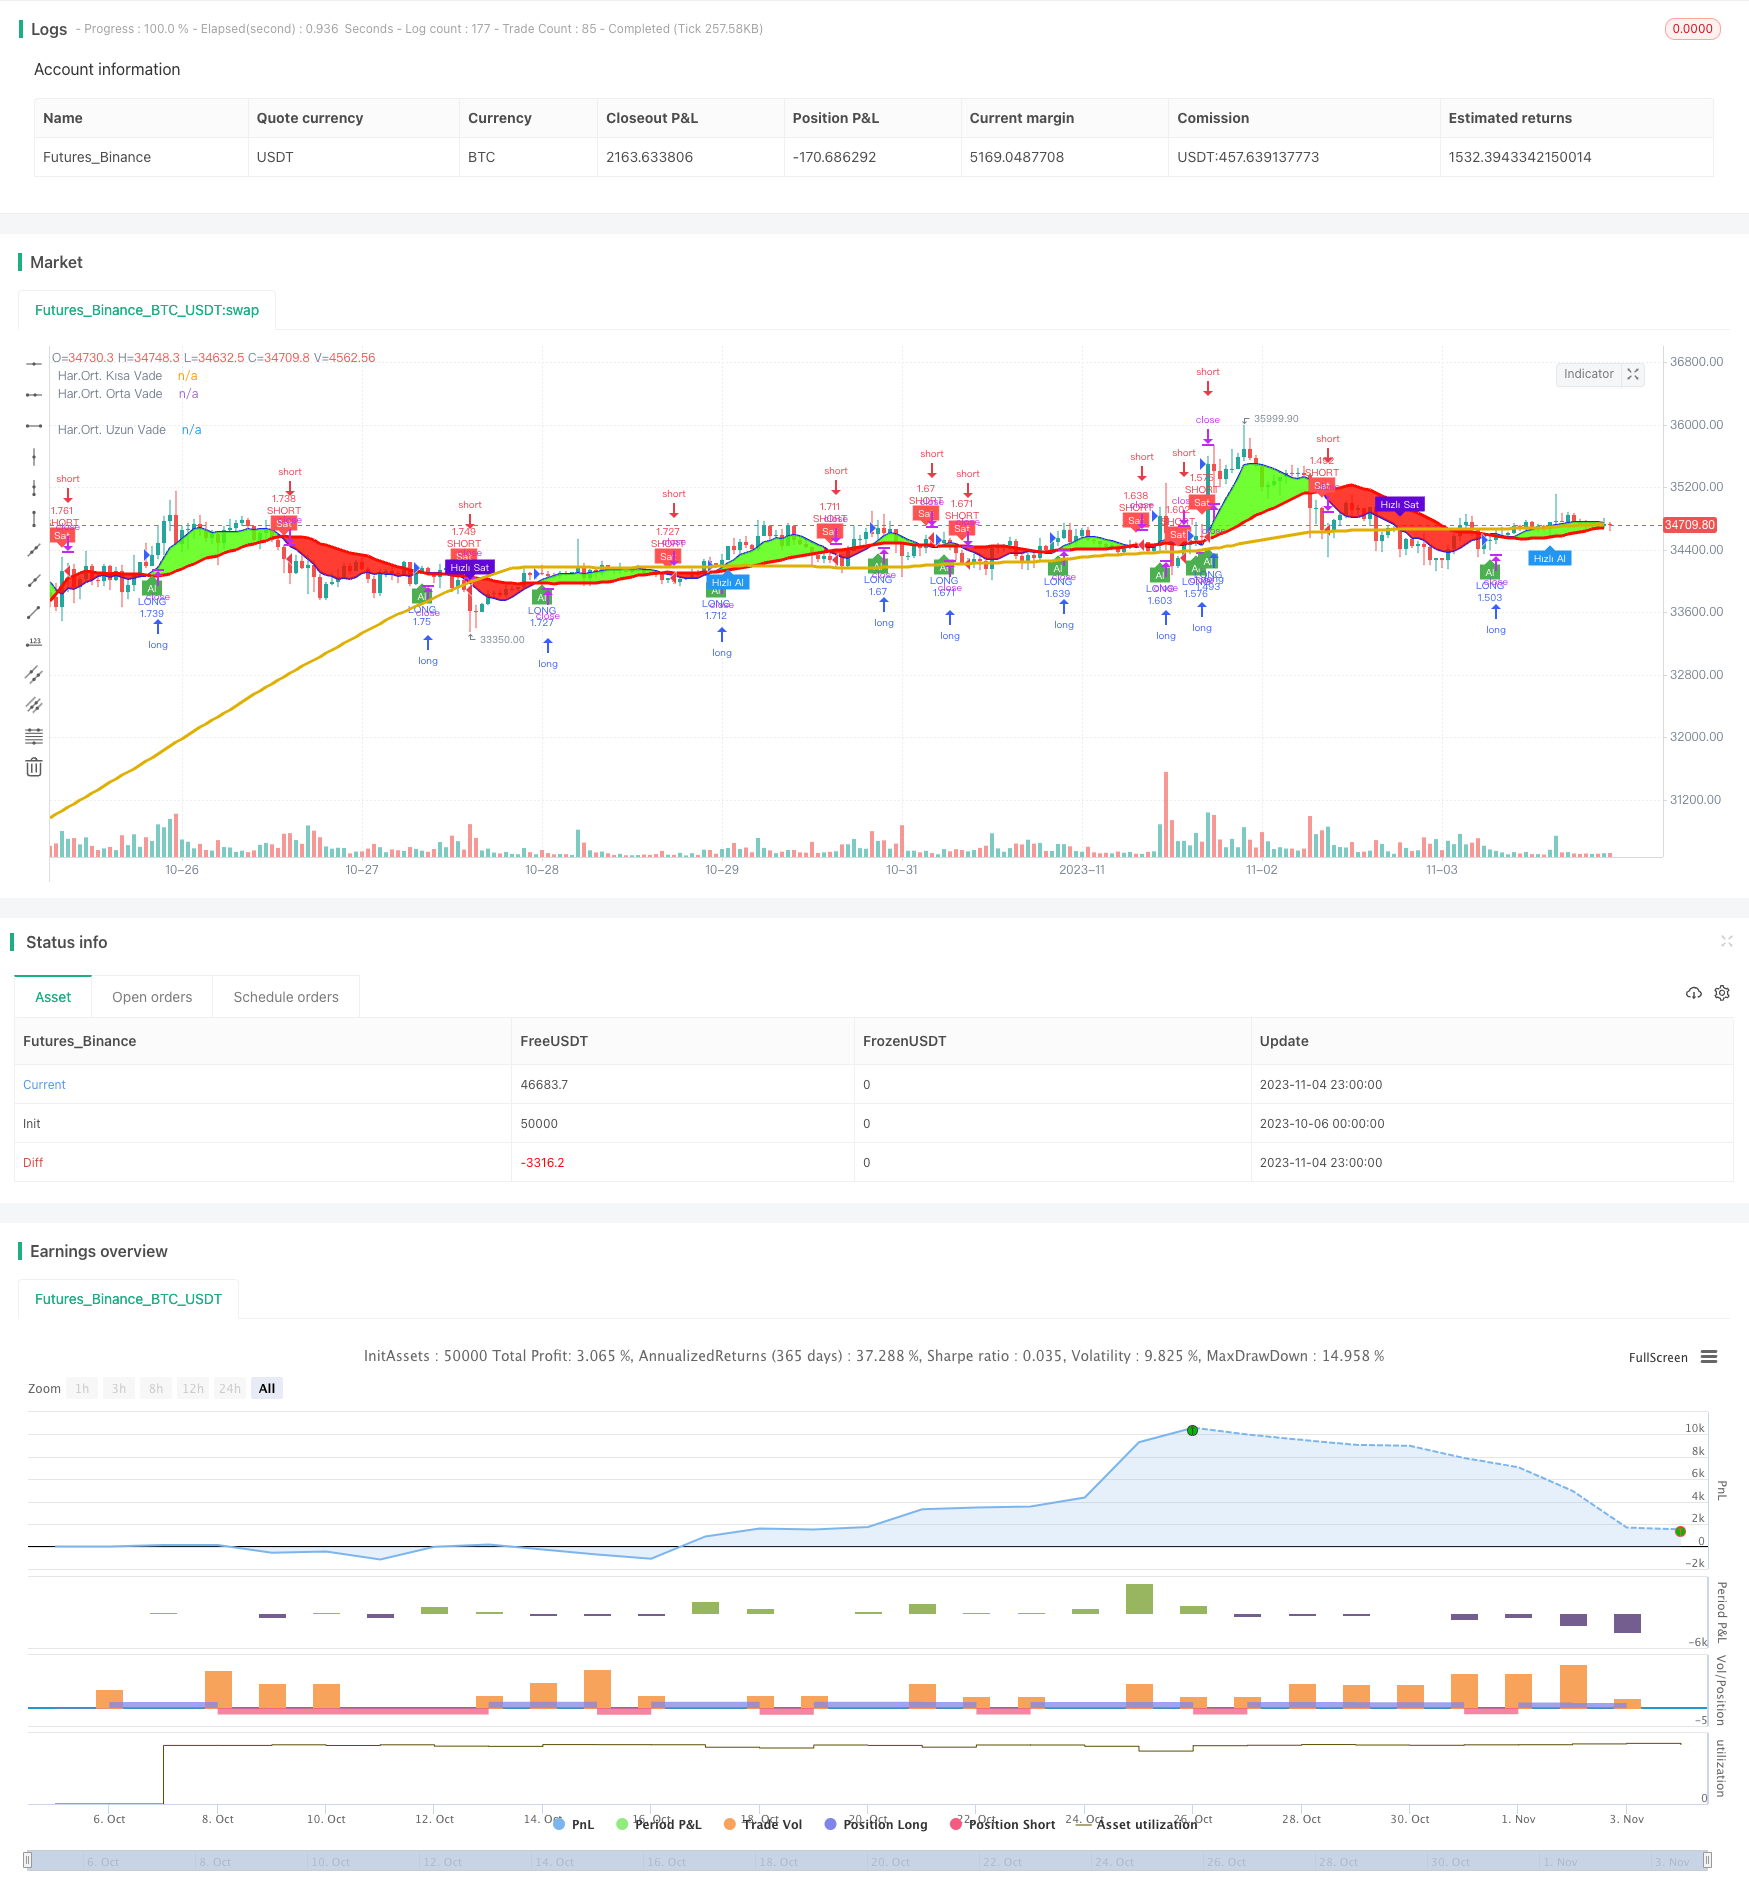
Overview
The triple moving average crossover strategy uses the crossover of moving averages over different time periods as trading signals, belonging to trend-following strategies. It uses three moving averages, including short-term, medium-term, and long-term moving averages, to generate trading signals based on their crossovers.
Strategy Logic
Firstly, the strategy calculates the short-term (default 7 days), medium-term (default 25 days), and long-term (default 99 days) moving averages. Then it generates trading signals according to the following rules:
When the short-term MA crosses above the medium-term MA, a buy signal is generated.
When the short-term MA crosses below the medium-term MA, a sell signal is generated.
When the short-term MA crosses above the long-term MA, a fast buy signal is generated.
When the short-term MA crosses below the long-term MA, a fast sell signal is generated.
The strategy believes that the short-term MA crossing above the medium-term MA indicates an uptrend, so a buy signal is generated. And the short-term MA crossing below the medium-term MA indicates a downtrend, so a sell signal is generated. Similarly, the crossover between the short-term MA and long-term MA also generates fast trading signals to capture longer-term trend changes.
Advantage Analysis
The strategy logic is simple and easy to understand and implement.
Using multi-timeframe analysis can effectively capture changes in market trends.
The parameters can be optimized by adjusting the MA periods.
The visual crossover signals intuitively reflect trend changes.
Risk Analysis
MAs have lagging issues and may miss trend reversal points.
Too many false signals when the short-term MA crosses above the long-term MA in bull markets.
Too many false signals when the short-term MA crosses below the long-term MA in bear markets.
Fast trading signals may be too sensitive, increasing trading frequency and commissions.
Proper adjustments of MA periods or adding filter conditions can help optimize and reduce false signals. Shortening fast trading periods may also lower trading frequency.
Optimization Directions
Add filter conditions, such as generating signals only when meeting certain trading volumes or price change percentages.
Combine with other indicators like MACD, KDJ to avoid erroneous trades when no clear trend.
Optimize MA period combinations to reduce false signals.
Distinguish bull and bear markets, optimize buy and sell parameters separately.
Consider trading costs, adjust fast trading parameters to control frequency.
Summary
The triple MA crossover strategy is relatively simple, judging the trend direction through crossover of different timeframe MAs to generate trading signals. It is easy to implement with flexible parameter adjustments to capture trend changes. But it also has the issues of MA lagging and excessive false signals. Methods like adding filters and optimizing parameter combinations can improve the strategy. It suits traders interested in trend crossovers for optimization and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 7 | Kısa Vade - Gün |
| v_input_2 | 25 | Orta Vade - Gün |
| v_input_3 | 99 | Uzun Vade - Gün |
| v_input_4 | 2020 | Backtest Başlangıç Tarihi |
Source Pine Script
/*backtest
start: 2023-10-06 00:00:00
end: 2023-11-05 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © dadashkadir

//@version=4
strategy("Üç Hareketli Ortalama Str.", overlay=true, initial_capital=10000, commission_value=0.047, default_qty_type=strategy.percent_of_equity, default_qty_value=100, pyramiding=0, calc_on_order_fills=true)

kisa = input(title = "Kısa Vade - Gün", defval = 7,  minval = 1)
orta = input(title = "Orta Vade - Gün", defval = 25, minval = 1)
uzun = input(title = "Uzun Vade - Gün", defval = 99, minval = 1)

sma7  = sma(close, kisa)
sma25 = sma(close, orta)
sma99  = sma(close, uzun)

alTrend  = plot (sma7, color=#2323F1, linewidth=2, title="Har.Ort. Kısa Vade", transp=0)
satTrend = plot (sma25, color=#FF0C00, linewidth=3, title="Har.Ort. Orta Vade", transp=0)
ort99    = plot (sma99, color=#DFB001, linewidth=3, title="Har.Ort. Uzun Vade", transp=0)

zamanaralik = input (2020, title="Backtest Başlangıç Tarihi")

al  = crossover (sma7, sma25) and zamanaralik <= year
sat = crossover (sma25, sma7) and zamanaralik <= year

hizlial = crossover (sma7, sma99) and zamanaralik <= year
hizlisat = crossover (sma99, sma7) and zamanaralik <= year

alkosul  = sma7 >= sma25
satkosul = sma25 >= sma7

hizlialkosul  = sma7 >= sma99
hizlisatkosul = sma99 >= sma7

plotshape(al,  title = "Buy",  text = 'Al',  style = shape.labelup,   location = location.belowbar, color= color.green, textcolor = color.white, transp = 0, size = size.tiny)
plotshape(sat, title = "Sell", text = 'Sat', style = shape.labeldown, location = location.abovebar, color= color.red,   textcolor = color.white, transp = 0, size = size.tiny)

plotshape(hizlial,  title = "Hızlı Al",  text = 'Hızlı Al',  style = shape.labelup,   location = location.belowbar, color= color.blue, textcolor = color.white, transp = 0, size = size.tiny)
plotshape(hizlisat, title = "Hızlı Sat", text = 'Hızlı Sat', style = shape.labeldown, location = location.abovebar, color= #6106D6 , textcolor = color.white, transp = 0, size = size.tiny)

fill (alTrend, satTrend, color = sma7 >= sma25? #4DFF00 : #FF0C00, transp=80, title="Al-Sat Aralığı")
//fill (ort99, satTrend, color = sma7 >= sma25? #6106D6 : color.blue, transp=80, title="Hızlı Al-Sat Aralığı")

if (al)
    strategy.entry("LONG", strategy.long)
if (sat)
    strategy.entry("SHORT", strategy.short)
//if (hizlial)
//    strategy.entry("My Short Entry Id", strategy.long)
//if (hizlisat)
//    strategy.entry("My Short Entry Id", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Triple-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Moving Average Convergence Trend Tracking StrategyPine Script · Trend following · 1d
- Dual Moving Average Crossover Strategy with Stop Loss and Take ProfitPine Script · Trend following · 4h
- Dual SMA Crossover StrategyPine Script · Trend following · 5m