Turnaround Tuesday Strategy Weekend Filter
The strategy is named "Turnaround Tuesday Strategy (Weekend Filter)". The main idea is to buy at the Monday open and sell at the Wednesday open when certain conditions based on moving averages and other filters are…
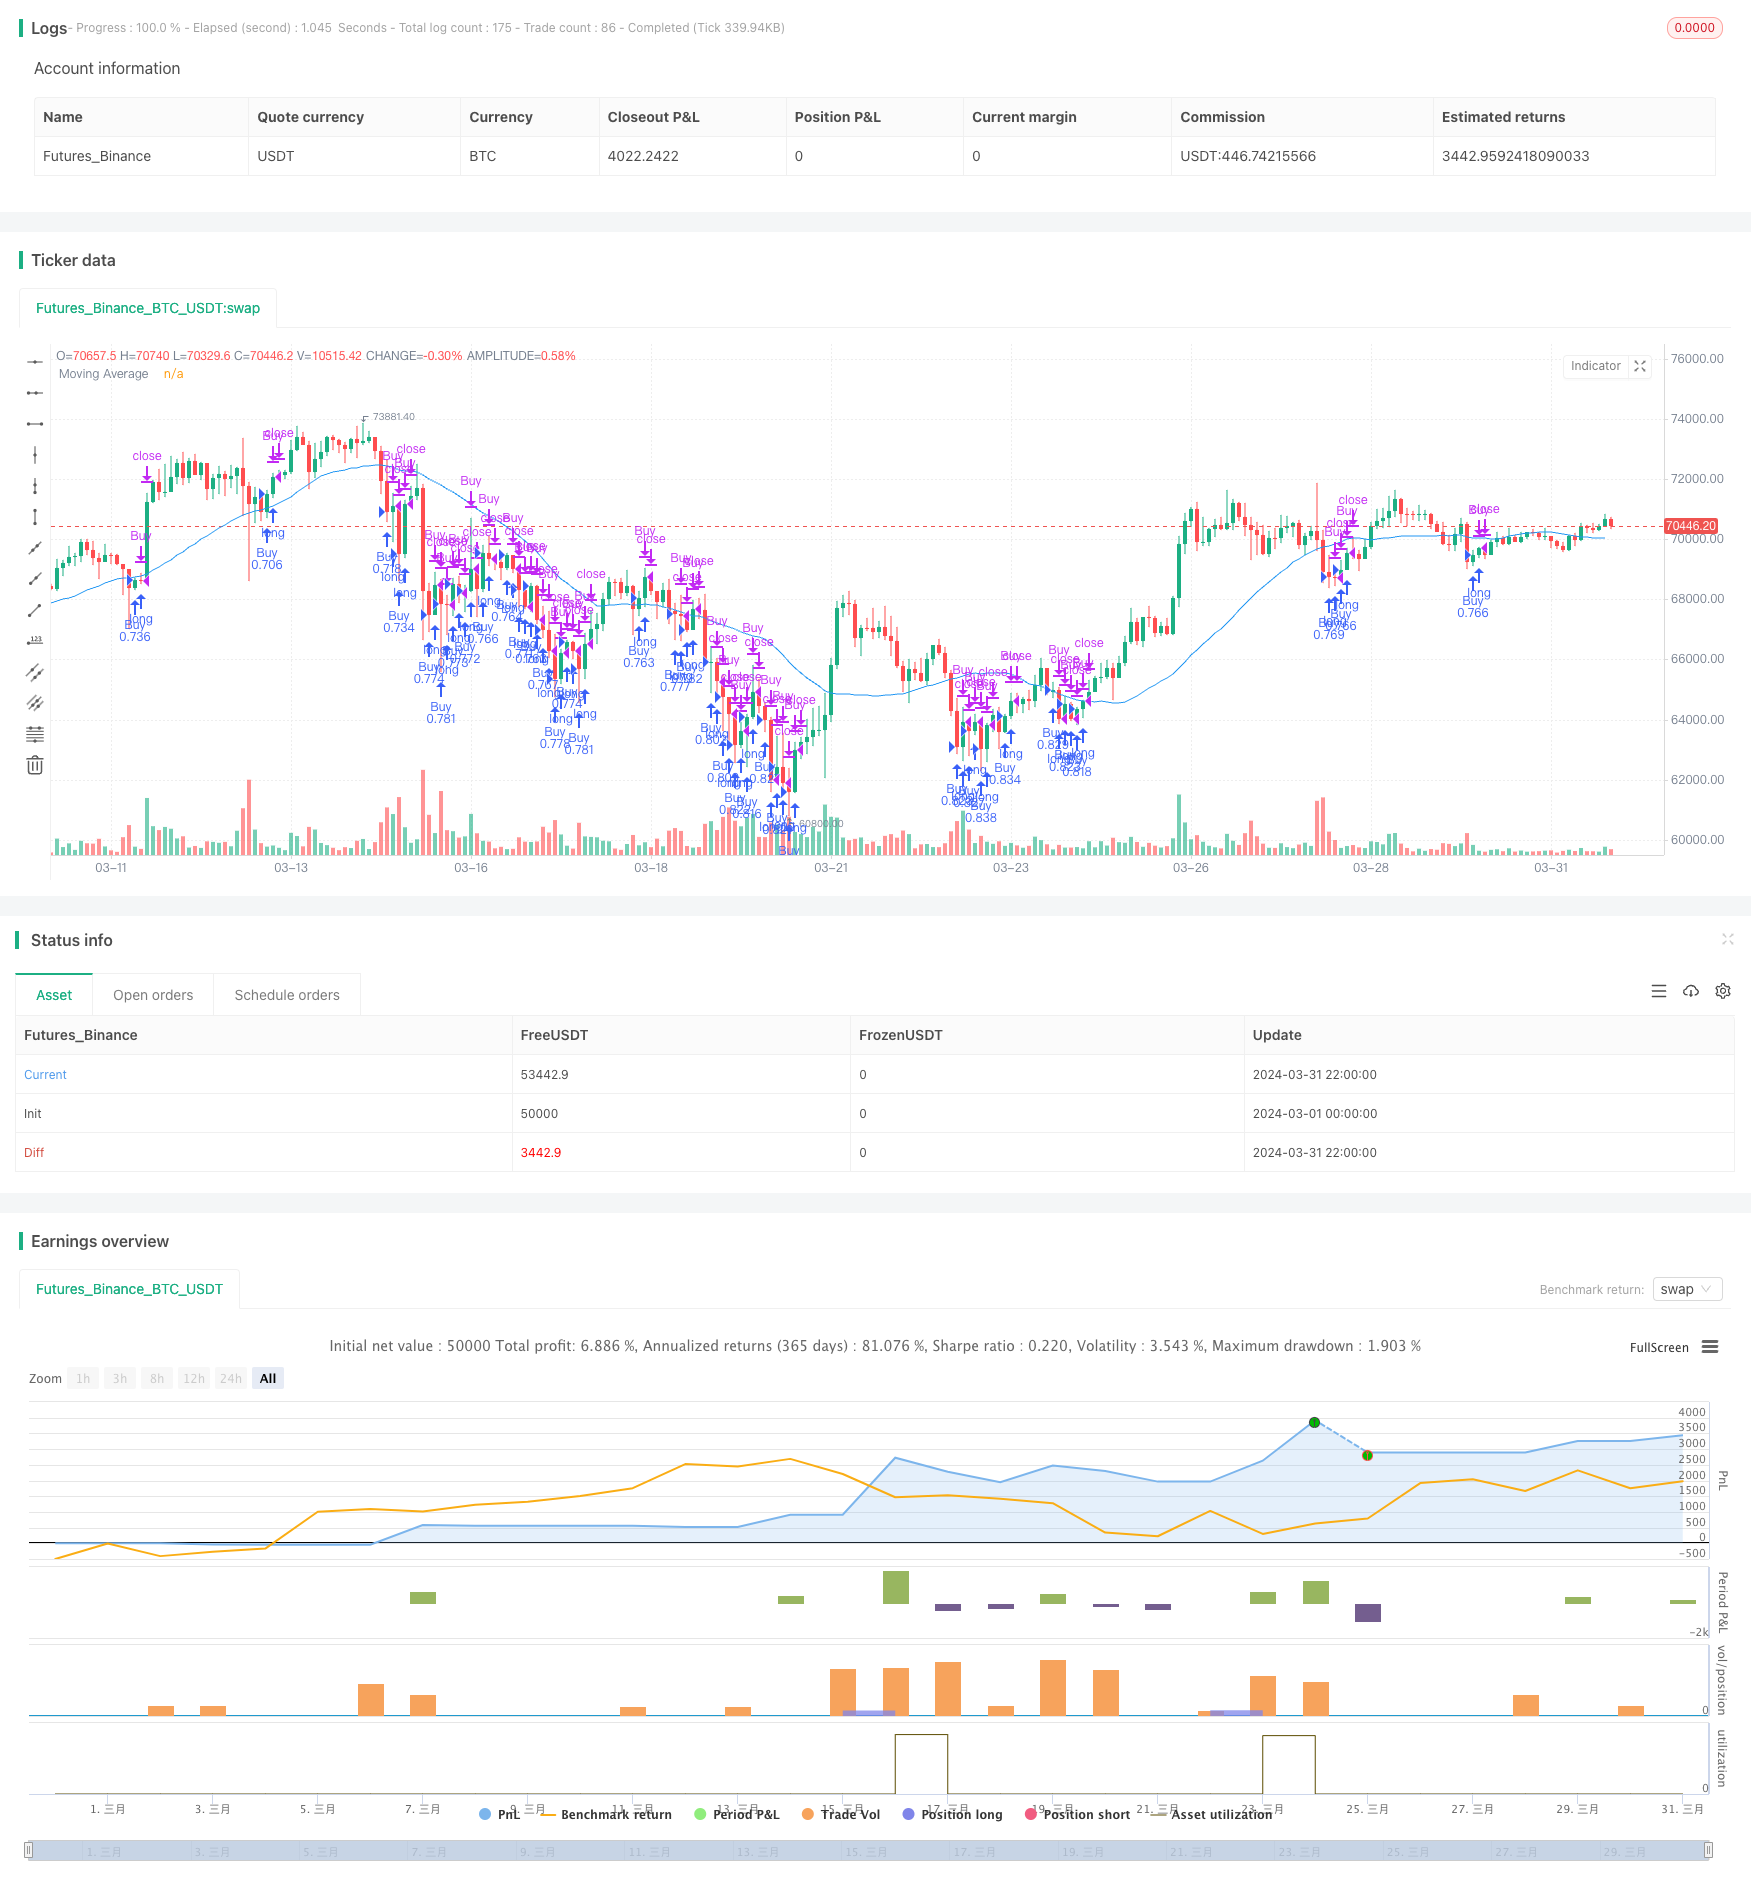
Overview
The strategy is named "Turnaround Tuesday Strategy (Weekend Filter)". The main idea is to buy at the Monday open and sell at the Wednesday open when certain conditions based on moving averages and other filters are met, in order to capture the Tuesday turnaround. By filtering with RSI, ATR, and excluding specific times like May, the strategy aims to improve its win rate and risk-reward ratio.
Strategy Principles
- Use the 30-day moving average as a trend determination basis. When the previous trading day's close is below the 30-day MA, it is considered a downtrend and meets one of the buying conditions.
- Use the 3-day RSI and 10-day ATR as filter conditions. When the 3-day RSI is less than 51 and the close relative to the 10-day ATR is less than 95%, the market sentiment is considered pessimistic but without extreme conditions, meeting the buying conditions.
- Exclude the month of May due to the "Sell in May and go away" effect, as the stock market tends to be sluggish.
- Combining the above conditions, buy on Monday when all filter conditions are met, and sell at the Wednesday open.
Strategy Advantages
- The combination of moving average and sentiment indicators can effectively capture the Tuesday turnaround.
- The dual filtering of RSI and ATR excludes trades in extreme conditions, improving the strategy's win rate and risk-reward ratio.
- Excluding May avoids trading during typically underperforming periods, enhancing strategy performance.
- Trading only from Monday to Wednesday results in low trading frequency and small commission costs.
Strategy Risks
- The strategy may underperform when the trend is strong and the reversal is not evident.
- Fixed buying and selling times may miss better entry and exit points, limiting the strategy's flexibility and profit potential.
- Relying on indicator judgments risks invalidity when the market changes drastically.
- Monthly judgments based on historical experience do not guarantee future situations will be the same, posing a timeliness risk.
Strategy Optimization Directions
- Consider introducing more effective filtering indicators, such as volume and volatility, to improve the strategy's robustness and adaptability.
- Optimize the selection of buying and selling timings, such as adding intraday breakout confirmation conditions, to increase flexibility and profit potential.
- For holding period optimization, consider longer holding times to more fully capture trends.
- Set different parameters for different market conditions to enhance the strategy's adaptability.
- Incorporate position management and risk control modules to cope with extreme market situations.
Summary
The Turnaround Tuesday Strategy (Weekend Filter) uses a combination of moving averages, RSI, ATR, and other indicators to buy and sell at specific times, aiming to capture the Tuesday turnaround. The strategy has low trading frequency, small commission costs, and improves its win rate and risk-reward ratio through time period and indicator filtering. However, the strategy also has certain limitations and risks, such as underperformance in trending markets and fixed buying/selling times and holding periods. Future optimizations can introduce more filtering conditions, optimize exit timings, dynamically adjust parameters, manage positions, and control risk to better adapt to changing market conditions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 30 | Moving Average Period |
| v_input_2 | true | Use RSI Filter |
| v_input_3 | true | Use ATR Filter |
| v_input_4 | true | Exclude May |
| v_input_5 | timestamp(2009-01-01 00:00:00) | Start Backtest |
| v_input_6 | timestamp(2025-01-01 00:00:00) | End Backtest |
Source Pine Script
/*backtest
start: 2024-03-01 00:00:00
end: 2024-03-31 23:59:59
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © muikol

//@version=5
strategy("Turnaround Tuesday", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.035)

// Inputs for MA period, filter_1, filter_2, month filter, and testing period
ma_period = input(30, title="Moving Average Period")
use_filter_1 = input(true, title="Use RSI Filter")
use_filter_2 = input(true, title="Use ATR Filter")
use_month_filter = input(true, title="Exclude May")
start_date = input(defval=timestamp("2009-01-01 00:00:00"), title="Start Backtest")
end_date = input(defval=timestamp("2025-01-01 00:00:00"), title="End Backtest")

// Data calculations
MA_tt = ta.sma(close, ma_period)
atr10 = ta.atr(10)
rsi3 = ta.rsi(close, 3)
c_1 = close[1]

// Entry conditions
isMonday = dayofweek == dayofweek.monday
bear = close[1] < MA_tt[1]
filter_1 = use_filter_1 ? rsi3[1] < 51 : true
filter_2 = use_filter_2 ? c_1/atr10[1] < 95 : true
notMay = use_month_filter ? month != 5 : true
entryCondition = isMonday and bear and notMay and filter_1 and filter_2

// Date check
inTestPeriod = true
// Exit conditions
isWednesdayOpen = dayofweek == dayofweek.wednesday

// Entry and exit triggers
if entryCondition and inTestPeriod
    strategy.entry("Buy", strategy.long)

if isWednesdayOpen and strategy.position_size > 0 and inTestPeriod
    strategy.close("Buy")

// Plot the moving average
plot(MA_tt, title="Moving Average", color=color.blue)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-04-30. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Turnaround-Tuesday-Strategy-Weekend-Filter.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m