Weekly Swing Trading Strategy
The strategy uses a combination of dual exponential moving average (EMA) crossovers and relative strength index (RSI) to identify potential trading opportunities in the markets. It is suited for traders looking to…
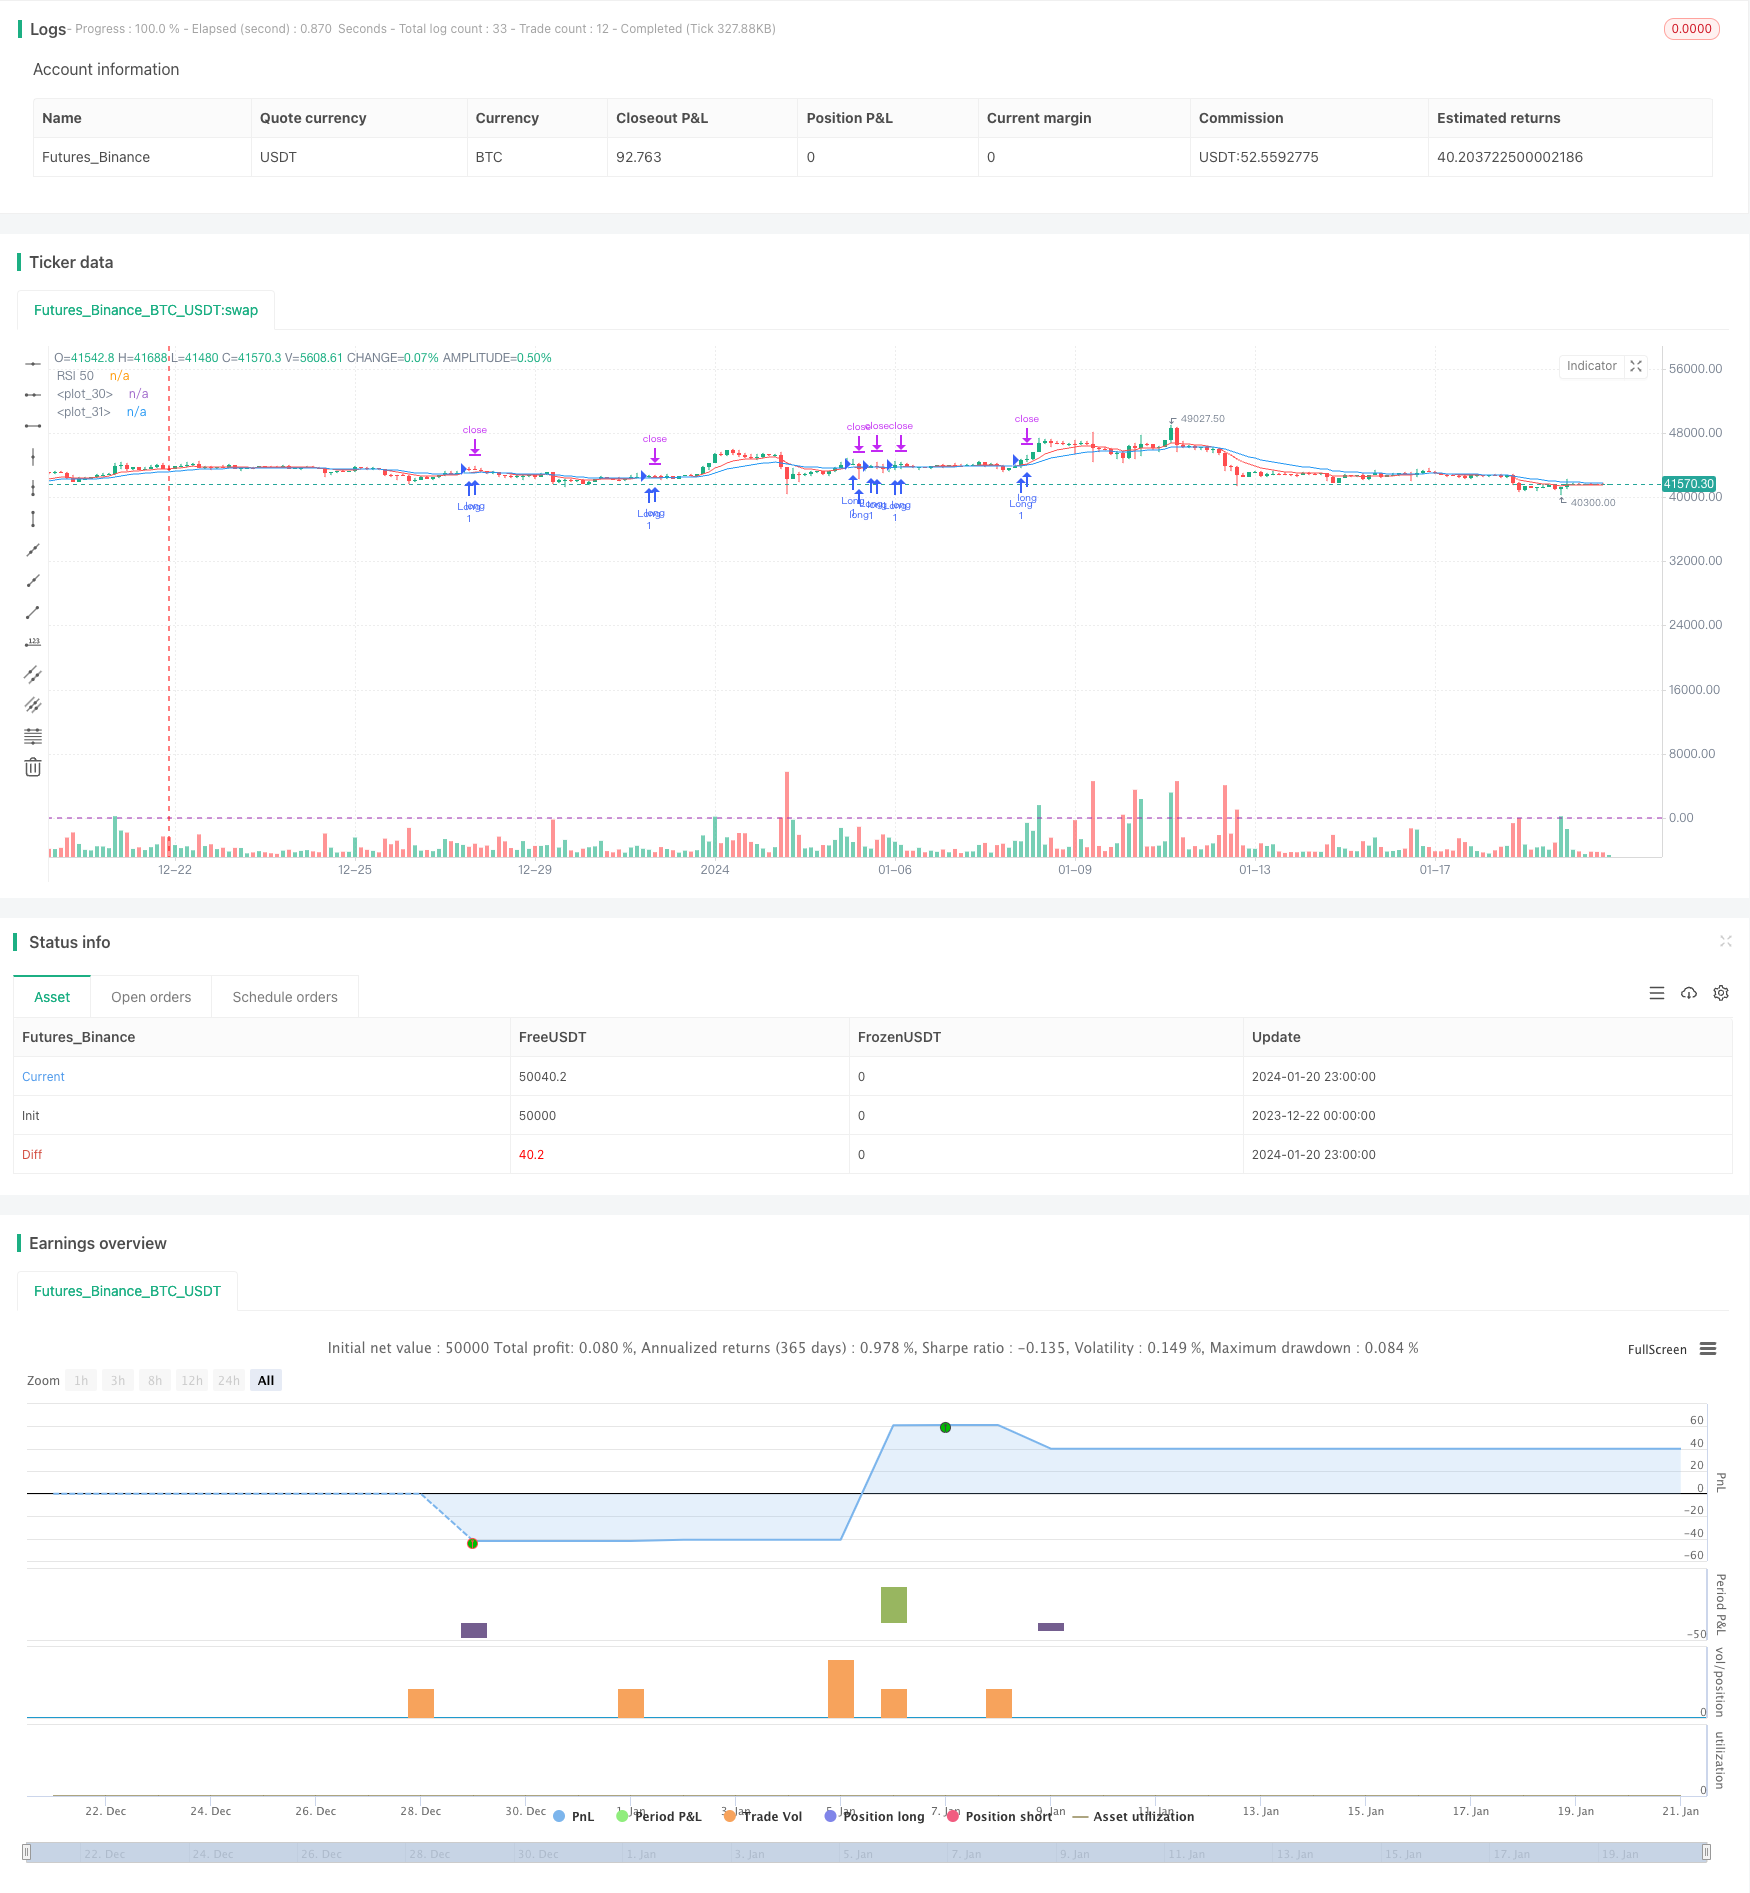
Overview
The strategy uses a combination of dual exponential moving average (EMA) crossovers and relative strength index (RSI) to identify potential trading opportunities in the markets. It is suited for traders looking to track bigger price moves and swings.
Strategy Logic
The core idea is to buy when the faster 9-week EMA moves up and crosses above the slower 21-week EMA, as this signals the market trend may be strengthening. Then if RSI is above 50, it confirms the buy signal as it means upward momentum is strong.
Specifically, a long entry signal is triggered when the 9-week EMA crosses above the 21-week EMA, and 14-week RSI is greater than 50. Positions are then sized for 2% account risk, with a 5% stop loss and 10% profit target. A 3% trailing stop also locks in profits.
The sell signal is based on opposite logic: if the 9-week EMA crosses below the 21-week EMA or if RSI drops below 50. This indicates the short-term trend has reversed down.
Advantages
- Dual indicators identify opportunities with higher quality signals
- RSI helps confirm trend and filter false breakouts
- Well-suited for tracking larger price swings
- Risk management with stop loss and take profit
- Trailing stop helps optimizes profit protection
Risks
- Fast EMA crossovers can generate more noise
- Possibility of false signals from RSI
- Risk reward ratio confined to 2:1
- Does not account for trading costs
- Many parameters need optimization like MA periods, RSI settings etc
This can be optimized by systematically testing combinations of these parameters. Additional filters in condition logic can reduce noisy trades. Considering fundamentals can provide more confirmation.
Enhancement Opportunities
- Test EMA period parameters for best mix
- Optimize RSI parameters to reduce false signals
- Add additional confirmation indicators like Bollinger Band Width
- Combine with fundamental analysis for higher quality signals
- Strategy can extend across multiple timeframes like intraday
Conclusion
The strategy leverages the power of EMA and RSI to identify potential opportunities within bigger trends. It provides clear risk management rules to effectively control risk per trade. Further testing and optimizing parameters can continue enhancing performance. It offers an effective way to trade larger cyclical swings in markets.
Source Pine Script
/*backtest
start: 2023-12-22 00:00:00
end: 2024-01-21 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Weekly Swing Trading Strategy", overlay=true)

// Entry Indicators
shortEma = ema(close, 9)
longEma = ema(close, 21)
rsiValue = rsi(close, 14)

// Entry Condition
longCondition = crossover(shortEma, longEma) and rsiValue > 50
if (longCondition)
    strategy.entry("Long", strategy.long)

// Position Sizing (2% risk per trade)
riskPerTrade = 0.02
stopLossPercent = 0.05 // 5% stop loss
stopLossPrice = close * (1 - stopLossPercent)
strategy.exit("Stop Loss", "Long", stop=stopLossPrice)

// Profit Target and Trailing Stop
profitTargetPercent = 0.10 // 10% profit target
profitTargetPrice = close * (1 + profitTargetPercent)
trailStopPercent = 0.03 // 3% trailing stop
strategy.exit("Take Profit", "Long", limit=profitTargetPrice, trail_price=trailStopPercent, trail_offset=trailStopPercent)

// Exit Strategy
exitCondition = crossunder(shortEma, longEma) or rsiValue < 50 // Exit when EMAs cross or RSI drops below 50
strategy.close("Long", when=exitCondition)

plot(shortEma, color=color.red)
plot(longEma, color=color.blue)
hline(50, "RSI 50", color=color.purple)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Weekly-Swing-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Mean Reversion StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Momentum Breakthrough TTM StrategyPine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m