Strategy vault / Trend following
Adaptive Trend Flow Multiple Filter Trading Strategy
This strategy is an adaptive trend following system based on multiple technical indicator filters. It combines various technical indicators including Exponential Moving Average (EMA), Simple Moving Average (SMA), and…
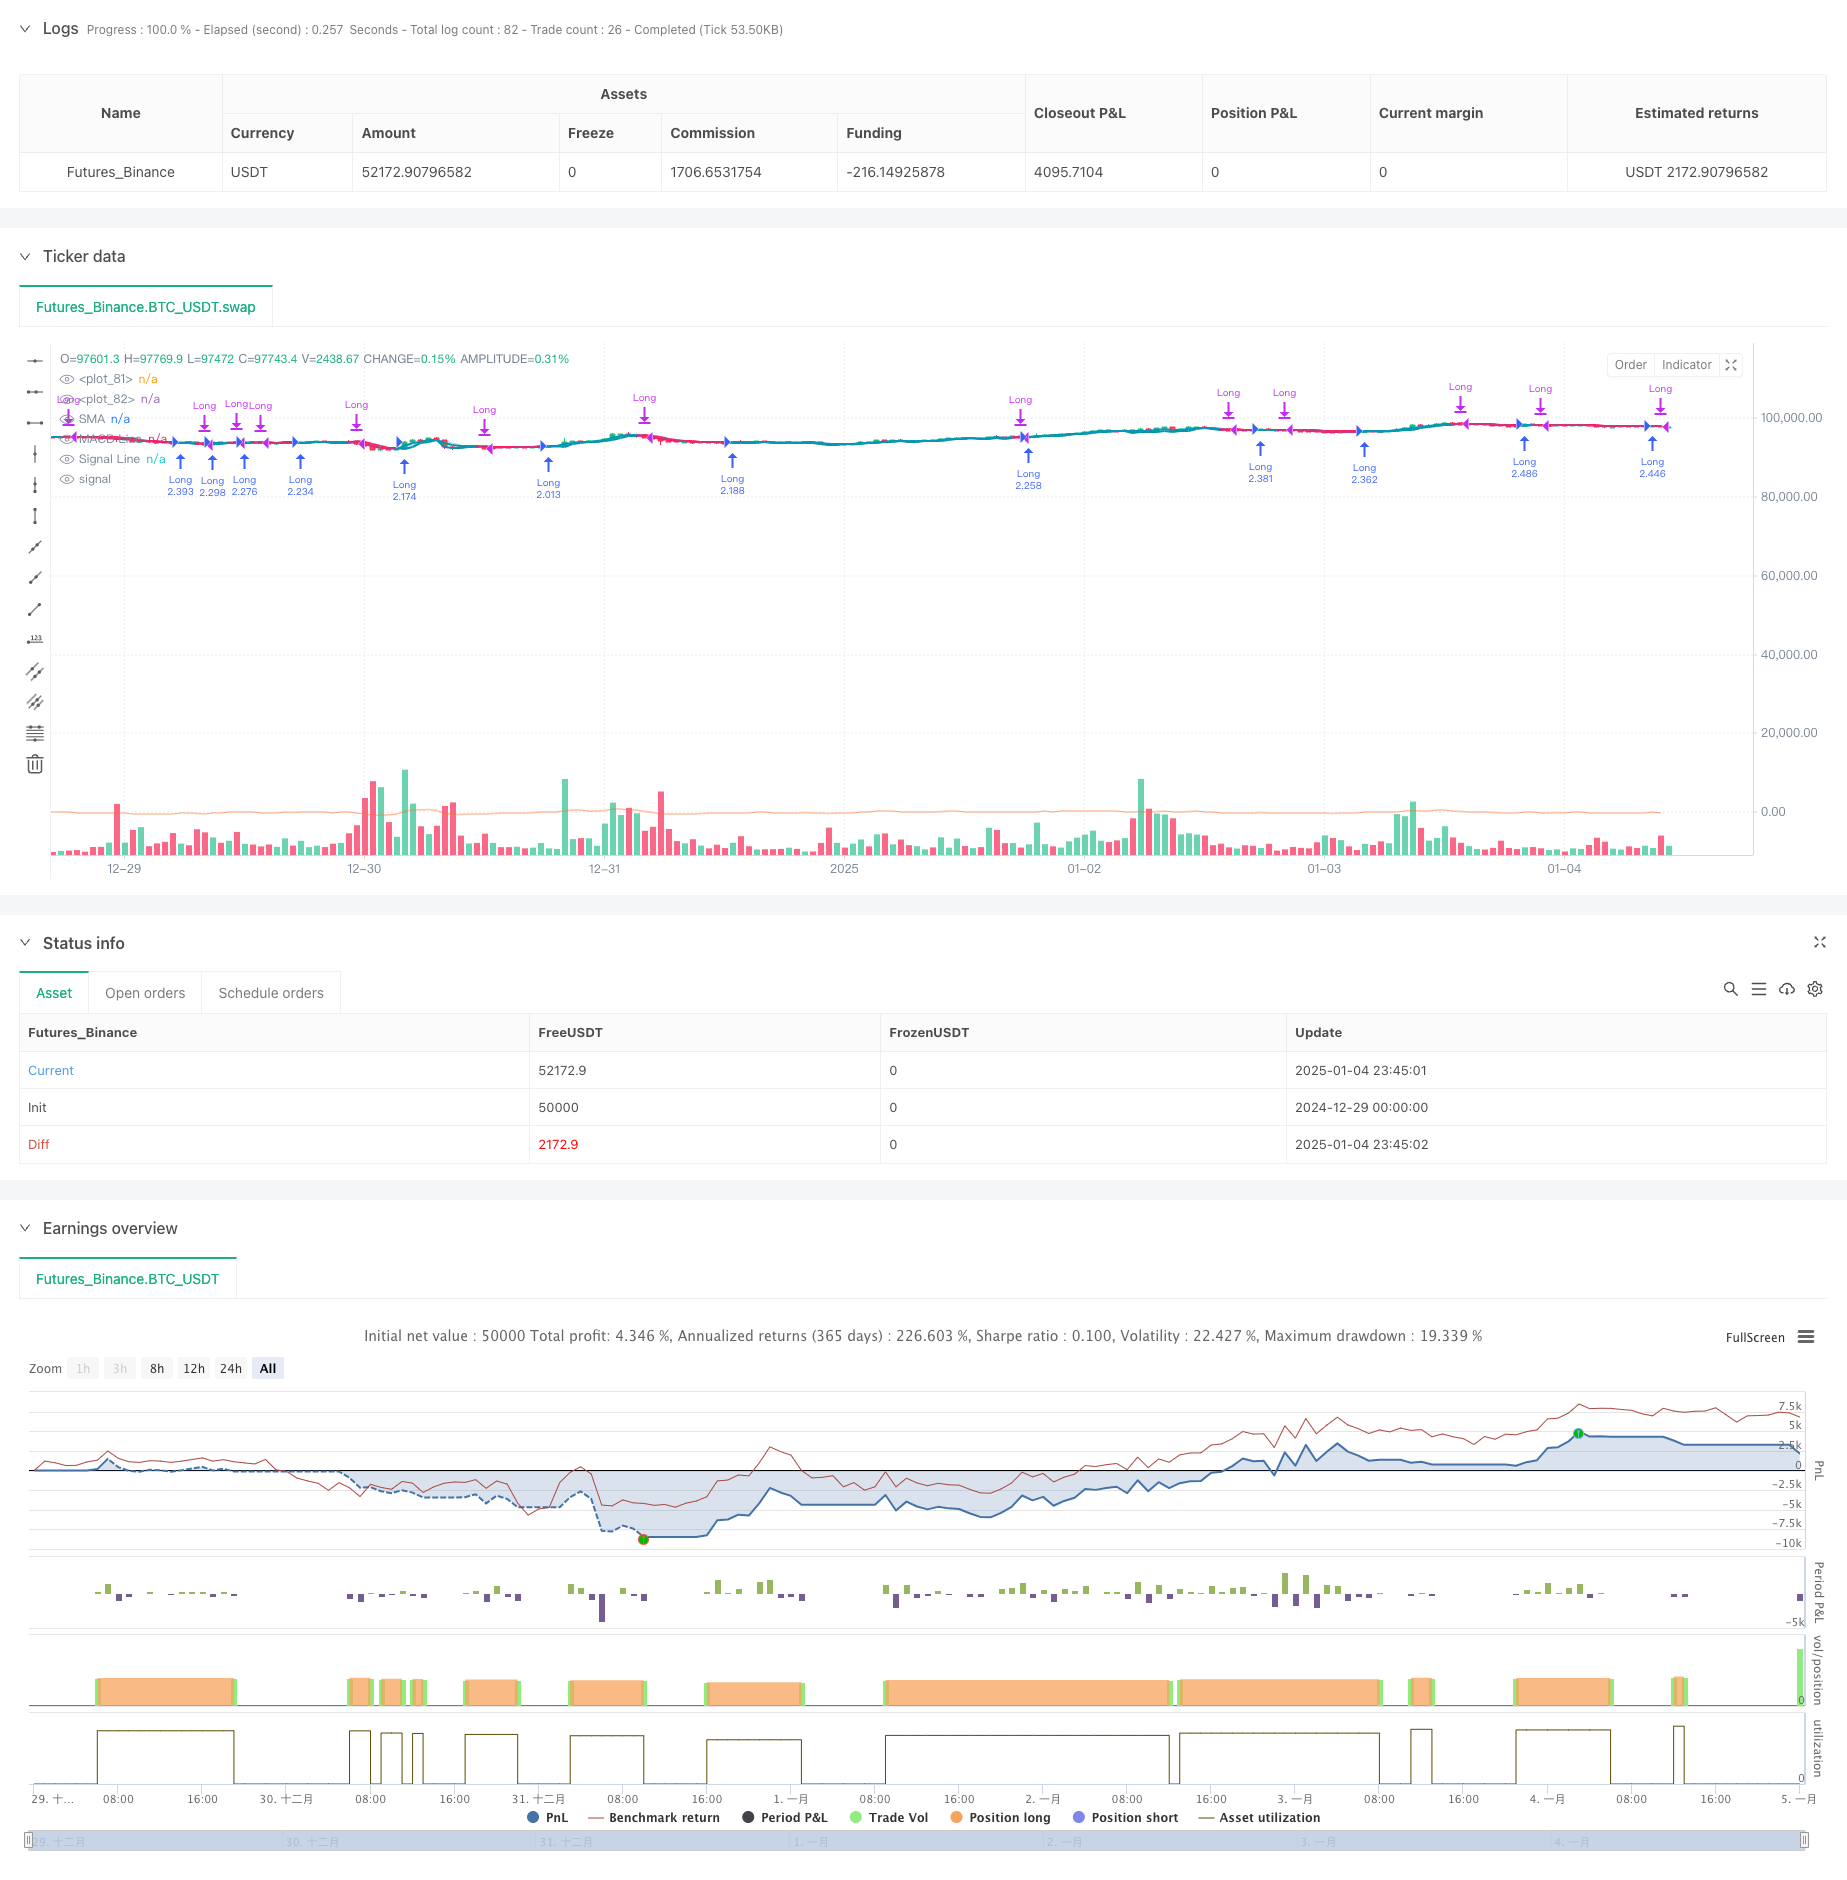
Overview
This strategy is an adaptive trend following system based on multiple technical indicator filters. It combines various technical indicators including Exponential Moving Average (EMA), Simple Moving Average (SMA), and Moving Average Convergence Divergence (MACD), dynamically adjusting parameters to adapt to different market environments for efficient trend capture and risk control. The strategy employs a layered filtering mechanism, significantly improving the reliability of trading signals through the synergistic combination of multiple technical indicators.
Strategy Principle
The core logic is based on a three-layer filtering mechanism:
- Adaptive Trend Recognition Layer: Uses a combination of fast and slow EMAs to calculate the trend baseline and dynamically adjusts upper and lower channel lines based on market volatility.
- SMA Filter Layer: Ensures price movement direction aligns with the overall trend using Simple Moving Average.
- MACD Confirmation Layer: Further validates trading signals using MACD indicator's trend confirmation functionality.
Trade signal generation requires all filter conditions to be met: trend transition, SMA direction confirmation, and MACD signal line support. The strategy also includes a dynamic position management system based on account equity, automatically adjusting position size through a leverage factor.
Strategy Advantages
- Strong Adaptability: Strategy can adapt to different market environments through dynamic parameter adjustment.
- Comprehensive Risk Control: Multiple filtering mechanisms significantly reduce the probability of false signals.
- High Customizability: Users can adjust various parameters according to personal trading style.
- High Automation Level: Supports JSON format alert messages for easy integration with automated trading systems.
- Good Visualization: Provides rich visual feedback including trend bands and signal markers.
Strategy Risks
- Trend Dependency: May generate frequent false signals in oscillating markets.
- Lag Risk: Multiple filtering mechanisms may lead to delayed entry timing.
- Parameter Sensitivity: Different parameter combinations may result in significant strategy performance variations.
- Leverage Risk: Excessive leverage may amplify losses.
Strategy Optimization Directions
- Volatility Adaptation: Add dynamic stop-loss mechanism based on ATR.
- Market Environment Recognition: Add market state classification system to use different parameter combinations in different market environments.
- Signal Quality Scoring: Establish signal strength scoring system to dynamically adjust positions based on signal strength.
- Capital Management Optimization: Introduce more sophisticated money management algorithms for more precise position control.
Summary
The strategy achieves relatively reliable trend following through multi-layer filtering mechanisms and dynamic parameter adjustment. Although there are certain risks of lag and parameter dependency, stable performance can still be achieved in actual trading through reasonable parameter optimization and risk control measures. Traders are recommended to thoroughly backtest and adjust parameter settings according to individual risk tolerance before live trading.
Source Pine Script
/*backtest
start: 2024-12-29 00:00:00
end: 2025-01-05 00:00:00
period: 45m
basePeriod: 45m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("Adaptive Trend Flow Strategy with Filters for SPX", overlay=true, max_labels_count=500,
     initial_capital=1000, commission_type=strategy.commission.cash_per_order, commission_value=0.01, slippage=2,
     margin_long=20, margin_short=20, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// User-defined inputs for trend logic
atr           = input.int(14, "Main Length", minval=2, group = "Find more strategies like this on pineindicators.com")
length        = input.int(2, "Main Length", minval=2)
smooth_len    = input.int(2, "Smoothing Length", minval=2)
sensitivity   = input.float(2.0, "Sensitivity", step=0.1)

// User-defined inputs for SMA filter
use_sma_filter = input.bool(true, "Enable SMA Filter?")
sma_length = input.int(4, "SMA Length", minval=1)

// User-defined inputs for MACD filter
use_macd_filter = input.bool(true, "Enable MACD Filter?")
macd_fast_length = input.int(2, "MACD Fast Length", minval=1)
macd_slow_length = input.int(7, "MACD Slow Length", minval=1)
macd_signal_length = input.int(2, "MACD Signal Length", minval=1)
// User-defined inputs for leverage
leverage_factor = input.float(4.5, "Leverage Factor", minval=1.0, step=0.1)
id           = input("besttrader123", title= "Your TradingView username", group = "Automate this strategy with plugpine.com")
key           = input("nc739ja84gf", title= "Unique identifier (UID)")
ticker        = input("SPX", title= "Ticker/symbol of your broker")
bullcolor     = #0097a7
bearcolor     = #ff195f
showbars      = input.bool(true, "Color Bars?")
showbg        = input.bool(true, "Background Color?")
showsignals   = input.bool(true, "Show Signals?")


// Trend calculation functions
calculate_trend_levels() =>
    typical = hlc3
    fast_ema = ta.ema(typical, length)
    slow_ema = ta.ema(typical, length * 2)
    basis = (fast_ema + slow_ema) / 2
    vol = ta.stdev(typical, length)
    smooth_vol = ta.ema(vol, smooth_len)
    upper = basis + (smooth_vol * sensitivity)
    lower = basis - (smooth_vol * sensitivity)
    [basis, upper, lower]

get_trend_state(upper, lower, basis) =>
    var float prev_level = na
    var int trend = 0
    if na(prev_level)
        trend := close > basis ? 1 : -1
        prev_level := trend == 1 ? lower : upper
    if trend == 1
        if close < lower
            trend := -1
            prev_level := upper
        else
            prev_level := lower
    else
        if close > upper
            trend := 1
            prev_level := lower
        else
            prev_level := upper
    [trend, prev_level]

[basis, upper, lower] = calculate_trend_levels()
[trend, level] = get_trend_state(upper, lower, basis)

// SMA filter
sma_value = ta.sma(close, sma_length)
sma_condition = use_sma_filter ? close > sma_value : true

// MACD filter
[macd_line, signal_line, _] = ta.macd(close, macd_fast_length, macd_slow_length, macd_signal_length)
macd_condition = use_macd_filter ? macd_line > signal_line : true

// Signal detection with filters
long_signal = trend == 1 and trend[1] == -1 and sma_condition and macd_condition
short_signal = trend == -1 and trend[1] == 1

// Plotting visuals
p2 = plot(basis, color=trend == 1 ? bullcolor : bearcolor, linewidth=2)
p1 = plot(level, color=close > level ? bullcolor : bearcolor, linewidth=2, style=plot.style_linebr)
// if showsignals and ta.crossover(close, level)
//     label.new(bar_index, level, "▲", color=bullcolor, textcolor=chart.bg_color, style=label.style_label_upper_right)
// if showsignals and ta.crossunder(close, level)
//     label.new(bar_index, level, "▼", color=bearcolor, textcolor=chart.fg_color, style=label.style_label_lower_right)

qty = strategy.equity / close * leverage_factor

// Automated alerts
if long_signal
    alert('{"AccountID": "' + id + '","Key": "' + key + '", "symbol": "' + ticker + '", "action": "long", "volume": ' + str.tostring(qty) + '}', alert.freq_once_per_bar)
if short_signal
    alert('{"AccountID": "' + id + '","Key": "' + key + '", "symbol": "' + ticker + '", "action": "closelong"}', alert.freq_once_per_bar)

// Strategy entries and exits
if long_signal
    strategy.entry("Long", strategy.long, qty=qty)
if short_signal
    strategy.close("Long")

// Optional SMA and MACD plot
plot(use_sma_filter ? sma_value : na, color=color.new(color.blue, 80), title="SMA")
plot(use_macd_filter ? macd_line : na, color=color.new(color.orange, 80), title="MACD Line")
plot(use_macd_filter ? signal_line : na, color=color.new(color.red, 80), title="Signal Line")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Trend-Flow-Multiple-Filter-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h