Strategy vault / Trend following
Dual EMA RSI Divergence Strategy A Trend Capture System Based on Exponential Moving Average and Relative Strength
This is a trend following strategy that combines Exponential Moving Average (EMA) and Relative Strength Index (RSI). The strategy identifies trading signals by monitoring the crossover of fast and slow EMAs while…
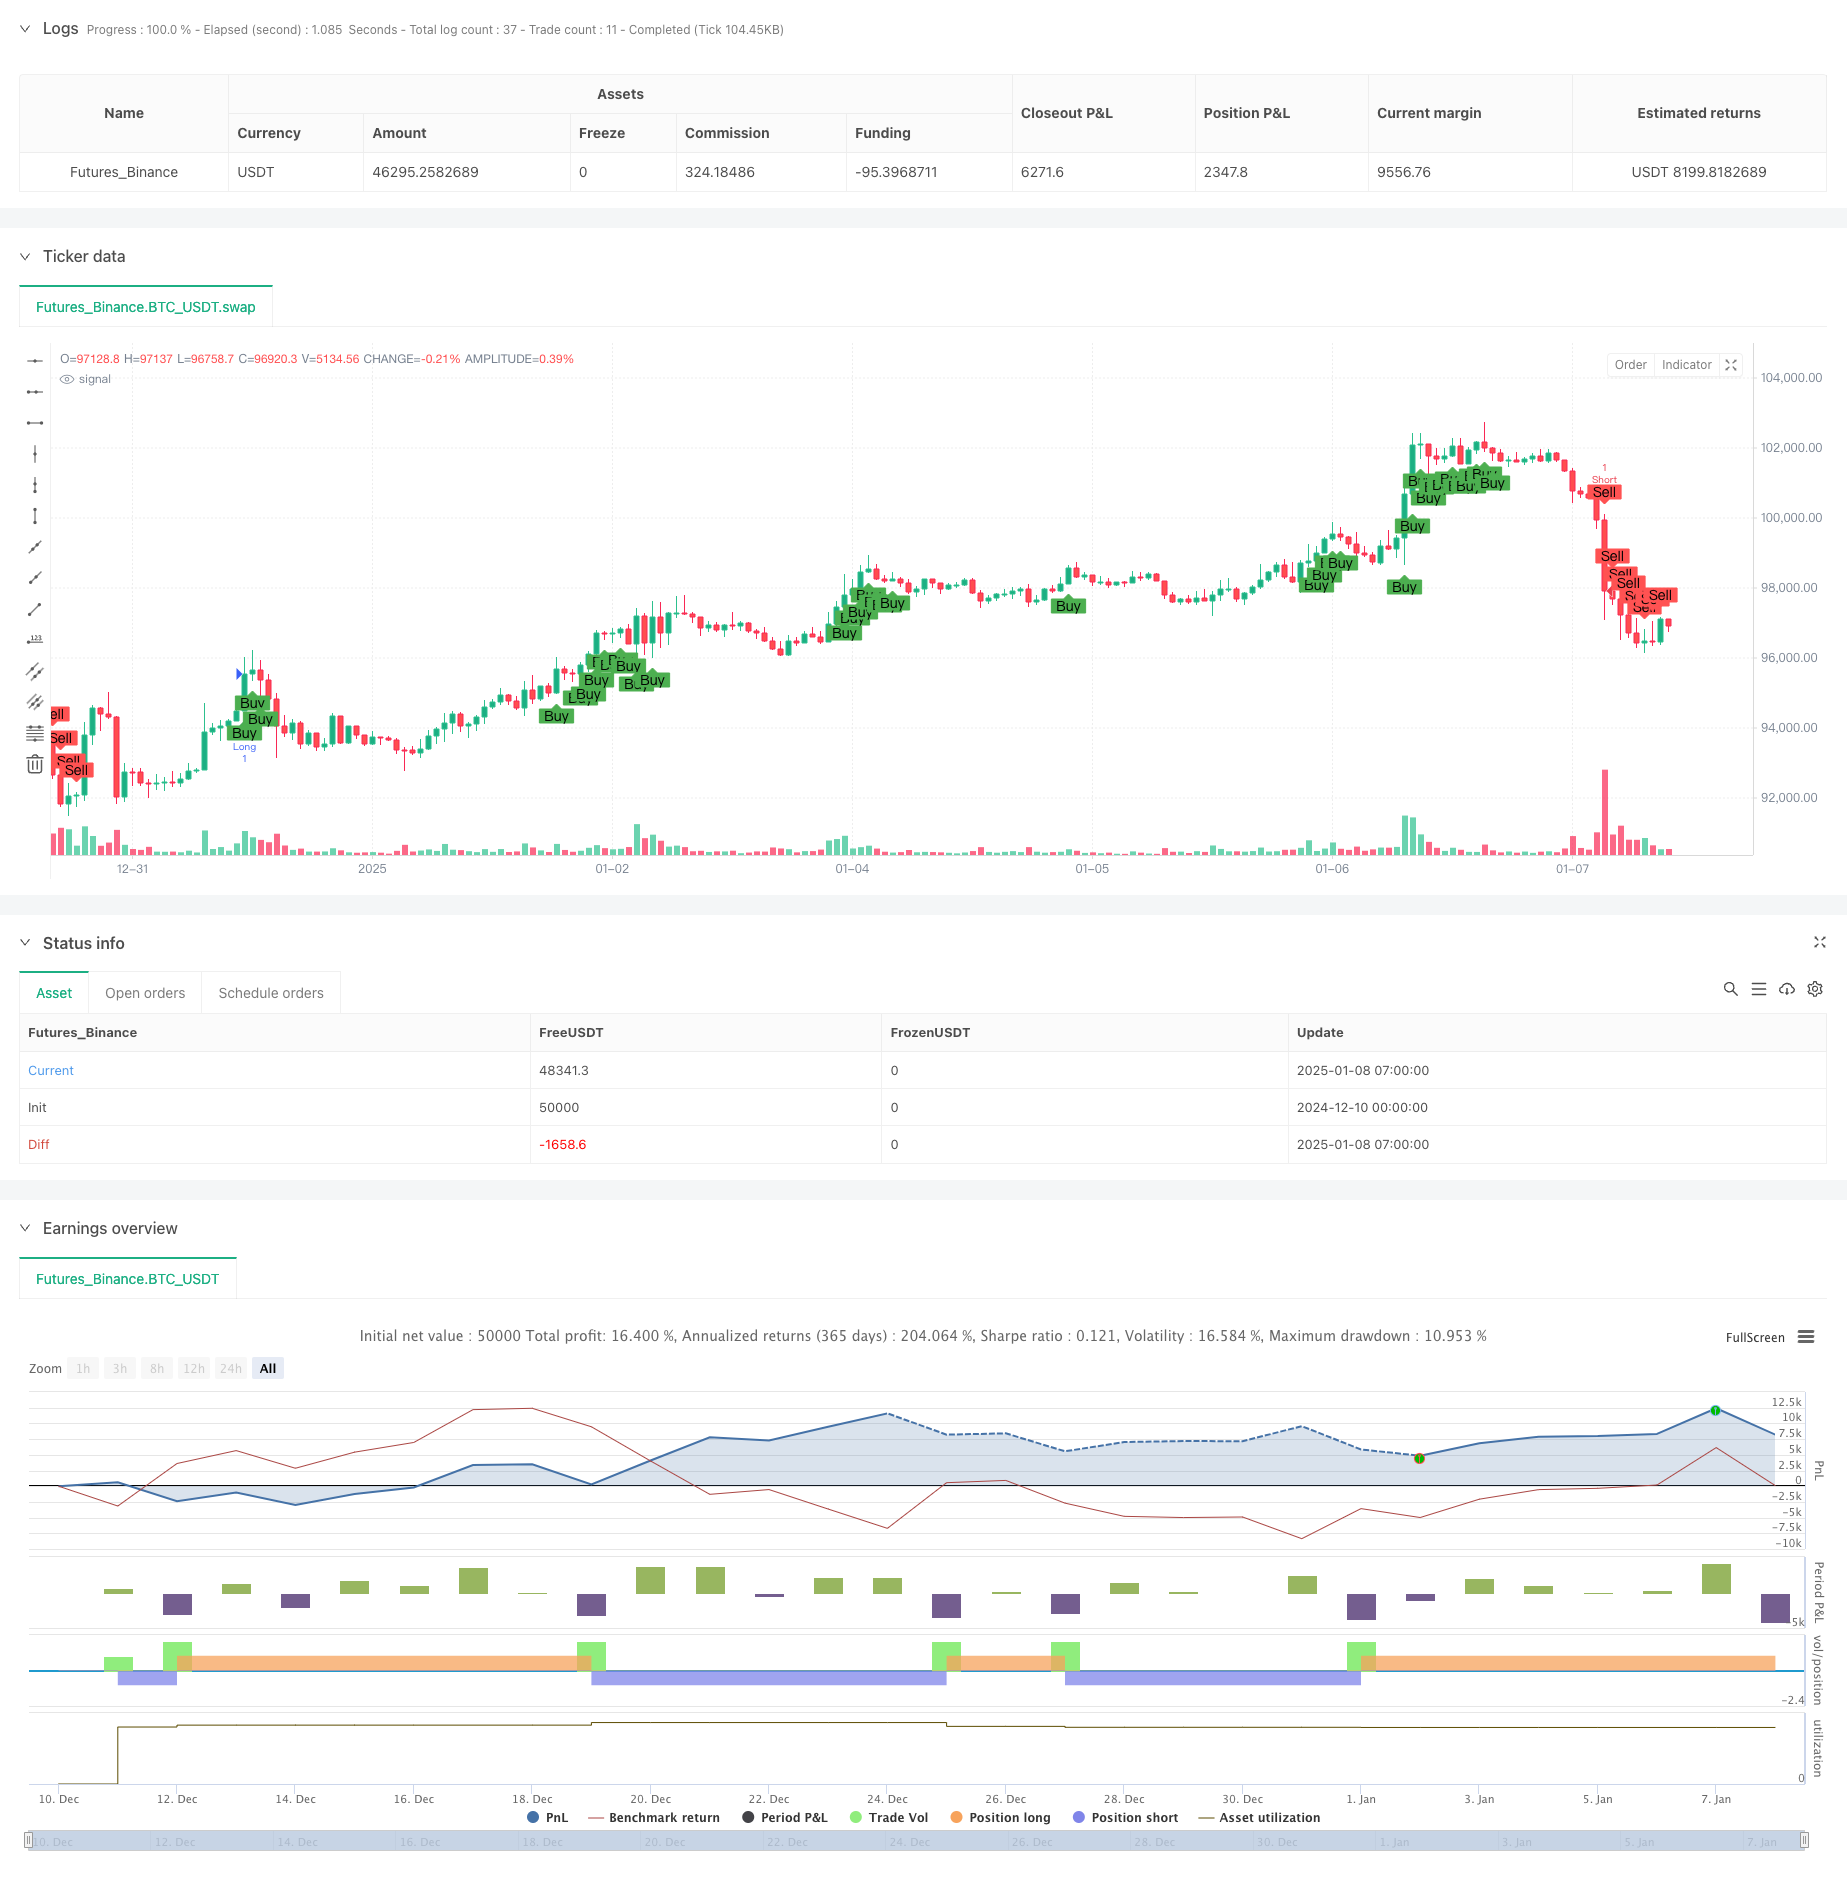
Overview
This is a trend following strategy that combines Exponential Moving Average (EMA) and Relative Strength Index (RSI). The strategy identifies trading signals by monitoring the crossover of fast and slow EMAs while incorporating RSI overbought/oversold levels and RSI divergence to effectively capture market trends. Operating on a 1-hour timeframe, it enhances trading accuracy through multiple technical indicator verification.
Strategy Principles
The core logic includes the following key elements:
- Uses 9-period and 26-period EMAs to determine trend direction, with uptrend indicated when fast line is above slow line
- Employs 14-period RSI with 65 and 35 as thresholds for long and short signals
- Detects RSI divergence on 1-hour timeframe by comparing price highs/lows with RSI highs/lows
- Long entry requires: fast EMA above slow EMA, RSI above 65, and no bearish RSI divergence
- Short entry requires: fast EMA below slow EMA, RSI below 35, and no bullish RSI divergence
Strategy Advantages
- Cross-validation of multiple technical indicators improves signal reliability
- RSI divergence detection reduces false breakout risks
- Combines benefits of trend following and overbought/oversold conditions
- Parameters can be optimized for different market characteristics
- Clear strategy logic that's easy to understand and implement
Strategy Risks
- EMA as a lagging indicator may lead to suboptimal entry points
- RSI may generate excessive signals in ranging markets
- Divergence detection may produce false readings, especially in volatile markets
- Significant drawdowns possible during quick market reversals Mitigation measures:
- Add stop-loss and take-profit settings
- Consider adding volume indicator verification
- Adjust RSI thresholds in ranging markets
Optimization Directions
- Introduce adaptive RSI thresholds based on market volatility
- Incorporate volume indicators for signal confirmation
- Develop more precise divergence detection algorithms
- Add stop-loss and profit management mechanisms
- Consider adding market volatility filters
Summary
This strategy builds a relatively complete trading system by combining moving averages, momentum indicators, and divergence analysis. It emphasizes multiple signal verification to effectively reduce false judgment risks. While there is some inherent lag, the strategy holds practical value through parameter optimization and risk management improvements.
Source Pine Script
/*backtest
start: 2024-12-10 00:00:00
end: 2025-01-08 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA9_RSI_Strategy_LongShort", overlay=true)

// Parameters
fastLength = input.int(9, minval=1, title="Fast EMA Length")
slowLength = input.int(26, minval=1, title="Slow EMA Length")
rsiPeriod = input.int(14, minval=1, title="RSI Period")
rsiLevelLong = input.int(65, minval=1, title="RSI Level (Long)")
rsiLevelShort = input.int(35, minval=1, title="RSI Level (Short)")

// Define 1-hour timeframe
timeframe_1h = "60"

// Fetch 1-hour data
high_1h = request.security(syminfo.tickerid, timeframe_1h, high)
low_1h = request.security(syminfo.tickerid, timeframe_1h, low)
rsi_1h = request.security(syminfo.tickerid, timeframe_1h, ta.rsi(close, rsiPeriod))

// Current RSI
rsi = ta.rsi(close, rsiPeriod)

// Find highest/lowest price and corresponding RSI in the 1-hour timeframe
highestPrice_1h = ta.highest(high_1h, 1) // ราคาสูงสุดใน 1 ช่วงของ timeframe 1 ชั่วโมง
lowestPrice_1h = ta.lowest(low_1h, 1)   // ราคาต่ำสุดใน 1 ช่วงของ timeframe 1 ชั่วโมง
highestRsi_1h = ta.valuewhen(high_1h == highestPrice_1h, rsi_1h, 0)
lowestRsi_1h = ta.valuewhen(low_1h == lowestPrice_1h, rsi_1h, 0)

// Detect RSI Divergence for Long
bearishDivLong = high > highestPrice_1h and rsi < highestRsi_1h
bullishDivLong = low < lowestPrice_1h and rsi > lowestRsi_1h
divergenceLong = bearishDivLong or bullishDivLong

// Detect RSI Divergence for Short (switch to low price for divergence check)
bearishDivShort = low > lowestPrice_1h and rsi < lowestRsi_1h
bullishDivShort = high < highestPrice_1h and rsi > highestRsi_1h
divergenceShort = bearishDivShort or bullishDivShort

// Calculate EMA
emaFast = ta.ema(close, fastLength)
emaSlow = ta.ema(close, slowLength)

// Long Conditions
longCondition = emaFast > emaSlow and rsi > rsiLevelLong and not divergenceLong

// Short Conditions
shortCondition = emaFast < emaSlow and rsi < rsiLevelShort and not divergenceShort

// Plot conditions
plotshape(longCondition, title="Buy", location=location.belowbar, color=color.green, style=shape.labelup, text="Buy")
plotshape(shortCondition, title="Sell", location=location.abovebar, color=color.red, style=shape.labeldown, text="Sell")

// Execute the strategy
if (longCondition)
    strategy.entry("Long", strategy.long, comment="entry long")

if (shortCondition)
    strategy.entry("Short", strategy.short, comment="entry short")

// Alert
alertcondition(longCondition, title="Buy Signal", message="Buy signal triggered!")
alertcondition(shortCondition, title="Sell Signal", message="Sell signal triggered!")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-RSI-Divergence-Strategy-A-Trend-Capture-System-Based-on-Exponential-Moving-Average-and-Relative-Strength.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover with RSI Trend Confirmation StrategyPine Script · Trend following · 3h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d