Strategy vault / Trend following
Dynamic Dual Moving Average Trailing Stop Strategy
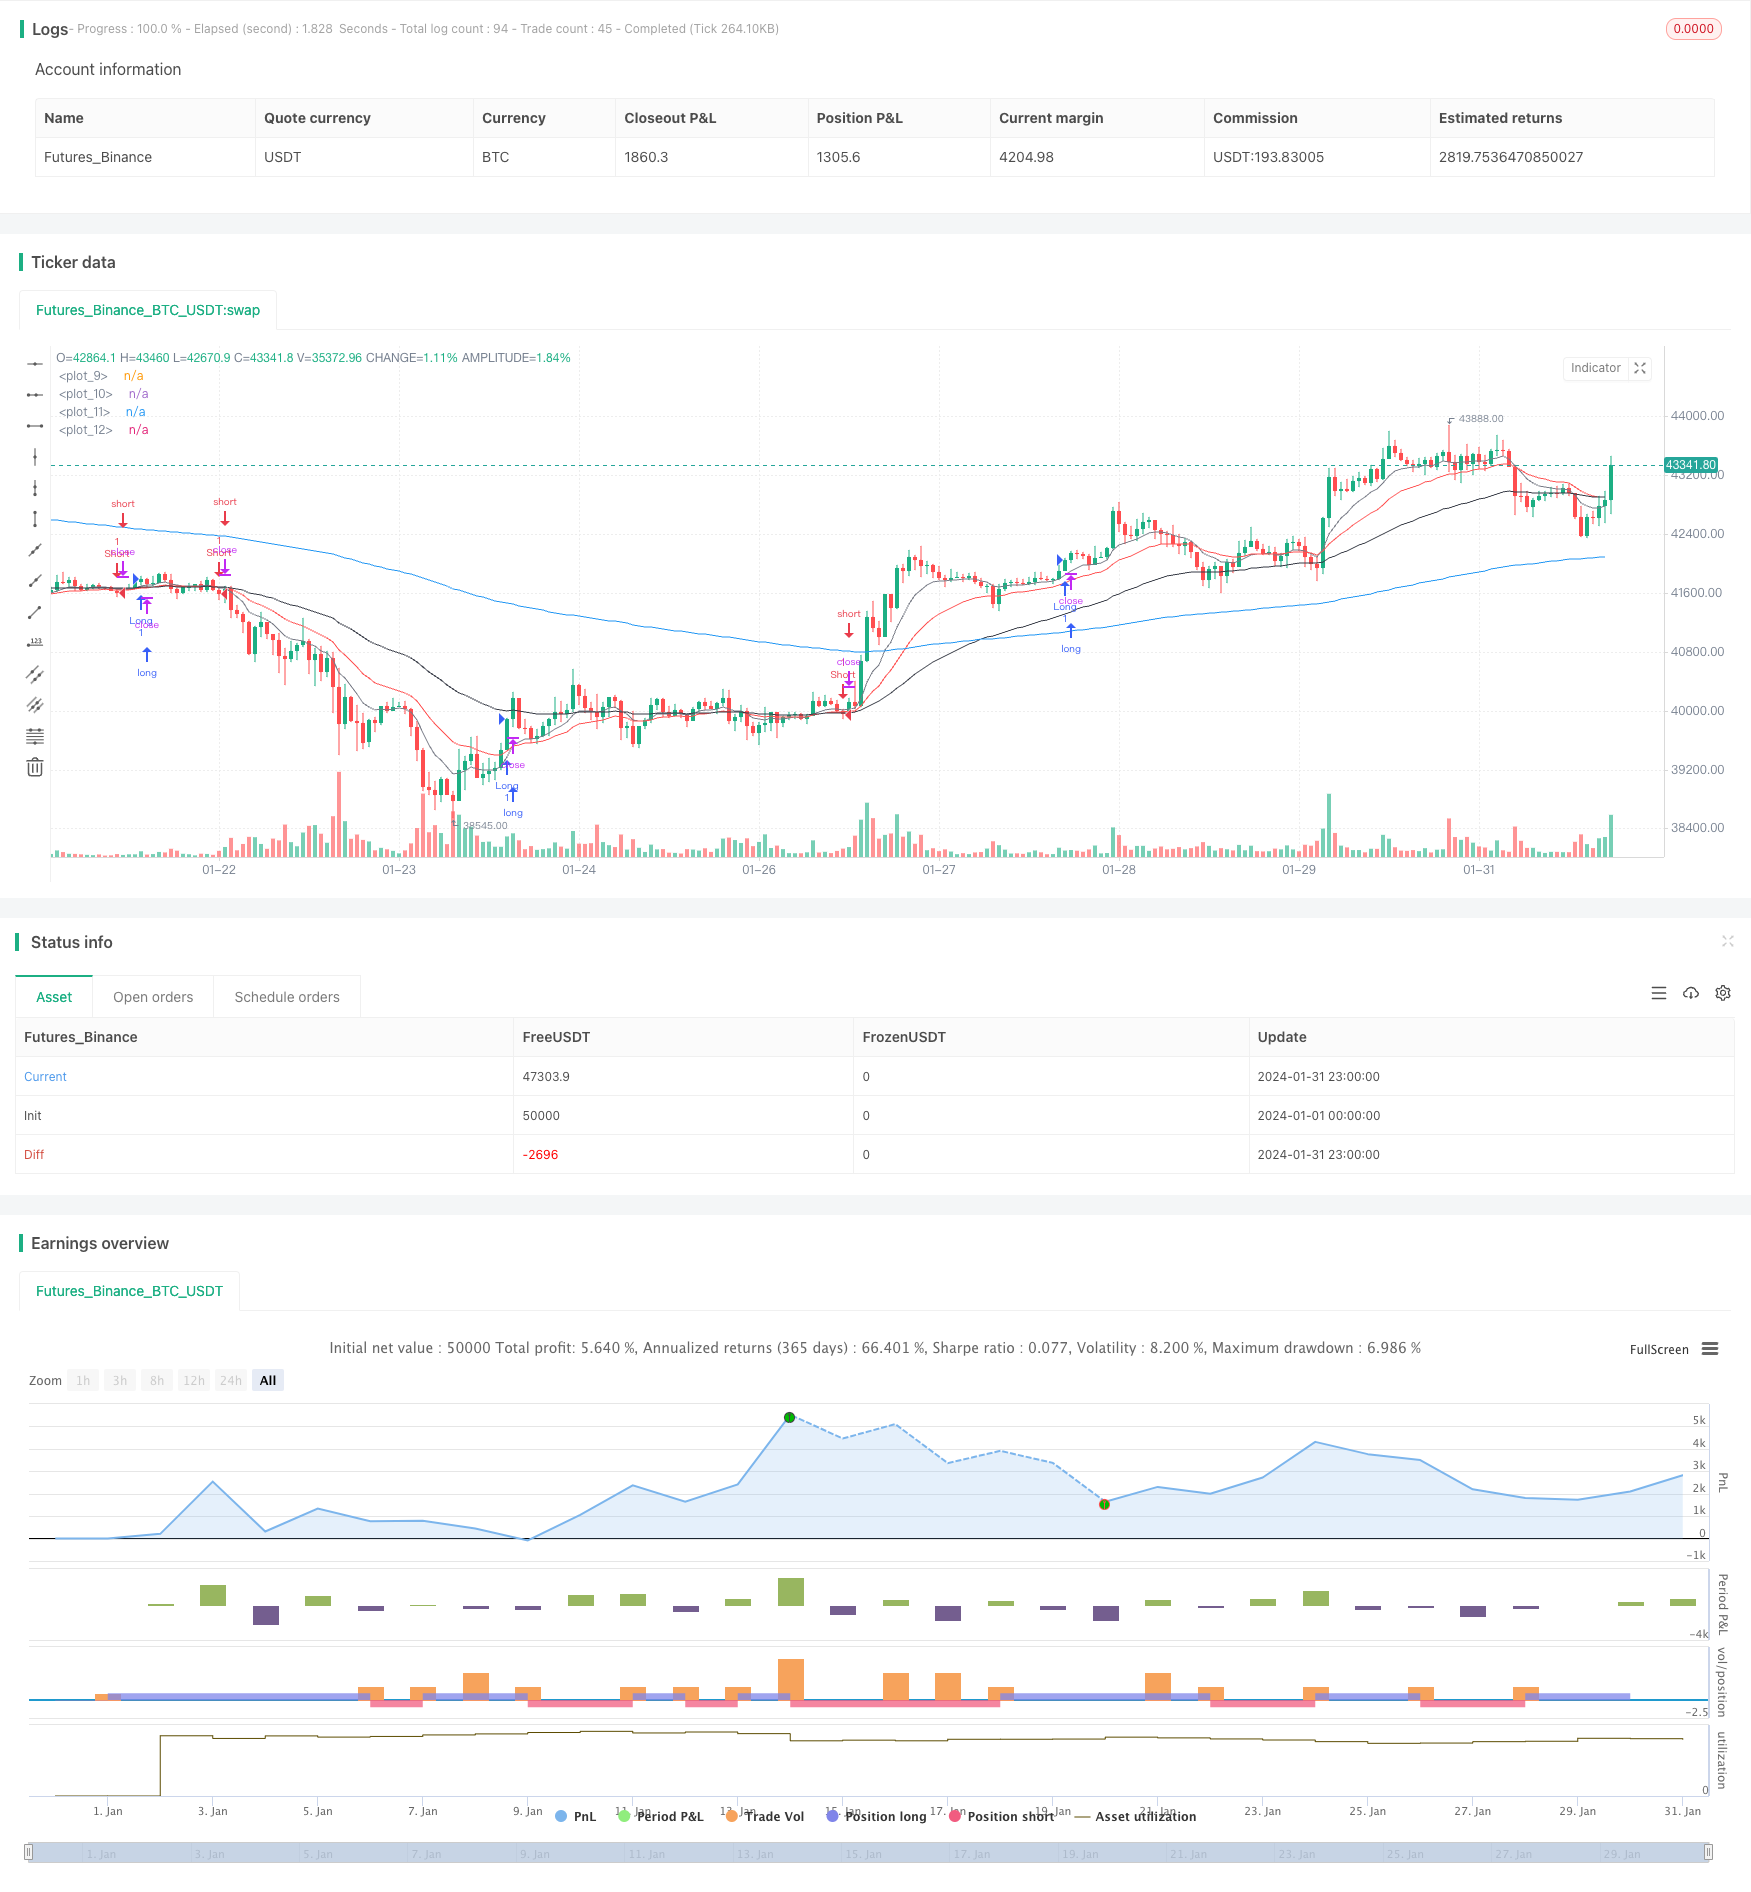
This is a dynamic trailing stop strategy based on dual EMA lines. It uses 9-day and 20-day EMAs to determine market trend direction, combined with RSI indicator to filter false breaks. It also uses ATR indicator to…
Overview
This is a dynamic trailing stop strategy based on dual EMA lines. It uses 9-day and 20-day EMAs to determine market trend direction, combined with RSI indicator to filter false breaks. It also uses ATR indicator to calculate dynamic stop loss and take profit levels. This strategy is suitable for medium to long term holdings.
Strategy Logic
The strategy uses 9-day EMA as the short term line and 20-day EMA as the medium term line to determine price trend. It goes long when price crosses above the short term line and closing price is higher than previous day's high, with RSI lower than 70 and close higher than 20-day EMA minus 1 ATR. It goes short when price crosses below the short term line and closing price is lower than previous day's low, with RSI higher than 30 and close higher than 20-day EMA minus 1 ATR.
The stop loss is set at closing price minus 1.5 times ATR. Take profit is set at closing price plus ATR multiplied by a take profit coefficient. It also uses 2 times ATR to set trend trailing stop loss.
Advantage Analysis
- Using dual EMAs to determine major market trend, avoids being pressured by noise
- Combining RSI indicator to filter false breaks, improves entry accuracy
- Dynamic stop loss and take profit adapts to market volatility
- Trend trailing stop loss maximizes profits
Risk Analysis
- EMA lines have lagging effect, may miss short term opportunities
- Improper RSI parameter setting may miss entries
- Improper stop loss/take profit ratio may be too loose or strict
- Stop loss may be penetrated during violent market swings
Optimization Directions
- Test different EMA combinations to find optimal parameters
- Optimize RSI parameters to balance entry accuracy and catching opportunities
- Test different stop loss/take profit ratios to find optimal configuration
- Add more filter conditions to reduce stop loss penetration probability
Summary
Overall this is a relatively stable medium to long term holding strategy. It uses dual EMAs to determine major market trend, avoiding being affected by short term noise. The addition of RSI also filters false breaks to some extent. Moreover, the dynamic stop loss/take profit mechanism allows the strategy to adjust based on market volatility. However, there are still risks like lagging of moving averages and potential of stop loss penetration. We need to find the optimum configuration through parameter tuning and optimization during practical application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2 | Take Profit Multiplier |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("CJTrade", overlay=true)

short = ema(close, 9)
medium = ema(close, 20)
long = ema(close, 50)
very_long = ema(close, 200)

plot(short, color=color.gray, linewidth=1)
plot(medium, color=color.red, linewidth=1)
plot(long, color=color.black, linewidth=1)
plot(very_long, color=color.blue, linewidth=1)

rsiValue = rsi(close, 14)

near20EMA = close > medium - atr(14)

longCond = crossover(close[1], short) and close >= high[1] and rsiValue < 70 and near20EMA
shortCond = crossunder(close[1], short) and close <= low[1] and rsiValue > 30 and near20EMA

strategy.entry("Long", strategy.long, when=longCond)
strategy.entry("Short", strategy.short, when=shortCond)

atrValue = atr(14)
stopLossLevel = close - atrValue * 1.5

// Dynamic take profit level based on ATR
takeProfitMultiplier = input(2, title="Take Profit Multiplier", minval=0.1, maxval=10, step=0.1)
takeProfitLevel = close + atrValue * takeProfitMultiplier

// Trailing stop loss for long positions
longTrailingStop = close - atrValue * 2
strategy.exit("LongTrailingStop", from_entry="Long", loss=longTrailingStop)

// Trailing stop loss for short positions
shortTrailingStop = close + atrValue * 2
strategy.exit("ShortTrailingStop", from_entry="Short", loss=shortTrailingStop)

strategy.exit("Take Profit/Stop Loss", from_entry="Long", loss=stopLossLevel, profit=takeProfitLevel)
strategy.exit("Take Profit/Stop Loss", from_entry="Short", loss=stopLossLevel, profit=takeProfitLevel)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Dual-Moving-Average-Trailing-Stop-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- Dynamic Multi Timeframe ATR Crossover Strategy Optimizing Trend Following and Risk Management with Flexible ParametersPine Script · Trend following · 1h