Strategy vault / Trend following
Dynamic Moving Average Trend Following with RSI Confirmation Trading Strategy
This is a trend-following strategy based on Exponential Moving Average (EMA) crossovers and Relative Strength Index (RSI) confirmation. The strategy combines signals from short-term and long-term EMA crossovers with…
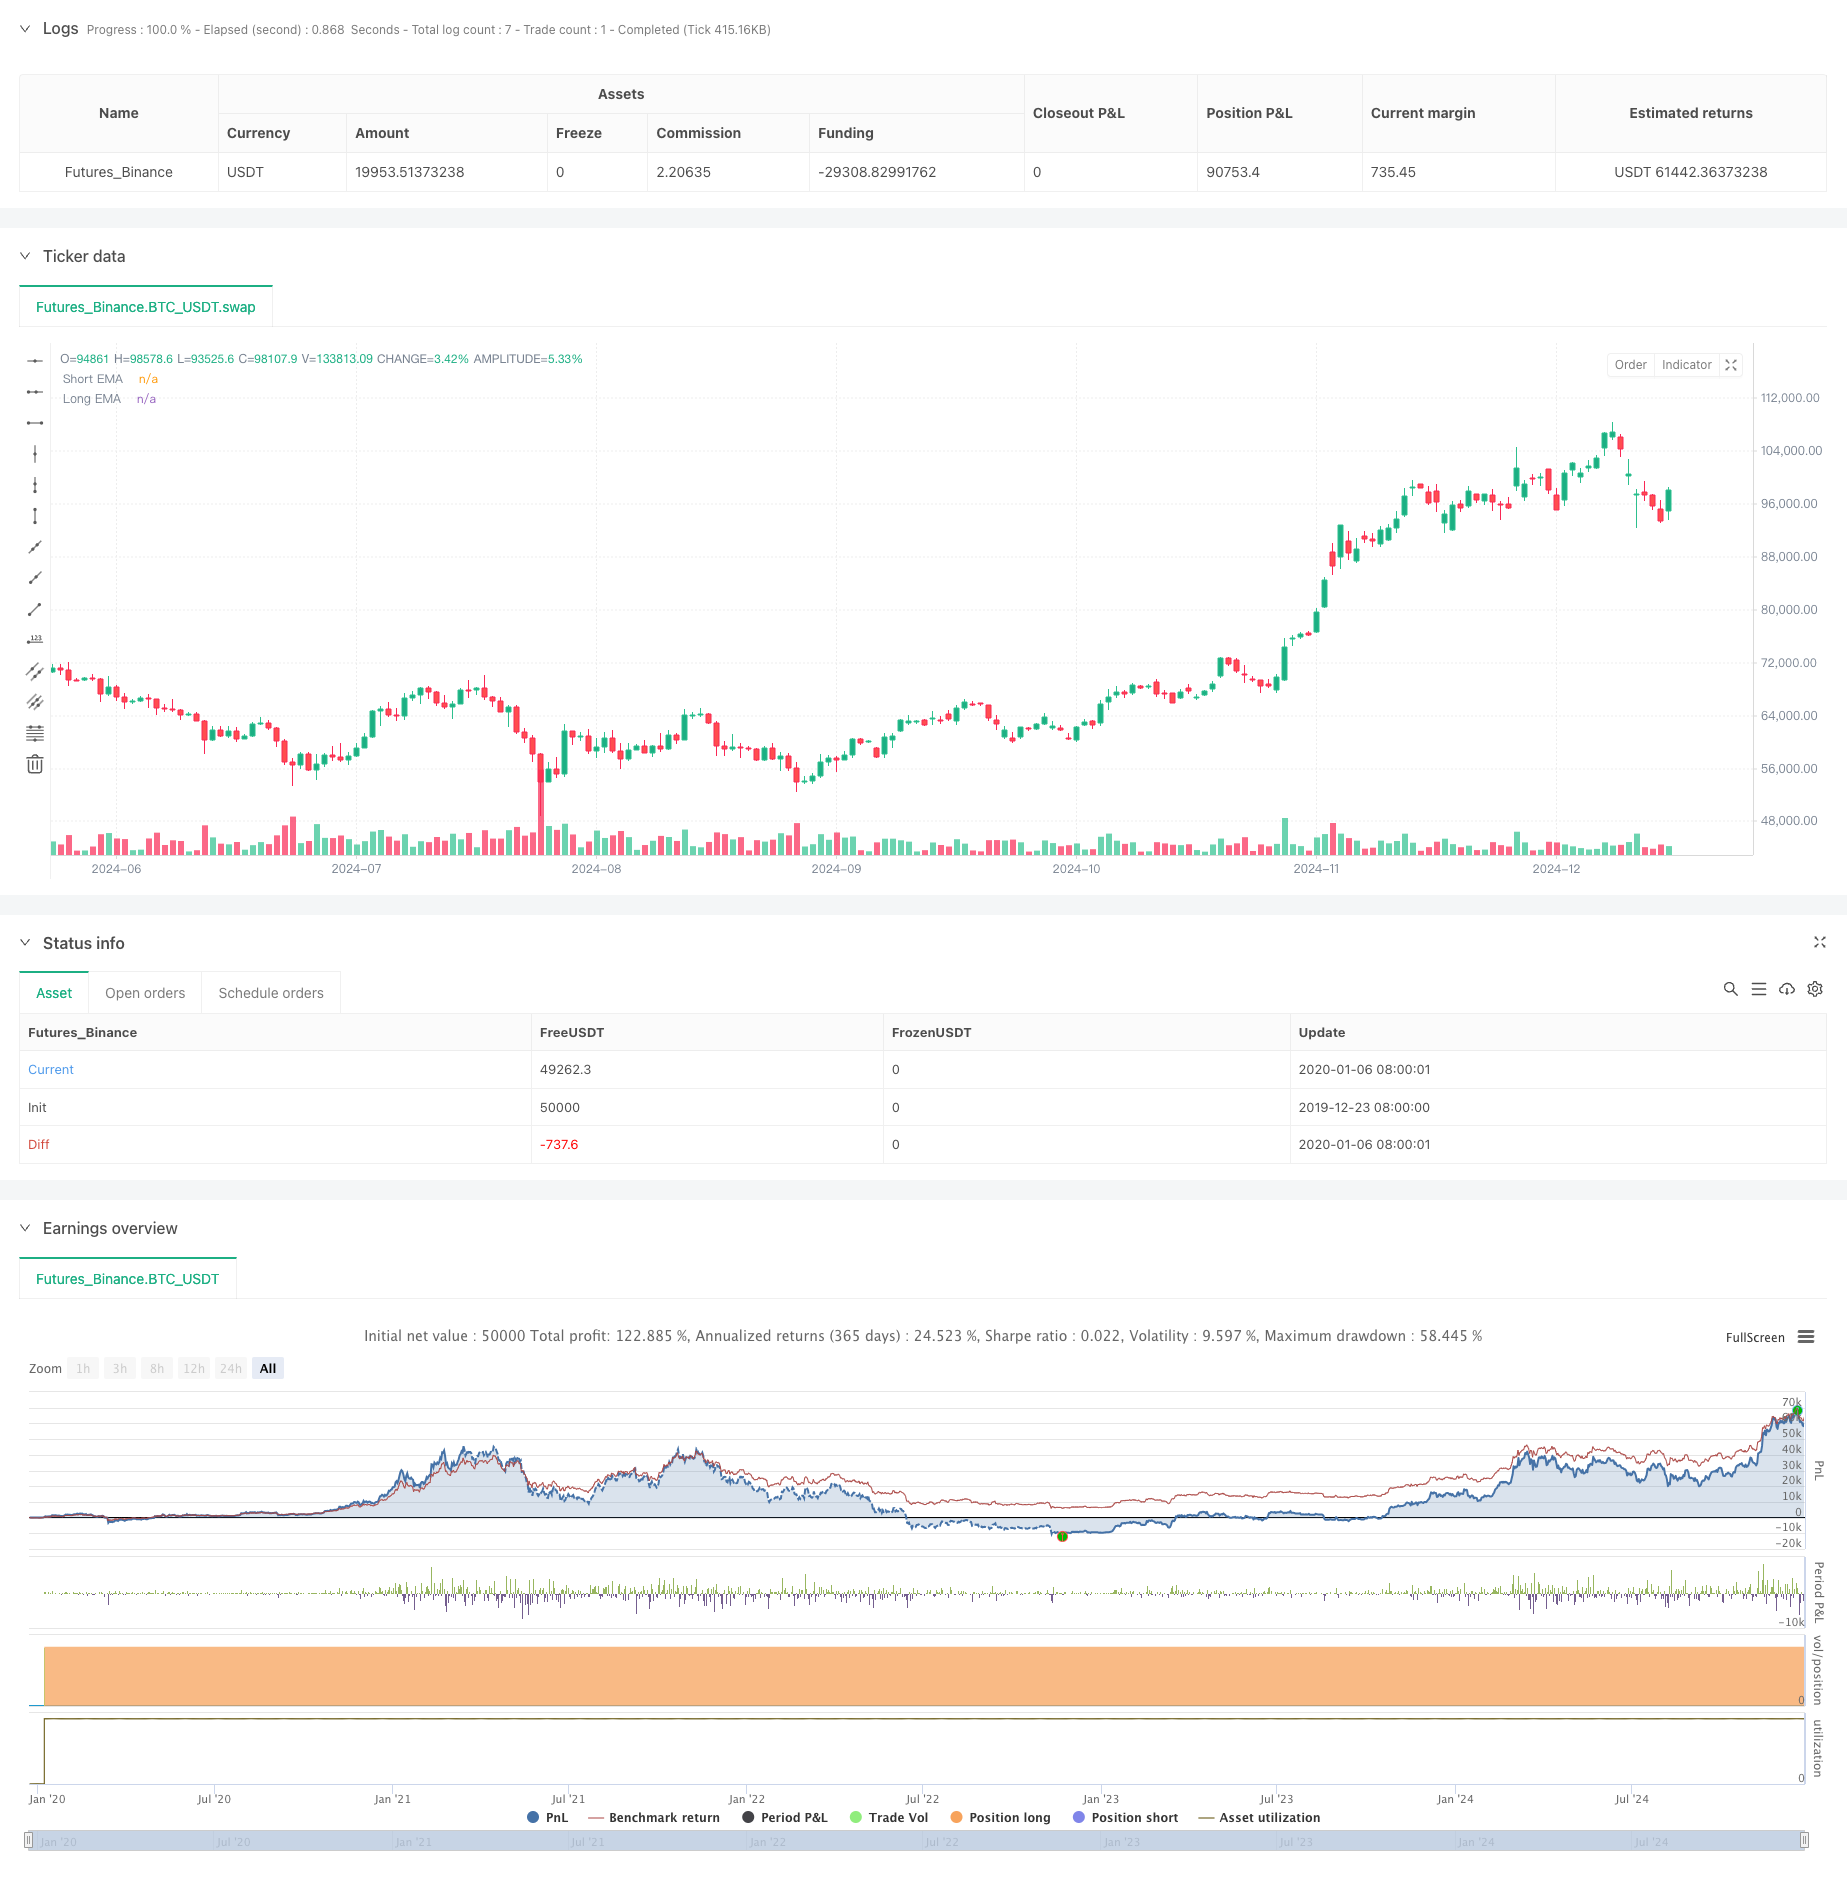
Overview
This is a trend-following strategy based on Exponential Moving Average (EMA) crossovers and Relative Strength Index (RSI) confirmation. The strategy combines signals from short-term and long-term EMA crossovers with RSI momentum confirmation, while incorporating a percentage-based stop-loss mechanism. It aims to capture significant market trend reversals while maintaining risk control through the synergistic effect of technical indicators.
Strategy Principles
The strategy employs a dual technical indicator filtering mechanism: First, it identifies potential trend reversal points through the crossover of short-term EMA (9 periods) and long-term EMA (21 periods). Buy signals are generated when the short-term EMA crosses above the long-term EMA and the RSI value is above the specified level. Sell signals occur when the short-term EMA crosses below the long-term EMA and the RSI value is below the specified level. Additionally, the strategy incorporates a percentage-based stop-loss mechanism, setting dynamic stop-loss levels for each trade to effectively control downside risk.
Strategy Advantages
- Dual technical indicator confirmation mechanism significantly improves trade signal reliability and reduces false signals
- Dynamic stop-loss mechanism effectively controls risk exposure for each trade
- Strong parameter adjustability allows traders to adapt to different market environments
- Clear strategy logic that is easy to understand and execute
- Visualized signal display and stop-loss lines make trading decisions more intuitive
Strategy Risks
- May generate frequent trading signals in ranging markets, increasing transaction costs
- EMAs as lagging indicators may not respond quickly enough in highly volatile markets
- RSI confirmation mechanism might miss important trend beginnings under certain market conditions
- Fixed percentage stop-loss may be too strict or loose in markets with varying volatility
Strategy Optimization Directions
- Introduce volatility indicators to dynamically adjust stop-loss percentages for more adaptive risk control
- Add trend strength filters to avoid frequent trading in weak trend markets
- Integrate volume indicators as additional confirmation mechanisms to improve signal quality
- Add trailing stop-loss mechanism to better protect accumulated profits
- Consider incorporating market environment classification to use different parameters in different market states
Summary
This strategy constructs a complete trend-following trading system through the combination of moving averages and momentum indicators. Its main advantages lie in its reliable signal confirmation mechanism and comprehensive risk control system. While there are some inherent limitations, the strategy's overall performance can be further enhanced through the proposed optimization directions. This is a robust strategy framework suitable for medium to long-term trend traders.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-25 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Simple Trend Following Strategy", overlay=true)

// Inputs
shortEMA = input.int(9, title="Short EMA Length", minval=1)
longEMA = input.int(21, title="Long EMA Length", minval=1)
confirmationRSI = input.int(50, title="RSI Confirmation Level", minval=1, maxval=100)
stopLossPercent = input.float(2, title="Stop Loss Percentage", minval=0.1)  // Stop Loss percentage

// Calculations
emaShort = ta.ema(close, shortEMA)
emaLong = ta.ema(close, longEMA)

rsiValue = ta.rsi(close, 14)

// Buy and Sell Conditions
buySignal = ta.crossover(emaShort, emaLong) and rsiValue > confirmationRSI
sellSignal = ta.crossunder(emaShort, emaLong) and rsiValue < confirmationRSI

// Plotting Signals
plotshape(buySignal, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
plotshape(sellSignal, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")

// Plotting EMAs
plot(emaShort, title="Short EMA", color=color.yellow)
plot(emaLong, title="Long EMA", color=color.purple)

// Strategy logic
strategy.entry("Buy", strategy.long, when=buySignal)
strategy.entry("Sell", strategy.short, when=sellSignal)

// Calculate stop loss price based on stopLossPercent
longStopLossPrice = strategy.position_avg_price * (1 - stopLossPercent / 100)
shortStopLossPrice = strategy.position_avg_price * (1 + stopLossPercent / 100)

// Draw stop loss line for long positions
if (strategy.position_size > 0)  // For long positions
    line.new(x1=bar_index, y1=longStopLossPrice, x2=bar_index + 1, y2=longStopLossPrice, color=color.red, width=2, style=line.style_dashed)

// Draw stop loss line for short positions
if (strategy.position_size < 0)  // For short positions
    line.new(x1=bar_index, y1=shortStopLossPrice, x2=bar_index + 1, y2=shortStopLossPrice, color=color.green, width=2, style=line.style_dashed)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Moving-Average-Trend-Following-with-RSI-Confirmation-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover with RSI Trend Confirmation StrategyPine Script · Trend following · 3h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d