Strategy vault / Trend following
Exponential Moving Average and Relative Strength Index Combination Trend Following Strategy
This strategy combines the EMA and RSI indicators to identify trend direction and enter positions after trend confirmation, avoiding overbuying and overselling by incorporating the RSI indicator. The strategy is…
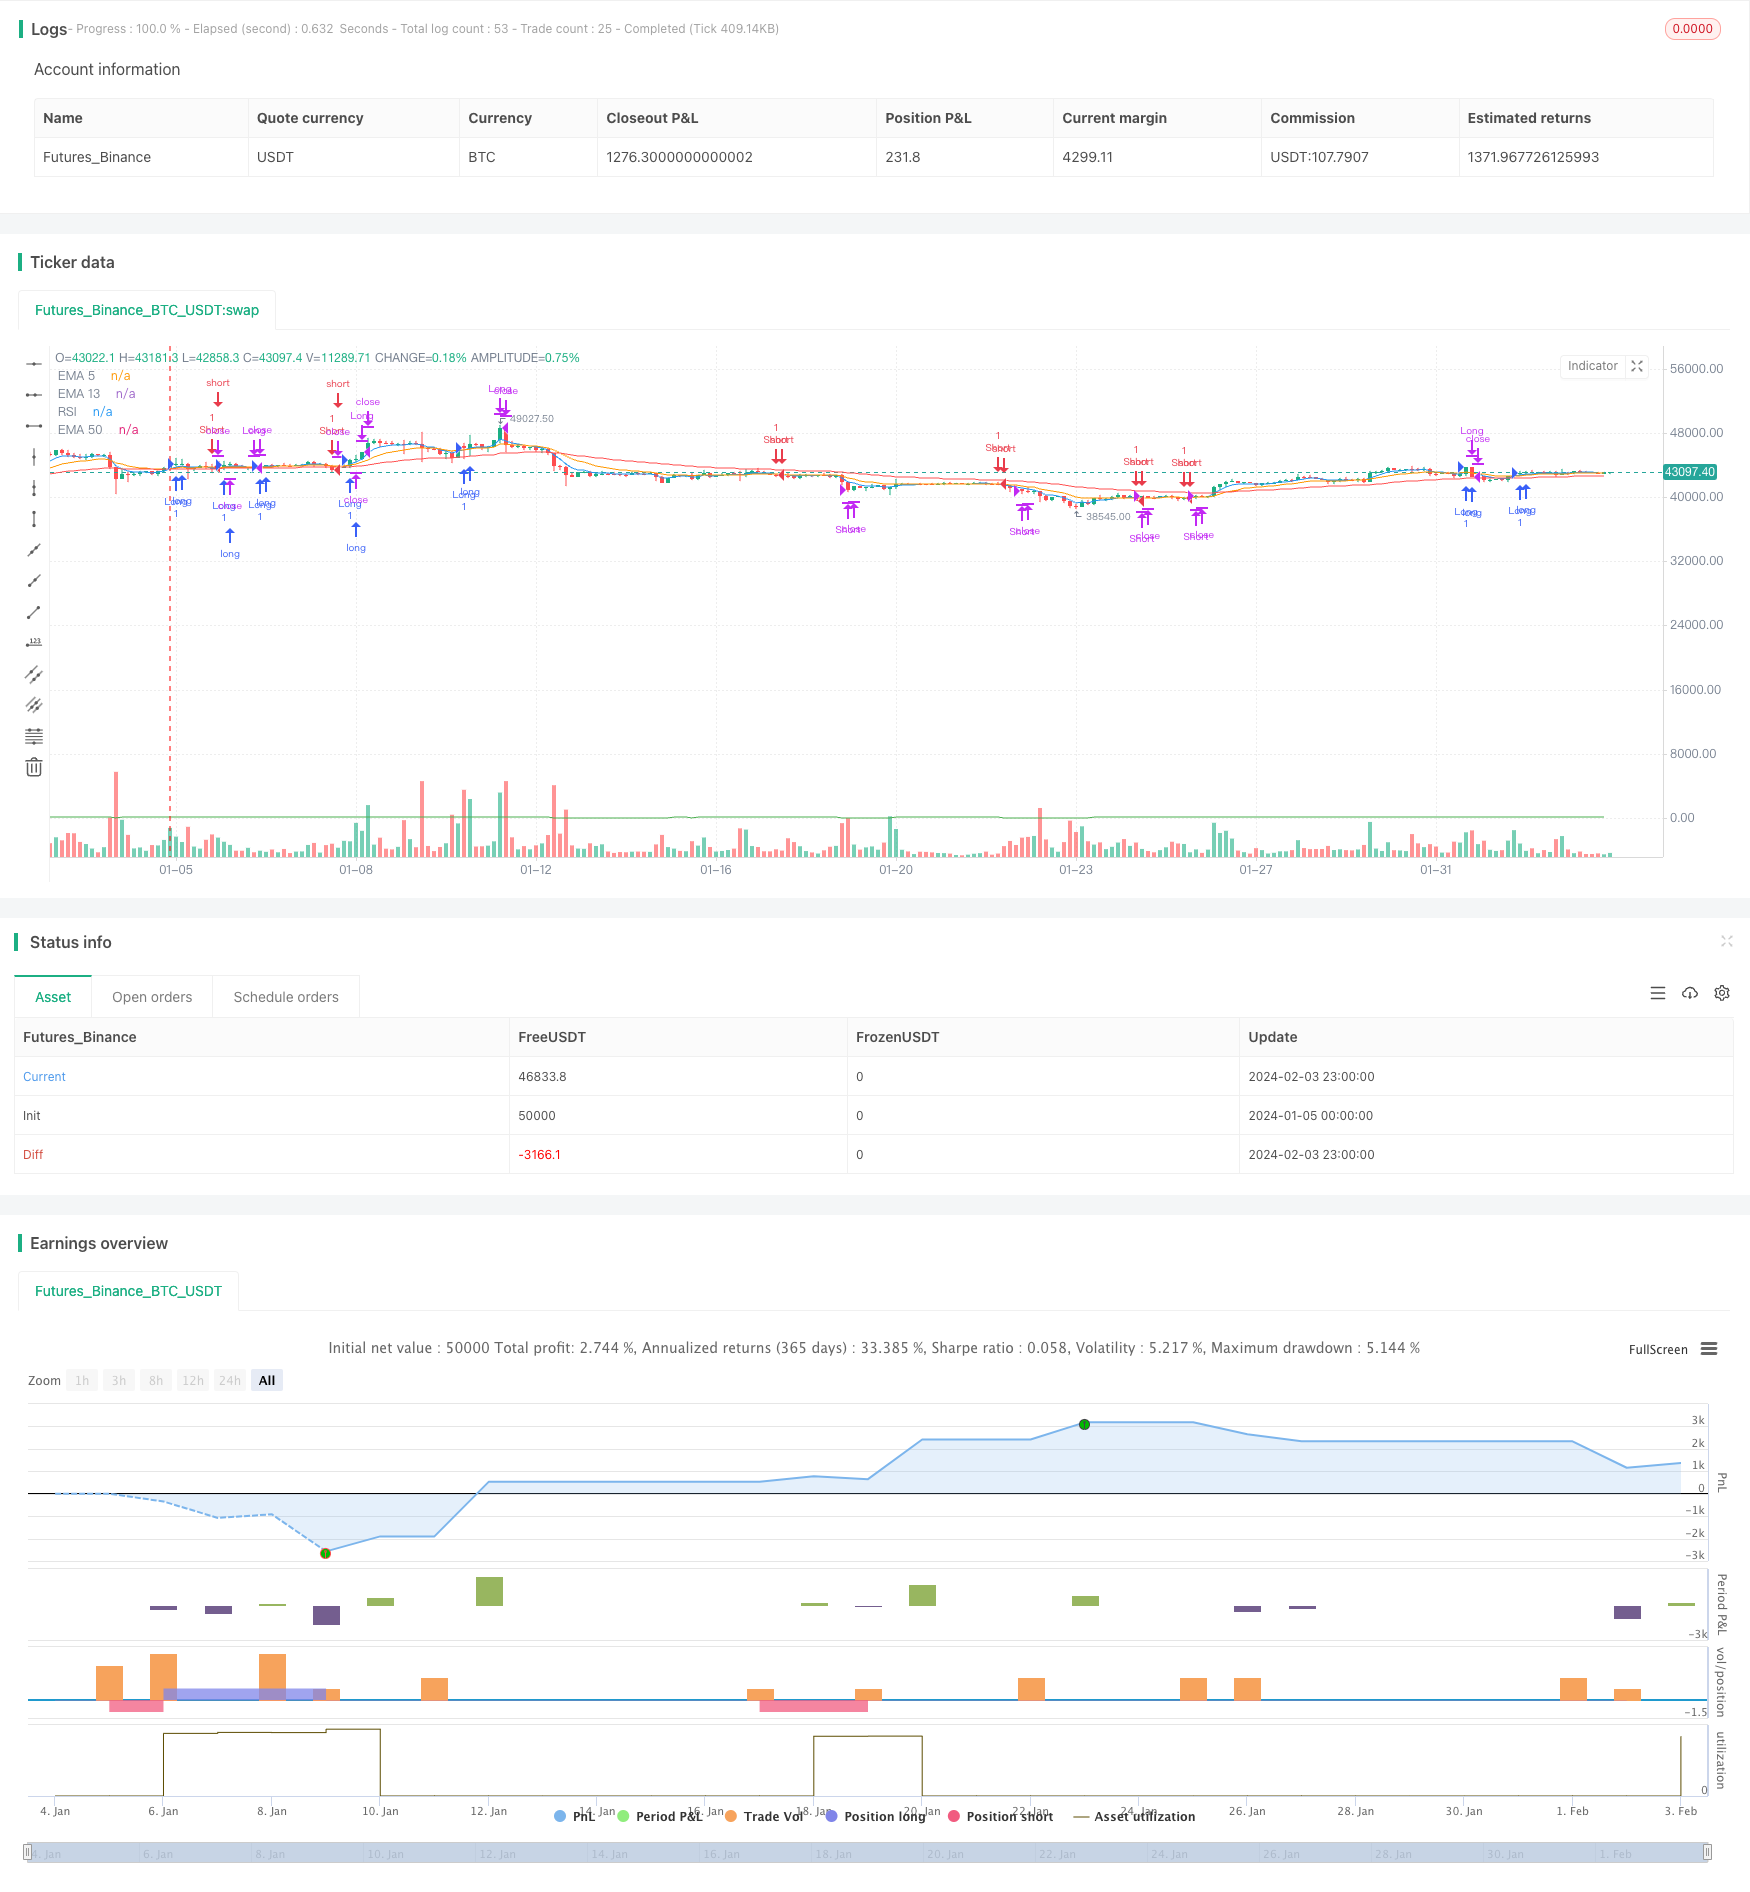
Overview
This strategy combines the EMA and RSI indicators to identify trend direction and enter positions after trend confirmation, avoiding overbuying and overselling by incorporating the RSI indicator. The strategy is simple and practical for medium to long term trend trading.
Strategy Logic
The strategy utilizes the 5-day EMA, 13-day EMA and 50-day EMA moving averages. When the 5-day EMA crosses above the 13-day EMA, it is viewed as a profit opportunity to go long. When the 5-day EMA crosses below the 13-day EMA, it is viewed as a stop loss opportunity to go short. In addition, long positions can only be opened when the price is above the 50-day EMA, and short positions can be opened only when the price is below the 50-day EMA, ensuring the trading direction is consistent with the major trend.
After entering a position, if the RSI becomes overbought (above 70) or the 5-day EMA crosses back below the 13-day EMA, long positions will be closed for profit taking. If the RSI becomes oversold (below 30) or the 5-day EMA crosses back above the 13-day EMA, short positions will be closed for profit.
Advantage Analysis
This strategy combines trend following signals and overbought/oversold indications, which can effectively capture profit opportunities along the main trend direction while avoiding being trapped in range-bound markets. The smoothness of EMAs helps reduce false signals. Also, the RSI settings prevent chasing gains and cutting losses excessively before trend reversals.
Risk Analysis
The strategy relies mainly on moving averages, which can generate more closing signals in winding consolidation markets, failing to hold longer-term positions. If a trend reversal occurs, the trader may not be able to follow the new opportunity promptly. In addition, the parameters of moving averages and RSI can impact strategy performance.
Risks can be reduced by loosening holding conditions, optimizing parameter combinations, incorporating more indicators, etc.
Optimization Directions
The strategy can be optimized in the following aspects:
Add position sizing mechanisms like fixed percentage to control single trade risk.
Optimize EMA and RSI parameters to find the best combination, testing more cycle lengths.
Incorporate more indicators like BO IntegerField to determine trends and reversals based on more factors.
Add automatic stop loss price setting.
Conclusion
The strategy is simple and practical overall. The use of only EMA and RSI requires less parameter optimization and market judgment, making it easy to grasp and backtest. However, flexibility and robustness may be slightly compromised, requiring further enhancements to adapt to more complex market environments. Still, for medium to long term trend trading, it provides a sound approach.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | RSI Length |
Source Pine Script
/*backtest
start: 2024-01-05 00:00:00
end: 2024-02-04 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA, RSI, and Price Crossover Strategy", overlay=true, default_qty_value = 1)

// Define the EMA lengths
ema5 = ta.ema(close, 5)
ema13 = ta.ema(close, 13)
ema50 = ta.ema(close, 50)

// Define the RSI length
rsiLength = input(14, title="RSI Length")
rsi = ta.rsi(close, rsiLength)

// Define the conditions for long and short positions
longCondition = ta.crossover(ema5, ema13) and close > ema50
shortCondition = ta.crossunder(ema5, ema13) and close < ema50

// Execute long and short positions
if (longCondition)
    strategy.entry("Long", strategy.long)
if (shortCondition)
    strategy.entry("Short", strategy.short)

// Define the exit conditions
exitLongCondition = rsi > 70 or ta.crossunder(ema5, ema13)
exitShortCondition = rsi < 30 or ta.crossover(ema5, ema13)

// Exit long and short positions
if (exitLongCondition)
    strategy.close("Long")
if (exitShortCondition)
    strategy.close("Short")

// Plot EMAs on the chart
plot(ema5, color=color.blue, title="EMA 5")
plot(ema13, color=color.orange, title="EMA 13")
plot(ema50, color=color.red, title="EMA 50")

// Create a separate panel for RSI
rsiPanel = plot(rsi, color=color.green, title="RSI")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Exponential-Moving-Average-and-Relative-Strength-Index-Combination-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover with RSI Trend Confirmation StrategyPine Script · Trend following · 3h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d