Strategy vault / Trend following
Ichimoku Mixed Equilibrium Table Macd and Tsi Combined Strategy
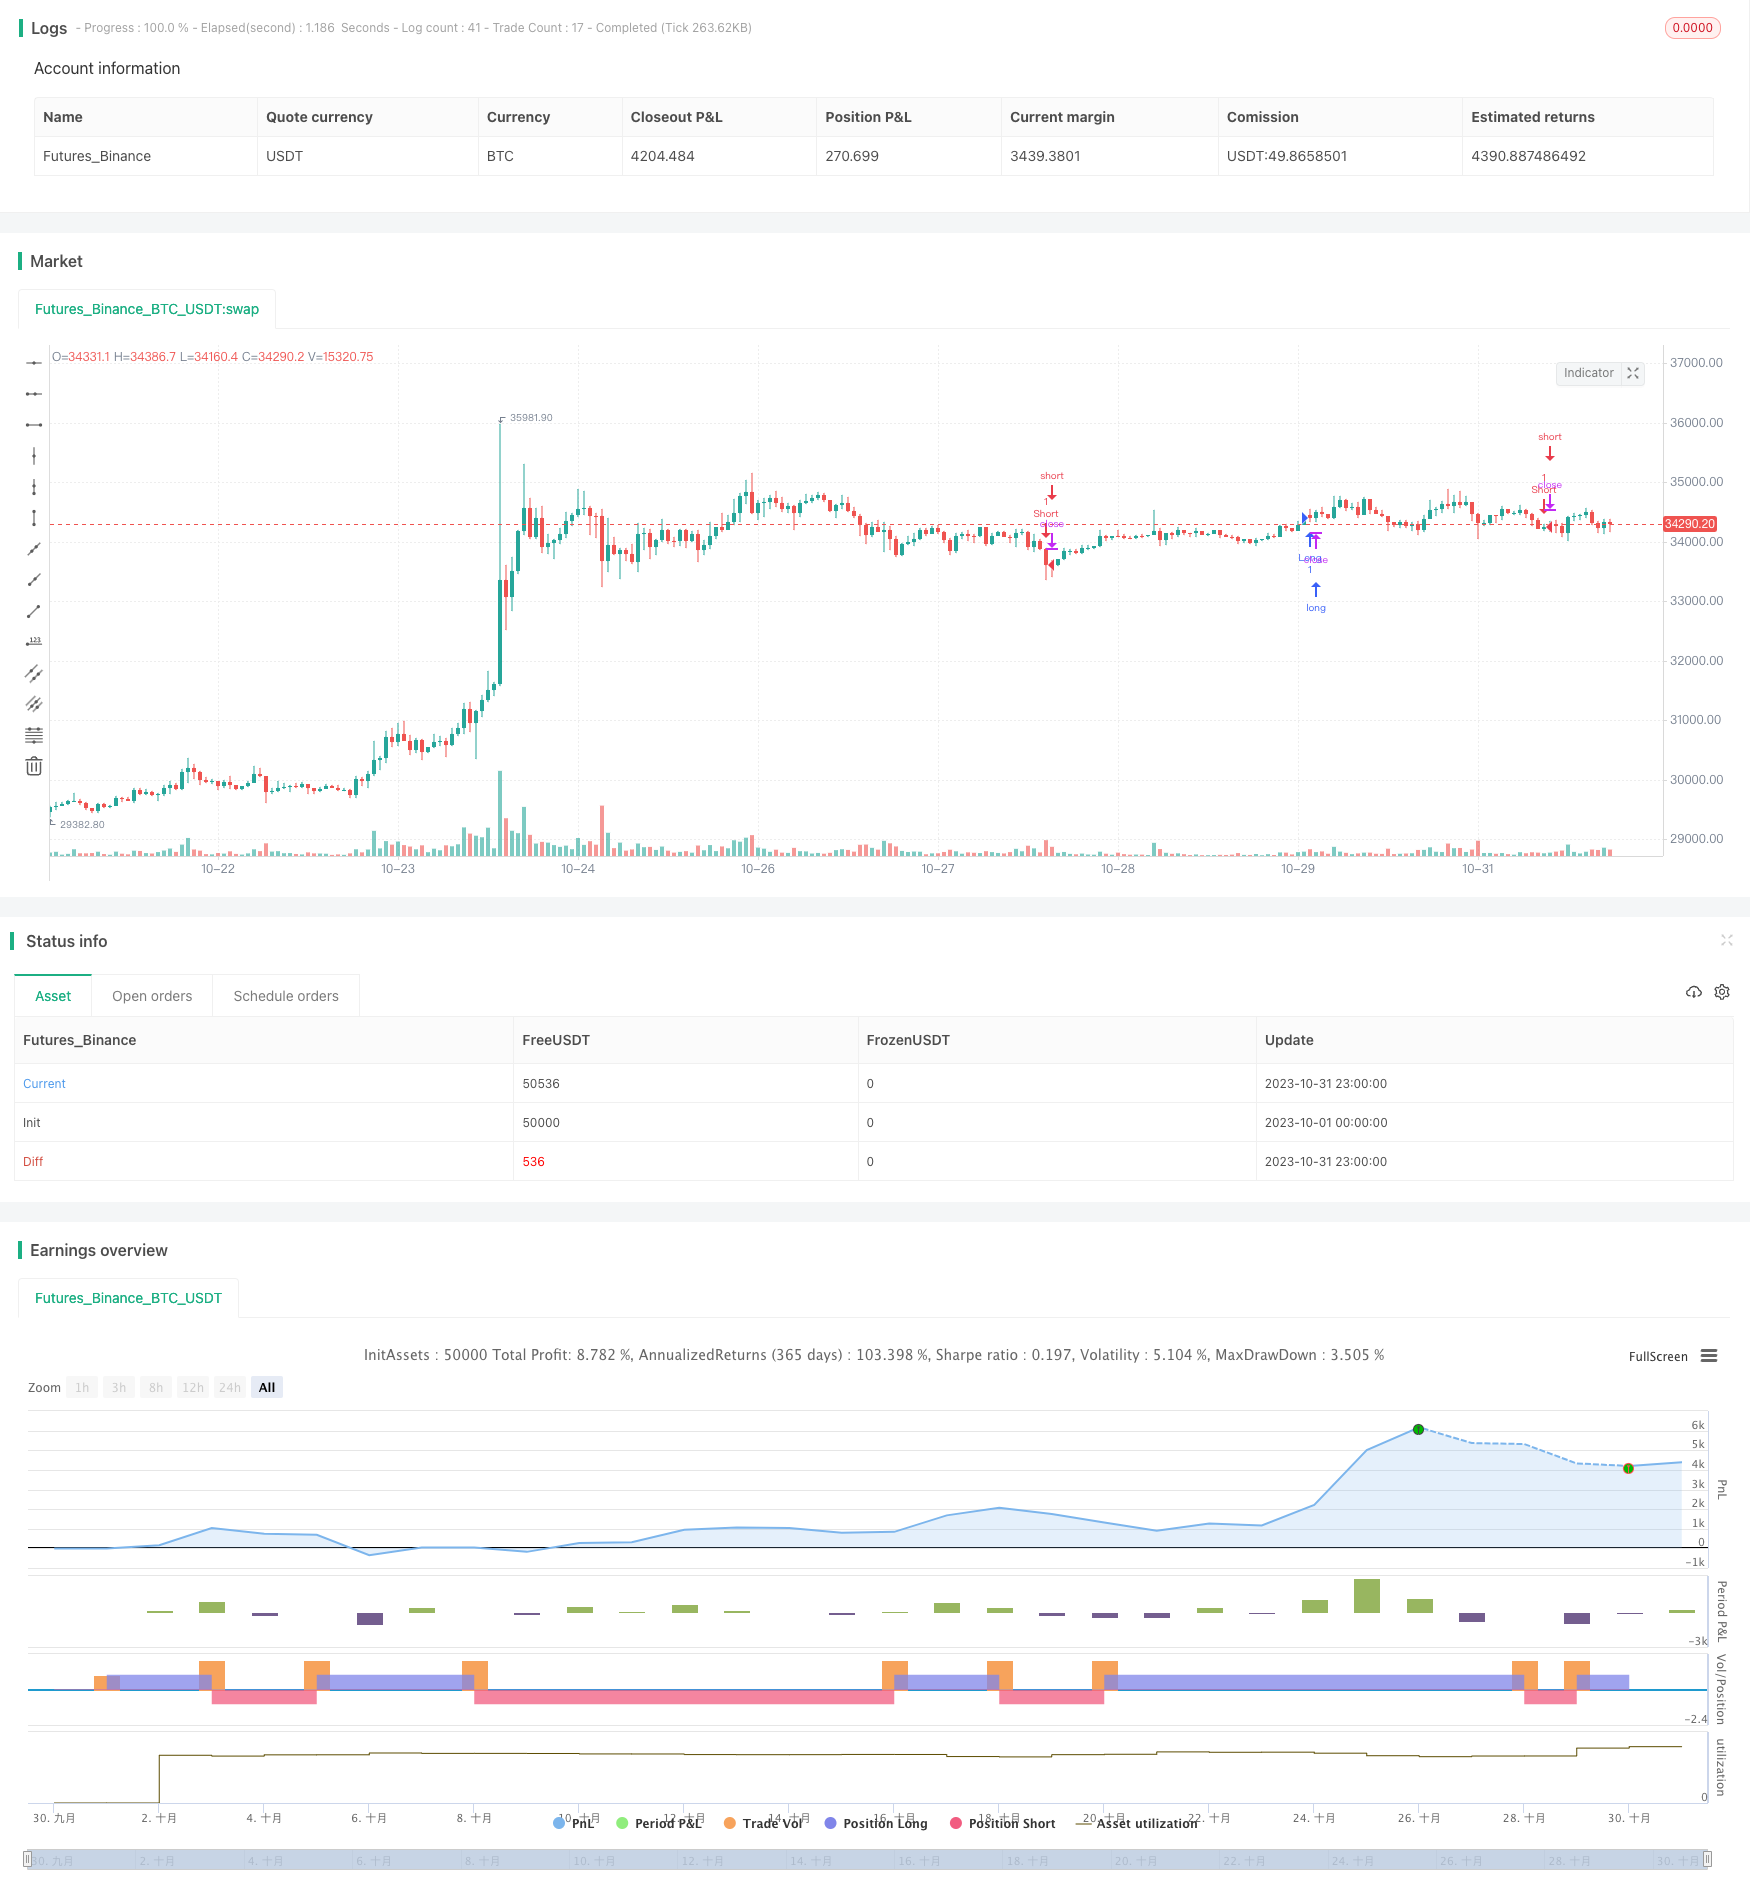
This strategy comprehensively uses technical indicators such as Ichimoku Kinko Hyo, Macd, Chaikin Money Flow and Tsi Oscillator to accurately judge the direction of market trends for short-term trading. The strategy…
I. Strategy Overview
This strategy comprehensively uses technical indicators such as Ichimoku Kinko Hyo, Macd, Chaikin Money Flow and Tsi Oscillator to accurately judge the direction of market trends for short-term trading.
II. Strategy Principle
The strategy uses the Tenkan-sen line, Kijun-sen line, Senkou Span A and Senkou Span B lines in Ichimoku to judge intraday price trends. At the same time, it combines the cross signals of the fast and slow moving average lines of Macd and the money flow indicator and oscillation indicator to determine the inflow and outflow of funds. After the comprehensive judgment of multiple indicators, the buy and sell decisions are made.
When the Tenkan-sen line crosses above the Kijun-sen line, the Chikou Span is above the 0 axis, and the closing price is above the Ichimoku cloud, it is a bullish signal. On the contrary, when the Tenkan-sen line crosses below the Kijun-sen line, the Chikou Span is below the 0 axis, and the closing price is below the cloud, it is a bearish signal. At the same time, the strategy detects whether the MACD histogram is positive and whether the Chaikin Money Flow indicator and the TSI oscillator are positive in the same direction. If the indicators are bullish in the same direction, long position is opened by buying in, and if the indicators are bearish in the same direction, short position is opened by selling out.
When the indicator issues a signal opposite to the previous one, a reverse trade is made to flatten the previous position.
III. Advantages of The Strategy
Using a combination of multiple indicators improves judgment accuracy.
Short-term operations track market fluctuations in real time.
No manual intervention, fully automated algorithmic trading.
IV. Risks of The Strategy and Solutions
The combined judgment of multiple indicators being bullish or bearish at the same time has the risk of misjudgment. Some judge criteria could be appropriately relaxed to reduce misjudgment rate.
High-frequency short-term trading has relatively high commission fees and it's hard to catch trends. Position holding period could be appropriately extended to seek excess returns to cover costs.
No stop loss setting may lead to greater losses. Appropriate stop loss points or moving stop loss can be set based on the ATR.
V. Directions for Strategy Optimization
Optimize parameter combinations. Adjust moving average parameters to adapt to different cycles and varieties.
Increase stop loss mechanism. Set dynamic stop loss lines combined with the ATR indicator.
Increase position management. Dynamically adjust trading volume proportions.
Combine machine learning technology to optimize indicators and signals.
VI. Conclusion
This strategy comprehensively uses multiple technical indicators to determine trend fluctuations in real time for high-frequency short-term trading. Although there are some risks, it can be improved through optimization. The strategy is worth further in-depth research and live trading verification. By increasing stop loss and position management, trading risks could be reduced.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Tenkan-Sen Bars |
| v_input_2 | 30 | Kijun-Sen Bars |
| v_input_3 | 52 | Senkou-Span B Bars |
| v_input_4 | 26 | Chikou-Span Offset |
| v_input_5 | 26 | Senkou-Span Offset |
| v_input_6 | true | Long Entry |
| v_input_7 | true | Short Entry |
| v_input_8 | 17 | Fast Length |
| v_input_9 | 28 | Slow Length |
| v_input_10_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_11 | 5 | Signal Smoothing |
| v_input_12 | true | Simple MA(Oscillator) |
| v_input_13 | true | Simple MA(Signal Line) |
| v_input_14 | 8 | CMF Length |
| v_input_15 | 8 | Long Length |
| v_input_16 | 8 | Short Length |
Source Pine Script
/*backtest
start: 2023-10-01 00:00:00
end: 2023-10-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © exlux99

//@version=4
strategy("Ichimoku with MACD/ CMF/ TSI", overlay=true, margin_long=0, margin_short=0)


//Inputs
ts_bars = input(10, minval=1, title="Tenkan-Sen Bars")
ks_bars = input(30, minval=1, title="Kijun-Sen Bars")
ssb_bars = input(52, minval=1, title="Senkou-Span B Bars")
cs_offset = input(26, minval=1, title="Chikou-Span Offset")
ss_offset = input(26, minval=1, title="Senkou-Span Offset")
long_entry = input(true, title="Long Entry")
short_entry = input(true, title="Short Entry")

middle(len) => avg(lowest(len), highest(len))

// Ichimoku Components
tenkan = middle(ts_bars)
kijun = middle(ks_bars)
senkouA = avg(tenkan, kijun)
senkouB = middle(ssb_bars)


ss_high = max(senkouA[ss_offset-1], senkouB[ss_offset-1])
ss_low = min(senkouA[ss_offset-1], senkouB[ss_offset-1])

// Entry/Exit Signals
fast_length = input(title="Fast Length", type=input.integer, defval=17)
slow_length = input(title="Slow Length", type=input.integer, defval=28)
src = input(title="Source", type=input.source, defval=close)
signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 5)
sma_source = input(title="Simple MA(Oscillator)", type=input.bool, defval=true)
sma_signal = input(title="Simple MA(Signal Line)", type=input.bool, defval=true)

// Calculating
fast_ma = sma_source ? sma(src, fast_length) : ema(src, fast_length)
slow_ma = sma_source ? sma(src, slow_length) : ema(src, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal ? sma(macd, signal_length) : ema(macd, signal_length)
hist = macd - signal


tk_cross_bull = tenkan > kijun
tk_cross_bear = tenkan < kijun
cs_cross_bull = mom(close, cs_offset-1) > 0
cs_cross_bear = mom(close, cs_offset-1) < 0
price_above_kumo = close > ss_high
price_below_kumo = close < ss_low


//CMF
lengthA = input(8, minval=1, title="CMF Length")
ad = close==high and close==low or high==low ? 0 : ((2*close-low-high)/(high-low))*volume
mf = sum(ad, lengthA) / sum(volume, lengthA)


//TSI
long = input(title="Long Length", type=input.integer, defval=8)
short = input(title="Short Length", type=input.integer, defval=8)
price = close
double_smooth(src, long, short) =>
	fist_smooth = ema(src, long)
	ema(fist_smooth, short)
pc = change(price)
double_smoothed_pc = double_smooth(pc, long, short)
double_smoothed_abs_pc = double_smooth(abs(pc), long, short)
tsi_value = 100 * (double_smoothed_pc / double_smoothed_abs_pc)


bullish = tk_cross_bull and cs_cross_bull and price_above_kumo and hist > 0 and mf > 0.1 and tsi_value > 0
bearish = tk_cross_bear and cs_cross_bear and price_below_kumo and hist < 0  and mf < -0.1 and tsi_value < 0


strategy.entry("Long", strategy.long, when=bullish and long_entry)
strategy.entry("Short", strategy.short, when=bearish and short_entry)

strategy.close("Long", when=bearish and not short_entry)
strategy.close("Short", when=bullish and not long_entry)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Mixed-Equilibrium-Table-Macd-and-Tsi-Combined-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Ichimoku Cloud MACD and Stochastic Based Multi Timeframe Trend Tracking StrategyPine Script · Trend following · 4h
- Multi Dimensional Trend Analysis with ATR Based Dynamic Stop Management StrategyPine Script · Trend following · 1d
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d