Strategy vault / Trend following
MACD Crypto Trading Strategy
This is a simple yet efficient MACD crypto trading strategy specifically designed for cryptocurrency markets and suitable for higher timeframe charts like 1 hour, 4 hours, 1 day etc. The strategy uses the MACD…
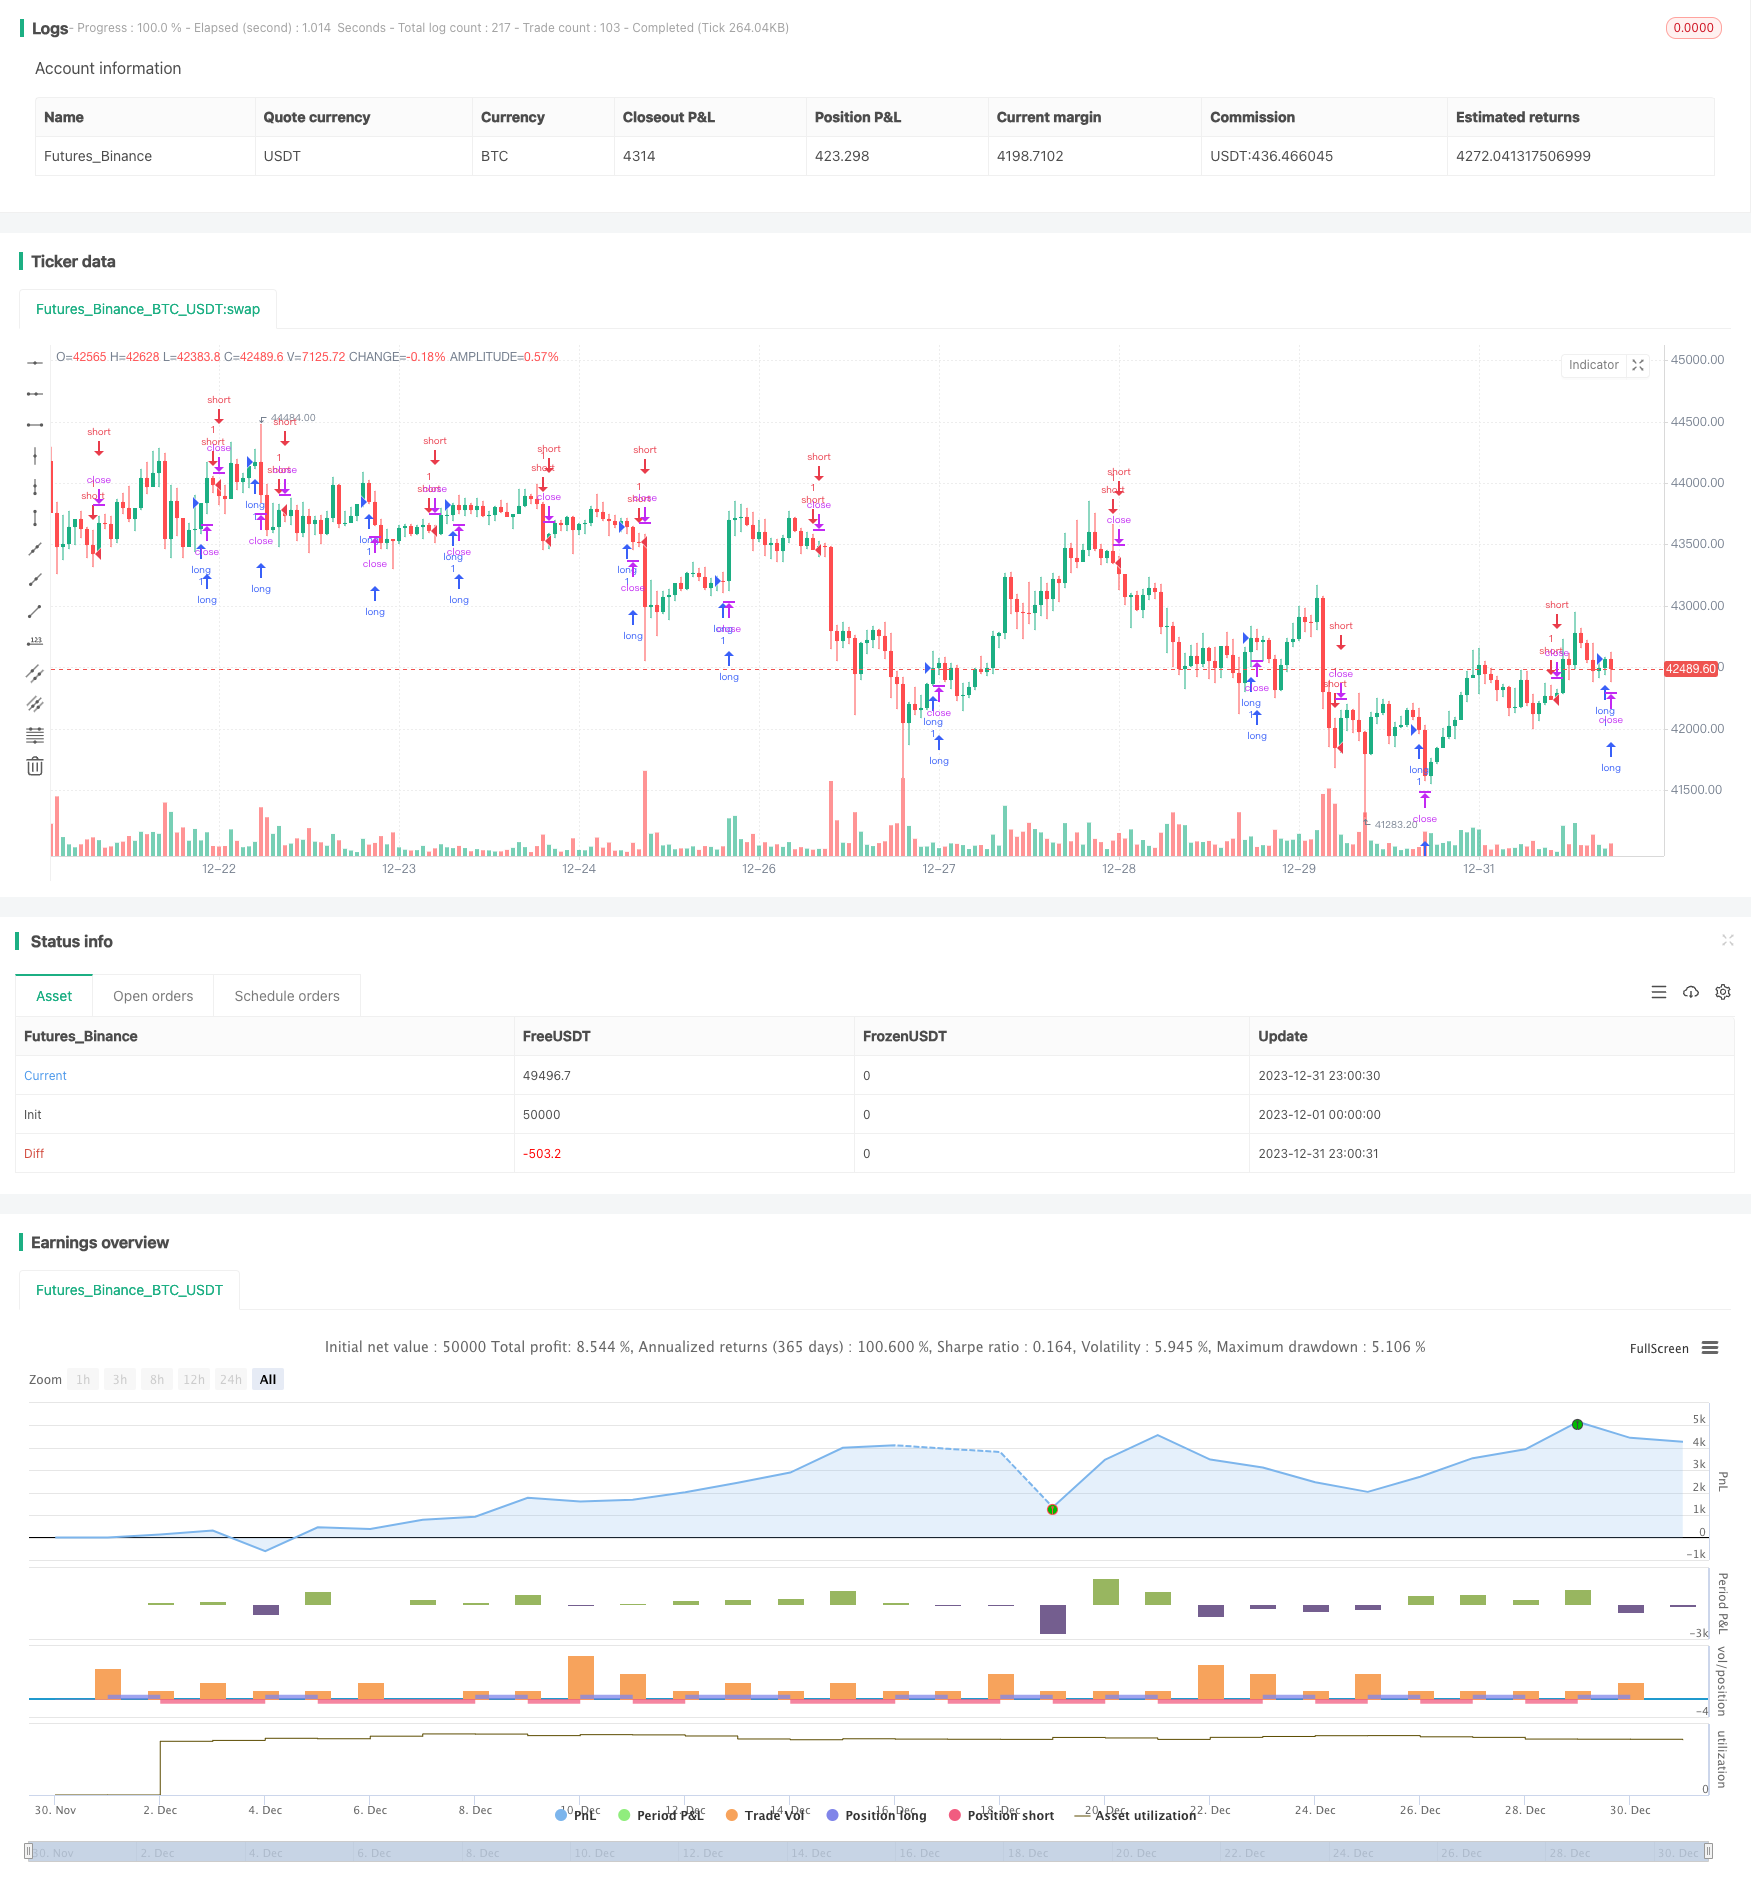
Overview
This is a simple yet efficient MACD crypto trading strategy specifically designed for cryptocurrency markets and suitable for higher timeframe charts like 1 hour, 4 hours, 1 day etc. The strategy uses the MACD indicator to determine market trend direction and trading signals are generated with simple moving average. The biggest advantage of this strategy is being simple, efficient and easy to understand and implement, especially suitable for the highly volatile crypto markets. However there are also some risks that need further optimization and improvement.
Strategy Logic
The strategy utilizes the MACD indicator to decide market trend and generate trade signals. MACD consists of the fast line, slow line and MACD histogram. The fast line is the short term moving average and the slow line is the long term moving average. When fast line crosses above slow line, it's a buy signal. When fast line crosses below slow line, it's a sell signal. The MACD histogram is the difference between fast line and slow line. Positive histogram means an upward trending bull market while negative histogram means a downward bear market. This strategy uses simple moving average to further validate the signals and avoid false signals. Specifically, only when both the MACD histogram and simple moving average are positive, the strategy will generate long signal to go long. When both the MACD histogram and simple moving average are negative, the strategy will generate short signal to go short. Using the MACD histogram to determine market direction can prevent trading against the trend.
Advantage Analysis
The biggest advantages of this simple yet efficient strategy are:
Using MACD to determine market direction, a mature and reliable technical indicator to accurately judge the trend;
Combining simple moving average for signal filtering, avoiding false signals and improving accuracy;
Specially designed for the highly volatile crypto markets where MACD performs the best;
The logic is simple and clear, easy to understand and implement, low barrier for adoption;
Can run on higher timeframes to lower trade frequency and reduce trading costs.
Risk Analysis
However there are also some risks of this strategy:
Using simple moving average for filtering might miss the best entry price in some market condition;
No profit taking or stop loss in place might lead to huge single trade loss;
Possible lagging signals and false signals might cause unnecessary loss;
Haven't considered the impact of trading timeframe and frequency on overall profitability.
These risks need to be addressed by further optimization.
Optimization Directions
Based on the risks mentioned above, the strategy can be improved in the following directions:
Test different parameters and indicators combinations to find the optimal setting;
Add stop loss and profit taking logic to limit max single trade loss;
Optimize entry logic with more strict signal confirmation to ensure high quality signals;
Consider the impact of different trading timeframe and frequency on the overall profitability.
Through optimizations in these directions, the stability, profitability and viability of this strategy can be greatly enhanced.
Summary
In summary, this is a MACD trading strategy with huge practical value. It's simple, efficient and easy to implement, perfect for people who want to get started with algo trading quickly. At the same time there is ample room for further optimizations to turn it into a stable money making algorithm suitable for long term live trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © SoftKill21

//@version=4
strategy("MACD crypto strategy", overlay=true)

// Getting inputs
//fast_length = input(title="Fast Length", type=input.integer, defval=12)
//slow_length = input(title="Slow Length", type=input.integer, defval=26)
//src = input(title="Source", type=input.source, defval=close)
//signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9)
//sma_source = input(title="Simple MA(Oscillator)", type=input.bool, defval=true)
//sma_signal = input(title="Simple MA(Signal Line)", type=input.bool, defval=false)

fast_length = 12
slow_length = 26
src = input(title="Source", type=input.source, defval=close)
signal_length = 9
sma_source = true
sma_signal = false

// Calculating
fast_ma = sma_source ? sma(src, fast_length) : ema(src, fast_length)
slow_ma = sma_source ? sma(src, slow_length) : ema(src, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal ? sma(macd, signal_length) : ema(macd, signal_length)
hist = macd - signal


longcondition = hist > 0
shortcondition = hist < 0

//sl = input(0.5, title="SL")
//tp = input(0.1, title="tp")

strategy.entry("long",1,when=longcondition)
strategy.entry("short",0,when=shortcondition)

//strategy.exit("x_long", "long" ,loss = close * sl / syminfo.mintick, profit = close * tp / syminfo.mintick , alert_message = "closelong")
//strategy.entry("short",0, when= loss = close * sl / syminfo.mintick)

//strategy.exit("x_short", "short" , loss = close * sl / syminfo.mintick, profit  = close * tp / syminfo.mintick,alert_message = "closeshort")

// risk = input(2, type=input.float,title="Risk percentage of BALANCE")
// strategy.risk.max_intraday_loss(risk, strategy.percent_of_equity)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Crypto-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d