Strategy vault / Trend following
Moving Average Crossover Strategy for Two way Trading
This strategy calculates moving averages of different periods and issues trading signals when the shorter period moving average crosses over or crosses below the longer period moving average. It belongs to the…
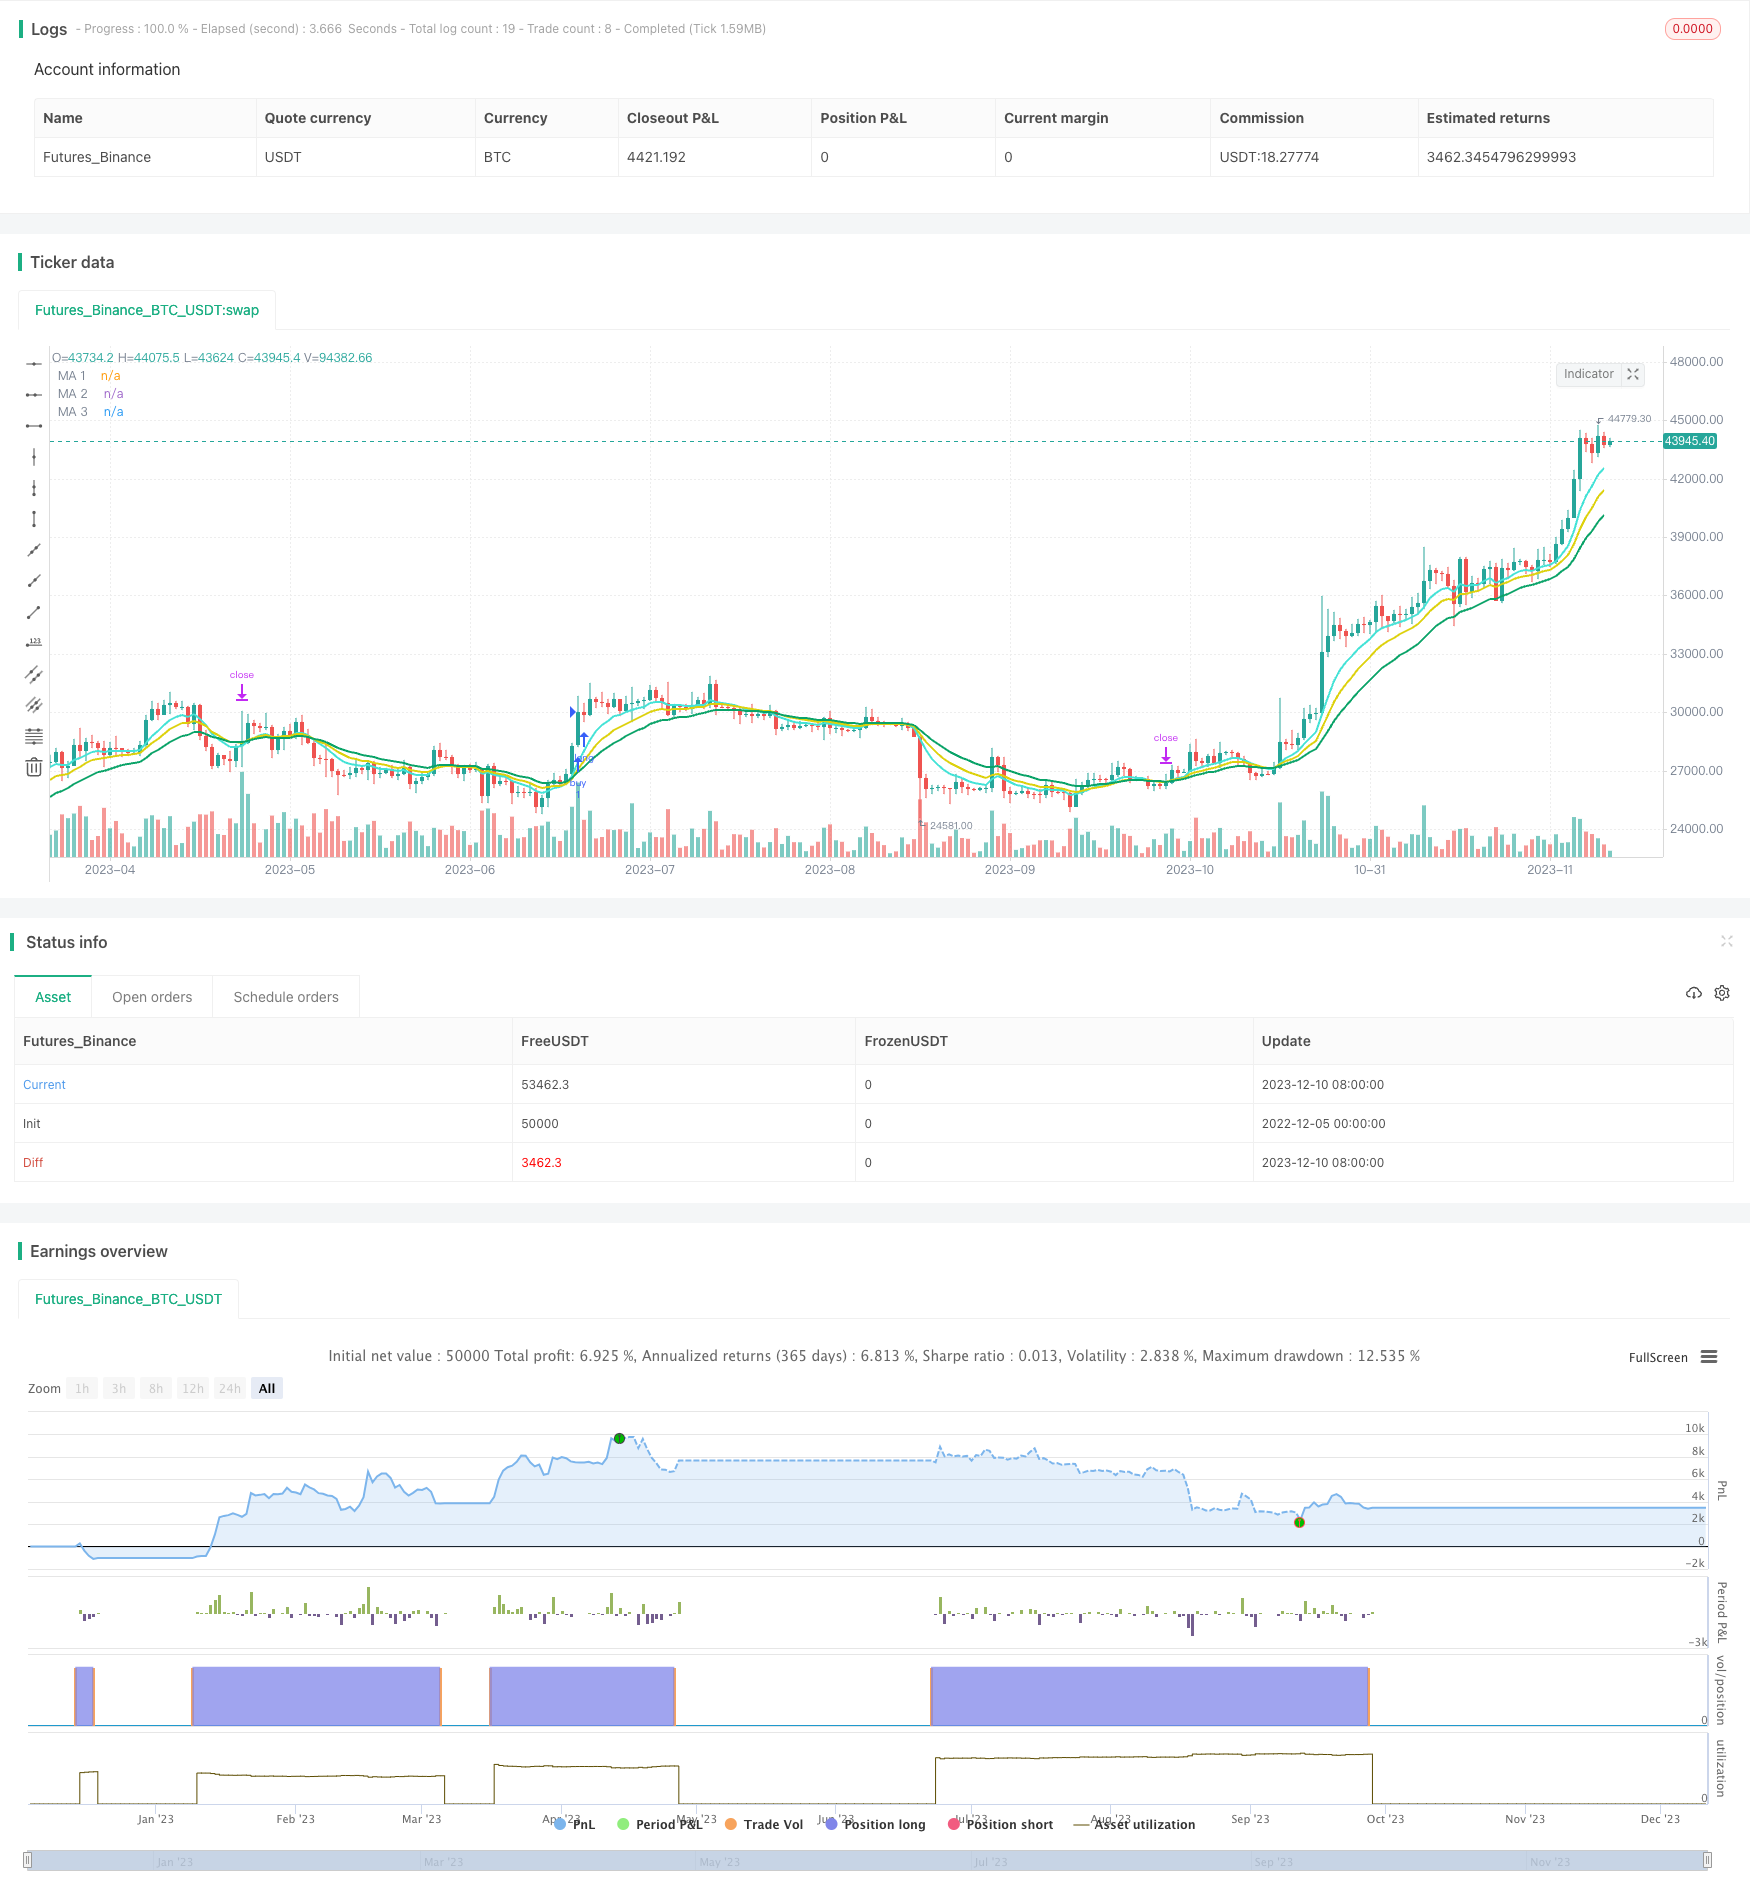
Overview
This strategy calculates moving averages of different periods and issues trading signals when the shorter period moving average crosses over or crosses below the longer period moving average. It belongs to the typical moving average crossover system. The strategy supports both long and short positions to achieve two-way trading.
Principles
The strategy judges market trends and generates trading signals based on the crossover between moving averages of different periods. It uses three moving average lines of 8-period, 13-period and 21-period, where the 8-period line is the shorter period line and the 21-period line is the longer period line. A long signal is triggered when the 8-period line crosses over the 21-period line. A short signal is triggered when the 8-period line crosses below the 21-period line.
In actual trading execution, the strategy also includes a filtering condition to avoid being trapped in choppy markets. It only places orders when the closing price is higher (long signal) or lower (short signal) than the crossover point. This can effectively filter out some false signals.
Advantages
- Applies moving average crossover rules to effectively track market trends
- Adds trade filters to avoid some false signals and being trapped
- Supports two-way trading to profit in both bull and bear markets
- Captures turns between major levels using inter-period moving averages
- Simple and clear logic, easy to understand and optimize
Risks
- May fail or generate excessive false signals in highly volatile markets
- Unable to judge when prices move sideways, missing opportunities
- Inter-period crossover has a lag, may not timely capture short-term trend changes
- Does not consider price volatility, parameters need adjustments for different volatility levels
- No stop loss or take profit, risks unlimited losses
Solutions for Risks
- Combine other indicators to judge markets, avoid volatility impact
- Lower moving average periods for higher sensitivity
- Add stop loss and take profit to control risks and drawdowns
Optimization Directions
- Combine other indicators like MACD and KDJ to improve efficacy
- Test impacts of different parameter settings on overall strategy performance
- Set adaptive parameters based on market type and volatility levels
- Optimize moving average calculation methods using DEMA, ZLEMA etc.
- Add stop loss and take profit logic
- Optimize quant backtesting metrics to determine best parameters
Conclusion
The strategy has a clear logic of using simple moving average crossover to determine relationships between short-term and long-term trends and capture rotation opportunities. It supports two-way trading and is easy to understand and optimize. But some risks exist like ineffective handling of specific market conditions and lack of risk control. Subsequent technical indicator combos and parameter optimization can further improve strategy stability and profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Strategy Direction: long | short | all |
| v_input_2 | 2020 | Backtest Start Year |
| v_input_3 | true | Backtest Start Month |
| v_input_4 | true | Backtest Start Day |
| v_input_5 | 2030 | Backtest Stop Year |
| v_input_6 | 12 | Backtest Stop Month |
| v_input_7 | 30 | Backtest Stop Day |
| v_input_8 | true | Order quantity |
| v_input_9 | false | Plot indicators? |
| v_input_10 | 0 | Type: EMA | DEMA | Butterworth_2Pole | Gaussian | Geometric_Mean | LowPass | McGuinley | SMA | Sine_WMA | Smoothed_MA | Super_Smoother | Triangular_MA | Wilders | Zero_Lag |
| v_input_11 | 8 | MA 1 |
| v_input_12 | 13 | MA 2 |
| v_input_13 | 21 | MA 3 |
| v_input_14 | 55 | MA 4 |
| v_input_15 | 89 | MA 5 |
| v_input_16 | 120 | IB |
| v_input_17 | 121 | 2B |
| v_input_18 | 200 | 21b |
| v_input_19 | 221 | 22b |
| v_input_20 | true | Enable 1 |
| v_input_21 | true | Enable 2 |
| v_input_22 | true | Enable 3 |
| v_input_23 | false | Enable 4 |
| v_input_24 | false | Enable 5 |
| v_input_25 | false | Enable 6 |
| v_input_26 | false | Enable 7 |
| v_input_27 | false | Enable x |
| v_input_28 | false | Enable x |
| v_input_29 | 3 | *** Gaussian poles *** |
Source Pine Script
/*backtest
start: 2022-12-05 00:00:00
end: 2023-12-11 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//Converted to strategy by shawnteoh

strategy(title = "MA Emperor insiliconot Strategy" , overlay=true, pyramiding=1, precision=8)
strat_dir_input = input(title="Strategy Direction", defval="long", options=["long", "short", "all"])
strat_dir_value = strat_dir_input == "long" ? strategy.direction.long : strat_dir_input == "short" ? strategy.direction.short : strategy.direction.all
strategy.risk.allow_entry_in(strat_dir_value)

// Testing start dates
testStartYear = input(2020, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)
//Stop date if you want to use a specific range of dates
testStopYear = input(2030, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(30, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)
// Order size
orderQty = input(1, "Order quantity", type = float)
// Plot indicator
plotInd = input(false, "Plot indicators?", type = bool)

testPeriod() =>
    time >= testPeriodStart and time <= testPeriodStop ? true : false

haClose = close
haOpen  = open
haHigh  = high
haLow   = low

haClose := (open + high + low + close) / 4
haOpen  := (nz(haOpen[1]) + nz(haClose[1])) / 2
haHigh  := max(high, max(haOpen, haClose))
haLow   := min(low , min(haOpen, haClose))

ssrc = close
ha = false

o = ha ? haOpen : open
c = ha ? haClose : close
h = ha ? haHigh : high
l = ha ? haLow : low

ssrc := ssrc == close ? ha ? haClose : c : ssrc
ssrc := ssrc == open ? ha ? haOpen : o : ssrc
ssrc := ssrc == high ? ha ? haHigh : h : ssrc
ssrc := ssrc == low ? ha ? haLow : l : ssrc
ssrc := ssrc == hl2 ? ha ? (haHigh + haLow) / 2 : hl2 : ssrc
ssrc := ssrc == hlc3 ? ha ? (haHigh + haLow + haClose) / 3 : hlc3 : ssrc
ssrc := ssrc == ohlc4 ? ha ? (haHigh + haLow + haClose+ haOpen) / 4 : ohlc4 : ssrc

type = input(defval = "EMA", title = "Type", options = ["Butterworth_2Pole", "DEMA", "EMA", "Gaussian", "Geometric_Mean", "LowPass", "McGuinley", "SMA", "Sine_WMA", "Smoothed_MA", "Super_Smoother",  "Triangular_MA", "Wilders", "Zero_Lag"])

len1=input(8, title ="MA 1")
len2=input(13, title = "MA 2")
len3=input(21, title = "MA 3")
len4=input(55, title = "MA 4")
len5=input(89, title = "MA 5")
lenrib=input(120, title = "IB")
lenrib2=input(121, title = "2B")
lenrib3=input(200, title = "21b")
lenrib4=input(221, title = "22b")

onOff1  = input(defval=true, title="Enable 1")
onOff2  = input(defval=true, title="Enable 2")
onOff3  = input(defval=true, title="Enable 3")
onOff4  = input(defval=false, title="Enable 4")
onOff5  = input(defval=false, title="Enable 5")
onOff6  = input(defval=false, title="Enable 6")
onOff7  = input(defval=false, title="Enable 7")
onOff8  = input(defval=false, title="Enable x")
onOff9  = input(defval=false, title="Enable x")


gauss_poles = input(3, "*** Gaussian poles ***",  minval = 1, maxval = 14)
linew = 2
shapes = false


variant_supersmoother(src,len) =>
    Pi = 2 * asin(1)
    a1 = exp(-1.414* Pi / len)
    b1 = 2*a1*cos(1.414* Pi / len)
    c2 = b1
    c3 = (-a1)*a1
    c1 = 1 - c2 - c3
    v9 = 0.0
    v9 := c1*(src + nz(src[1])) / 2 + c2*nz(v9[1]) + c3*nz(v9[2])
    v9

variant_smoothed(src,len) =>
    v5 = 0.0
    v5 := na(v5[1]) ? sma(src, len) : (v5[1] * (len - 1) + src) / len
    v5

variant_zerolagema(src, len) =>
    price = src
    l = (len - 1) / 2
    d = (price + (price - price[l]))
    z = ema(d, len)
    z

variant_doubleema(src,len) =>
    v2 = ema(src, len)
    v6 = 2 * v2 - ema(v2, len)
    v6

variant_WiMA(src, length) =>
    MA_s= nz(src)
    MA_s:=(src + nz(MA_s[1] * (length-1)))/length
    MA_s

fact(num)=>
    a = 1
    nn = num <= 1 ? 1 : num
    for i = 1 to nn
        a := a * i
    a

getPoles(f, Poles, alfa)=>
    filt = f
    sign = 1
    results = 0 + n//tv series spoofing
    for r = 1 to max(min(Poles, n),1)
	    mult  = fact(Poles) / (fact(Poles - r) * fact(r))
	    matPo = pow(1 - alfa, r)
        prev  = nz(filt[r-1],0)
        sum   =  sign * mult * matPo * prev
        results := results + sum
        sign  := sign * -1
    results := results - n
    results

variant_gauss(Price, Lag, Poles)=>
    Pi = 2 * asin(1)
    beta = (1 - cos(2 * Pi / Lag)) / ( pow (sqrt(2), 2.0 / Poles) - 1)
    alfa = -beta + sqrt(beta * beta +  2 * beta)
    pre = nz(Price, 0) * pow(alfa, Poles)
    filter = pre
    result = n > 0 ?  getPoles(nz(filter[1]), Poles, alfa) : 0
    filter := pre + result

variant_mg(src, len)=>
    mg = 0.0
    mg := na(mg[1]) ? ema(src, len) : mg[1] + (src - mg[1]) / (len * pow(src/mg[1], 4))
    mg

variant_sinewma(src, length) =>
    PI = 2 * asin(1)
    sum = 0.0
    weightSum = 0.0
    for i = 0 to length - 1
        weight = sin(i * PI / (length + 1))
        sum := sum + nz(src[i]) * weight
        weightSum := weightSum + weight
    sinewma = sum / weightSum
    sinewma

variant_geoMean(price, per)=>
    gmean = pow(price, 1.0/per)
    gx = for i = 1 to per-1
        gmean := gmean * pow(price[i], 1.0/per)
        gmean
    ggx = n > per? gx : price
    ggx


variant_butt2pole(pr, p1)=>
    Pi = 2 * asin(1)
    DTR = Pi / 180
    a1 = exp(-sqrt(2) * Pi / p1)
    b1 = 2 * a1 * cos(DTR * (sqrt(2) * 180 / p1))
    cf1 = (1 - b1 + a1 * a1) / 4
    cf2 = b1
    cf3 = -a1 * a1
    butt_filt = pr
    butt_filt := cf1 * (pr + 2 * nz(pr[1]) + nz(pr[2])) + cf2 * nz(butt_filt[1]) + cf3 * nz(butt_filt[2])

variant_lowPass(src, len)=>
    LP = src
    sr = src
    a = 2.0 / (1.0 + len)
    LP := (a - 0.25 * a * a) * sr + 0.5 * a * a * nz(sr[1]) - (a - 0.75 * a * a) * nz(sr[2]) + 2.0 * (1.0 - a) * nz(LP[1]) - (1.0 - a) * (1.0 - a) * nz(LP[2])
    LP


variant_sma(src, len) =>
    sum = 0.0
    for i = 0 to len - 1
        sum := sum + src[i] / len
    sum

variant_trima(src, length) =>
    len = ceil((length + 1) * 0.5)
    trima =  sum(sma(src, len), len)/len
    trima


variant(type, src, len) =>
      type=="EMA"   ? ema(src, len) :
      type=="LowPass" ? variant_lowPass(src, len) :
      type=="Linreg"  ? linreg(src, len, 0) :
      type=="Gaussian"  ? variant_gauss(src, len, gauss_poles) :
      type=="Sine_WMA"  ? variant_sinewma(src, len) :

      type=="Geometric_Mean"  ? variant_geoMean(src, len) :

      type=="Butterworth_2Pole" ? variant_butt2pole(src, len) :
      type=="Smoothed_MA"  ? variant_smoothed(src, len) :
      type=="Triangular_MA"  ? variant_trima(src, len) :
      type=="McGuinley" ? variant_mg(src, len) :
      type=="DEMA"  ? variant_doubleema(src, len):
      type=="Super_Smoother"  ? variant_supersmoother(src, len) :
      type=="Zero_Lag"  ? variant_zerolagema(src, len) :
      type=="Wilders"? variant_WiMA(src, len) : variant_sma(src, len)


c1=#44E2D6
c2=#DDD10D
c3=#0AA368
c4=#E0670E
c5=#AB40B2

cRed = #F93A00


ma1 =  variant(type, ssrc, len1)
ma2 =  variant(type, ssrc, len2)
ma3 =  variant(type, ssrc, len3)
ma4 =  variant(type, ssrc, len4)
ma5 =  variant(type, ssrc, len5)
ma6 =  variant(type, ssrc, lenrib)
ma7 =  variant(type, ssrc, lenrib2)
ma8 =  variant(type, ssrc, lenrib3)
ma9 =  variant(type, ssrc, lenrib4)

col1 = c1
col2 = c2
col3 = c3
col4 = c4
col5 = c5

p1 = plot(onOff1 ? ma1 : na, title = "MA 1",  color = col1,  linewidth = linew, style = linebr)
p2 = plot(onOff2 ? ma2 : na, title = "MA 2",  color = col2,  linewidth = linew, style = linebr)
p3 = plot(onOff3 ? ma3 : na, title = "MA 3",  color = col3,  linewidth = linew, style = linebr)
p4 = plot(onOff4 ? ma4 : na, title = "MA 4",  color = col4,  linewidth = linew, style = linebr)
p5 = plot(onOff5 ? ma5 : na, title = "MA 5",  color = col5,  linewidth = linew, style = linebr)
p6 = plot(onOff6 ? ma6 : na, title = "MA 6",  color = col5,  linewidth = linew, style = linebr)
p7 = plot(onOff7 ? ma7 : na, title = "MA 7",  color = col5,  linewidth = linew, style = linebr)
p8 = plot(onOff8 ? ma8 : na, title = "MA 8",  color = col5,  linewidth = linew, style = linebr)
p9 = plot(onOff9 ? ma9 : na, title = "MA 9",  color = col5,  linewidth = linew, style = linebr)

longCond = crossover(ma2, ma3)
if longCond and testPeriod()
    strategy.entry("buy", strategy.long, qty = orderQty, when = open > ma2[1])

shortCond = crossunder(ma2, ma3)
if shortCond and testPeriod()
    strategy.entry("sell", strategy.short, qty = orderQty, when = open < ma2[1])

plotshape(series=plotInd? longCond : na, title="P", style=shape.triangleup, location=location.belowbar, color=green, text="P", size=size.small)
plotshape(series=plotInd? shortCond : na, title="N", style=shape.triangledown, location=location.abovebar, color=red, text="N", size=size.small)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-Strategy-for-Two-way-Trading.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d