Strategy vault / Trend following
Moving Average Crossover Trading Strategy 442628
This strategy generates buy and sell signals based on the crossover of moving averages. It uses 8-day, 18-day and 50-day exponential moving averages (EMA). A buy signal is generated when the price breaks above the…
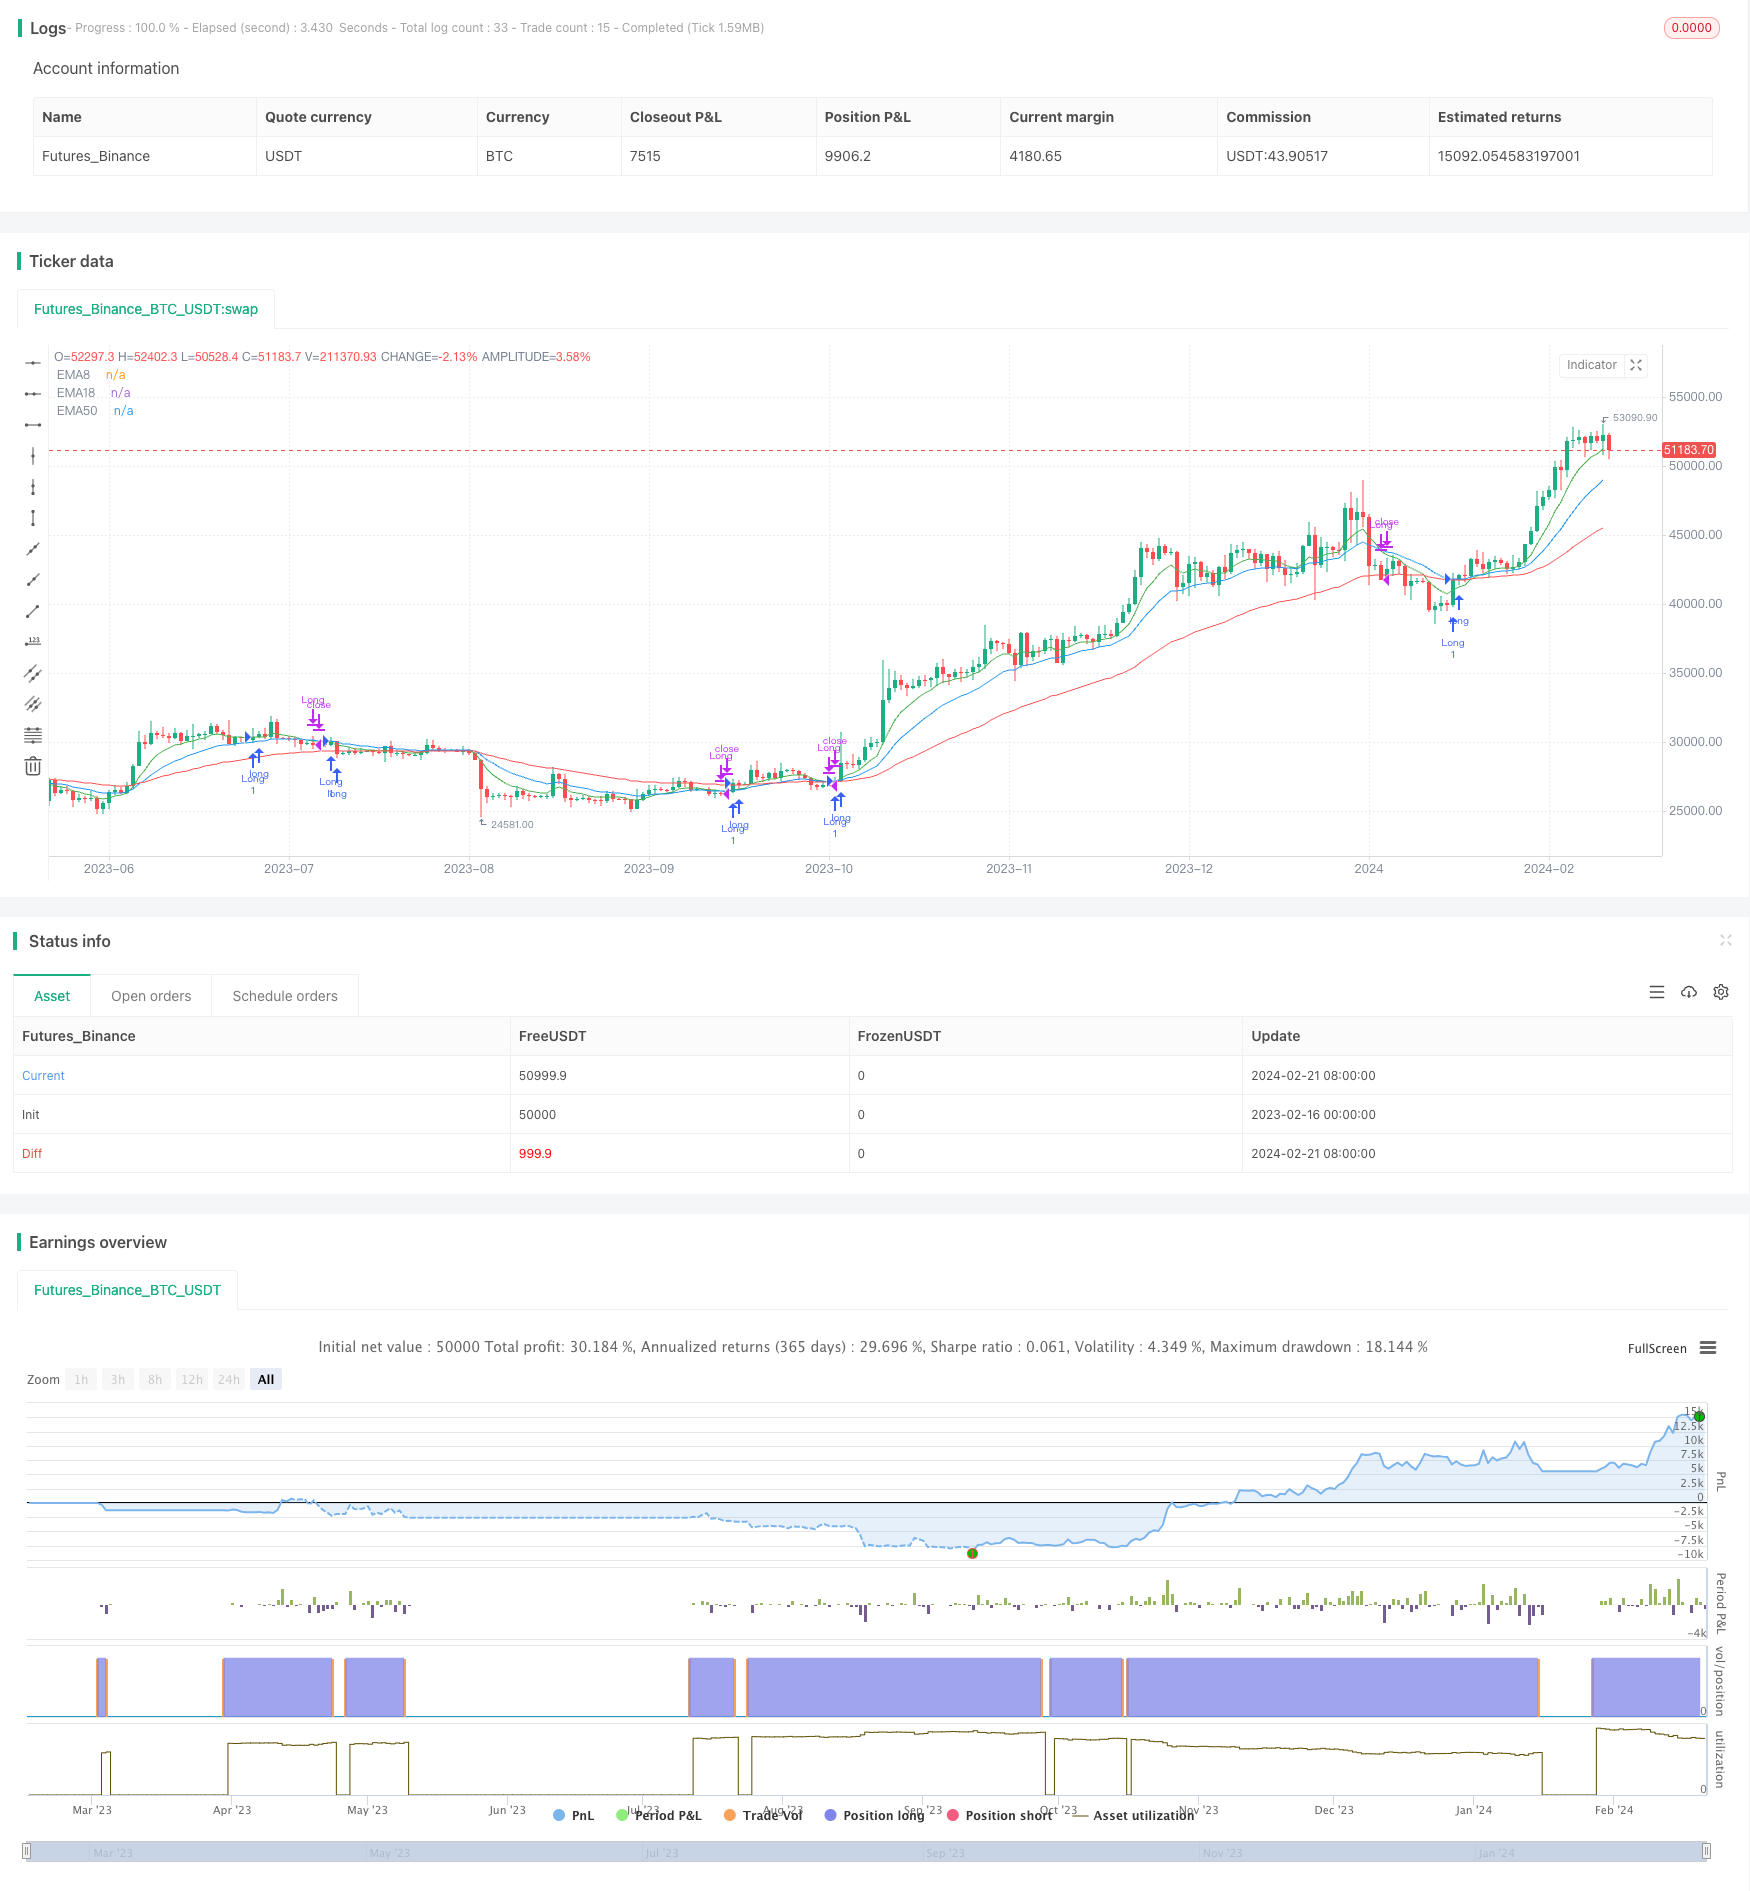
Overview
This strategy generates buy and sell signals based on the crossover of moving averages. It uses 8-day, 18-day and 50-day exponential moving averages (EMA). A buy signal is generated when the price breaks above the 8-day EMA and is higher than the 50-day EMA. A sell signal is generated when the 8-day EMA crosses below the 18-day EMA.
Principle
Moving averages can effectively filter price fluctuations and reflect price trends. Faster moving averages respond quicker to price changes. When the faster moving average crosses above the slower one, it signals an upward trend in prices. And when it crosses below, it signals a downward trend.
This strategy utilizes the crossover of EMAs of different periods to determine changes in price trends and generate trading signals. Specifically, it uses:
- 8-day EMA: fast-moving, to judge short-term trends
- 18-day EMA: medium-speed, to judge medium-term trends
- 50-day EMA: slow-moving, to judge long-term trends
Buy signals are generated when the short-term uptrend (8-day EMA rising) aligns with medium and long-term trends (price higher than 50-day EMA). Sell signals are generated when the short-term uptrend (8-day EMA) is broken by the medium-term downtrend (18-day EMA falling).
Advantage Analysis
The advantages of this strategy are:
- Clear trading signals and simple rules.
- Can effectively identify trend reversal using multi-period EMAs.
- EMAs filter noise and reduce unnecessary trades.
- Good real-time performance to respond to events quickly.
Risk Analysis
There are also some risks:
- EMAs have lag and may miss best timing for reversals.
- Potentially large drawdowns, requiring strict stop loss.
- Parameter setting is subjective, needs adjustment across markets.
- Too frequent signals during high volatility, increasing costs.
Some methods to optimize and mitigate risks:
- Combine other indicators to improve timing and win rate.
- Set stop loss to control downside.
- Test and optimize parameters for different markets.
- Add filters to avoid over-trading.
Optimization Directions
Some directions to further optimize the strategy:
- Optimize EMA periods to find best combinations.
- Add other indicators like RSI to improve entry timing.
- Add stop loss mechanisms like trailing stop loss.
- Combine volume analysis, only consider signals with increasing volume.
- Test robustness across different products, adjust accordingly.
Conclusion
Overall this is a simple and practical strategy, using EMA crosses to determine trend changes. It has good real-time performance but also risks requiring further testing and optimization. With robust enhancements, it can become a stable algorithmic trading strategy.
Source Pine Script
/*backtest
start: 2023-02-16 00:00:00
end: 2024-02-22 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy('Trading EMAs', overlay=true)

// Definir las medias móviles con colores personalizados
ema8 = ta.ema(close, 8)
ema18 = ta.ema(close, 18)
ema50 = ta.ema(close, 50)

plot(ema8, color=color.new(color.green, 0), title='EMA8')
plot(ema18, color=color.new(color.blue, 0), title='EMA18')
plot(ema50, color=color.new(color.red, 0), title='EMA50')

// Condiciones de entrada
longCondition = ta.crossover(close, ema8) and close > ema50 // Señal de compra cuando el precio de cierre cruza al alza la EMA de 8 y el precio está por encima de la EMA de 50

// Condiciones de salida
exitLongCondition = ta.crossunder(ema8, ema18) // Señal de venta cuando EMA8 cruza por debajo de EMA18

// Ejecutar las operaciones basadas en las condiciones de entrada
if longCondition
    strategy.entry('Long', strategy.long)

// Salida de las operaciones basadas en las condiciones de salida
if exitLongCondition
    strategy.close('Long')
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-Trading-Strategy-442628.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover with RSI Trend Confirmation StrategyPine Script · Trend following · 3h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d