Strategy vault / Trend following
Multi EMA Trend Following Strategy with Dynamic Stop Loss
This strategy is a trend following trading system based on multiple Exponential Moving Averages (EMA) and Relative Strength Index (RSI). It combines daily EMA(20,30,200) crossover signals, RSI momentum confirmation…
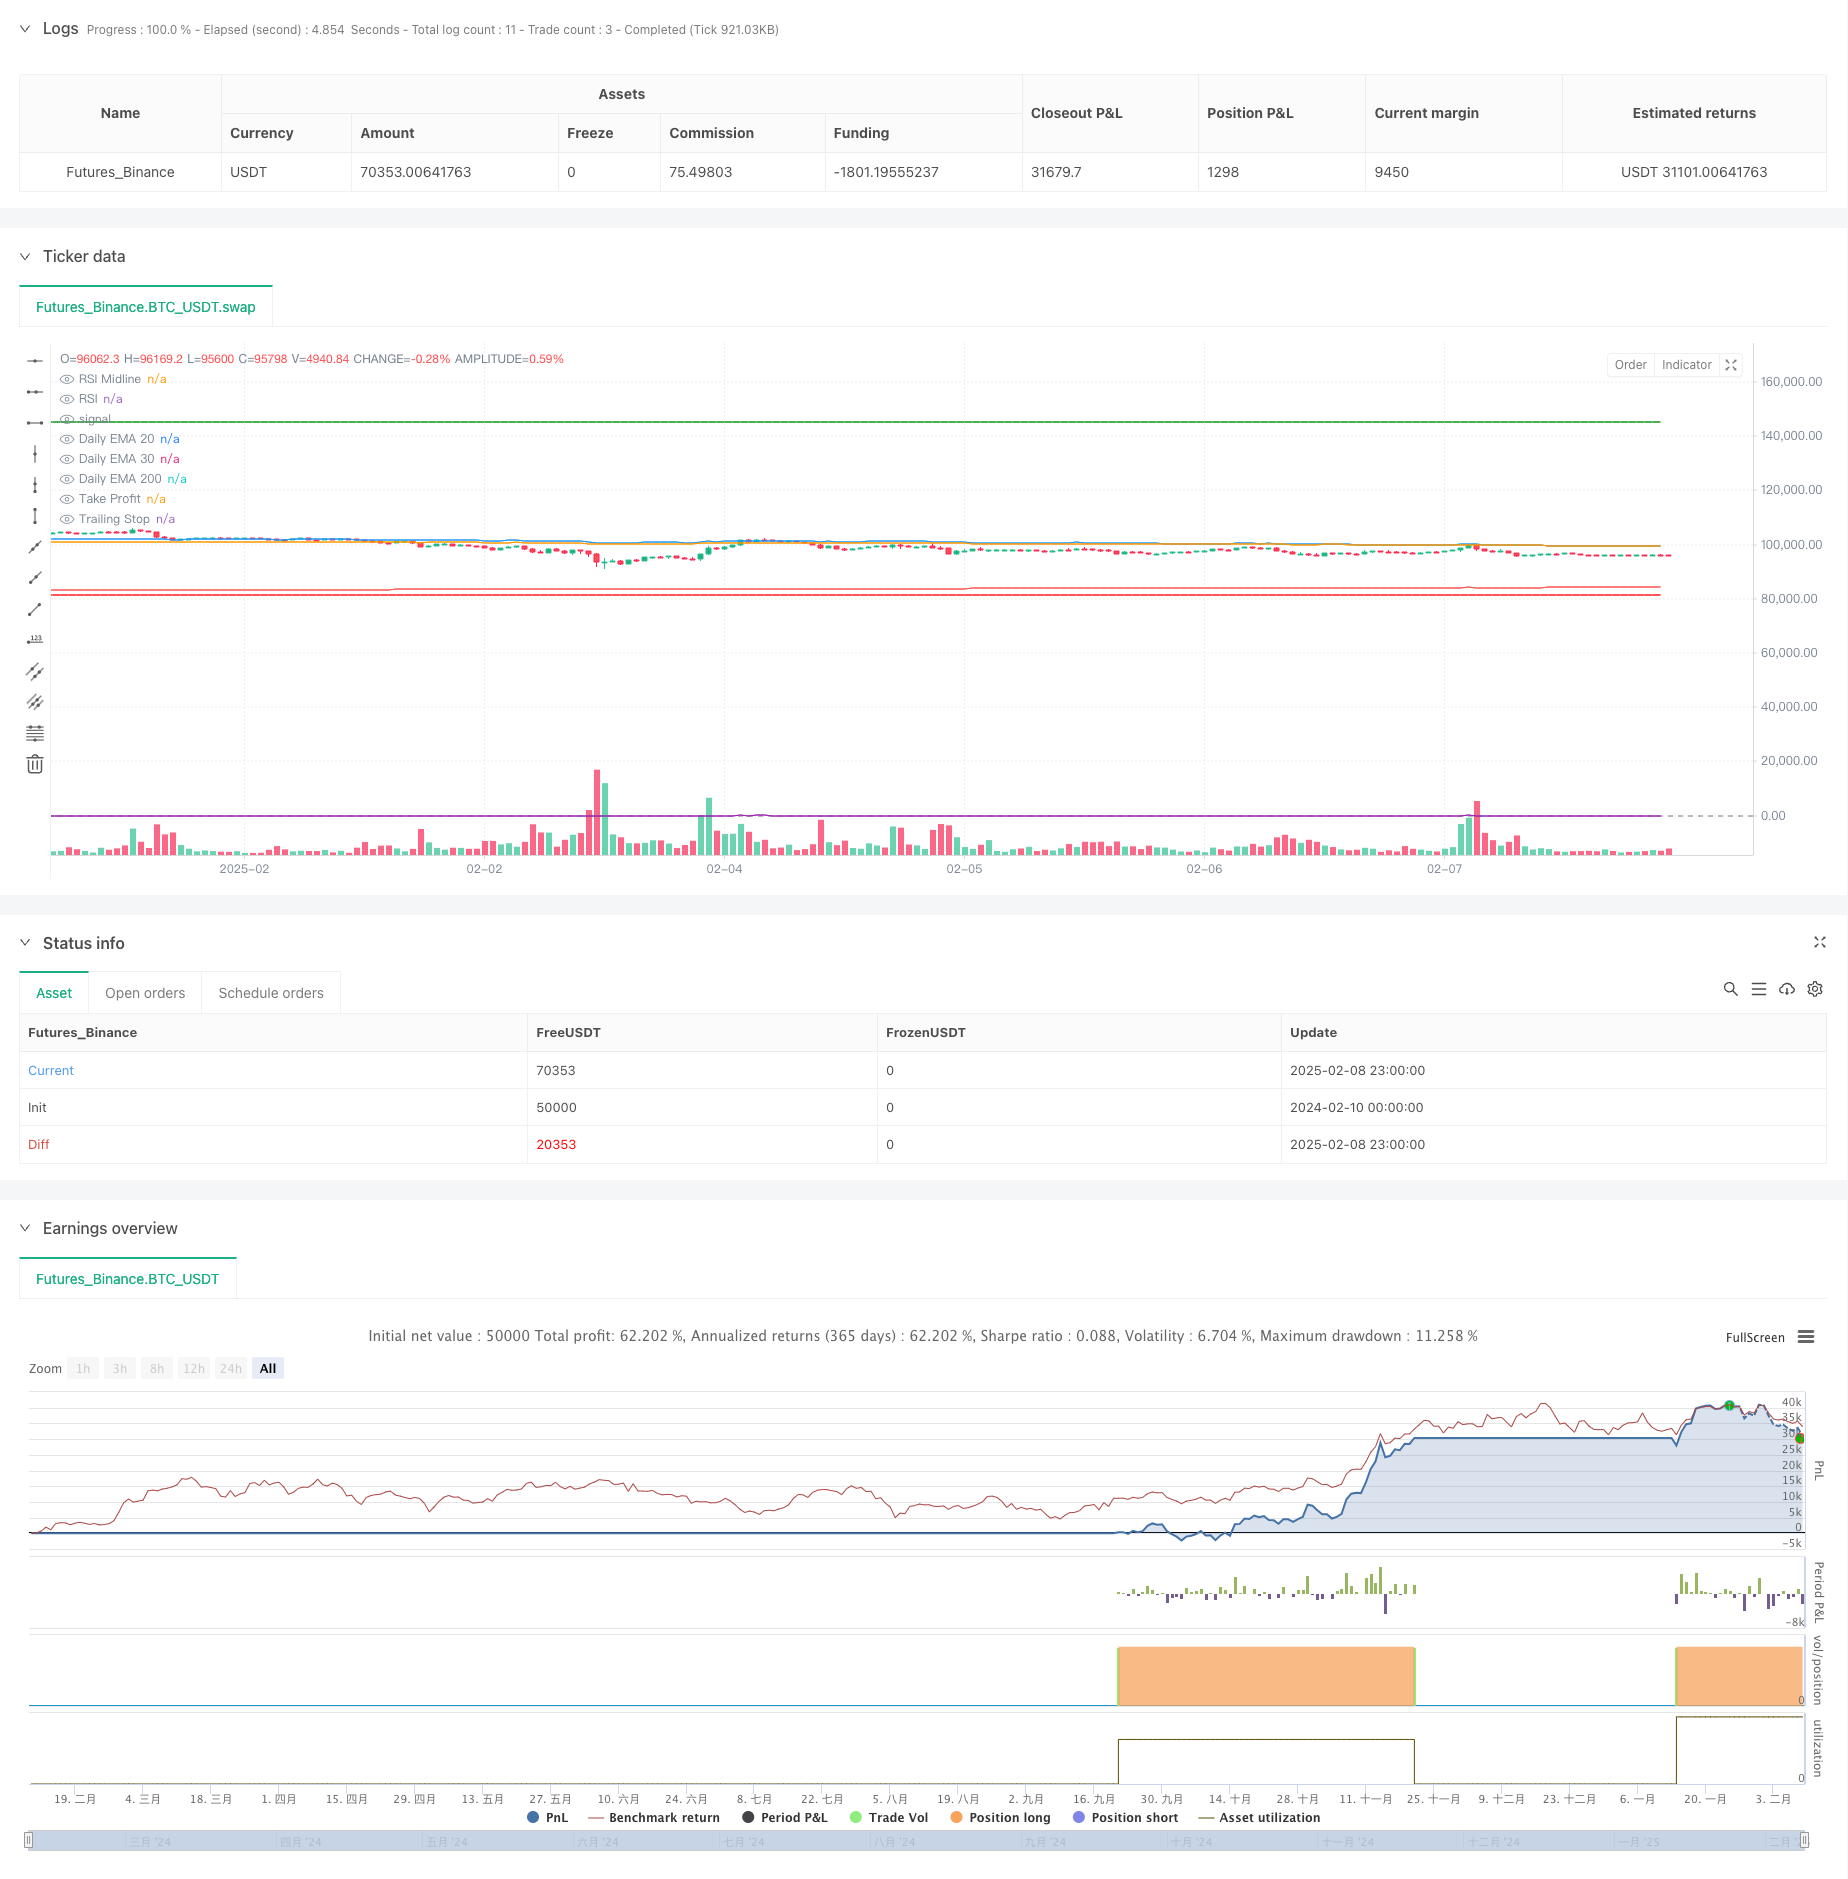
Overview
This strategy is a trend following trading system based on multiple Exponential Moving Averages (EMA) and Relative Strength Index (RSI). It combines daily EMA(20,30,200) crossover signals, RSI momentum confirmation, and dynamic stop-loss mechanism to capture medium to long-term trend opportunities.
Strategy Principles
The core logic includes the following key components:
- Entry Signal: A long position is triggered when the 20-day EMA crosses above the 30-day EMA, price is above the 200-day EMA, and RSI is above 50.
- Take Profit: A fixed 50% take profit level is set upon entry.
- Dynamic Stop Loss: A 25% trailing stop that moves up as price makes new highs.
- Exit Mechanism: Positions are automatically closed when price hits either the take profit or trailing stop levels.
Strategy Advantages
- Multiple Timeframe Validation: Daily EMAs filter out short-term noise and enhance trading stability.
- Dynamic Risk Management: Trailing stop mechanism effectively locks in profits and prevents large drawdowns.
- Comprehensive Trend Confirmation: Combination of RSI and EMA system better confirms trend validity.
- Clear Execution Logic: Entry and exit conditions are well-defined and easy to understand.
Strategy Risks
- Choppy Market Risk: Frequent stop-outs may occur in range-bound markets.
- Slippage Impact: Dynamic stops and take profit levels may face significant slippage in volatile markets.
- False Breakout Risk: EMA crossover signals may generate false breakouts.
- Parameter Sensitivity: Stop loss and take profit percentages significantly impact strategy performance.
Optimization Directions
- Market Environment Filter: Add volatility indicators (like ATR) to assess market conditions and reduce position size or pause trading in choppy markets.
- Dynamic Take Profit: Consider adjusting take profit levels based on market volatility.
- Entry Signal Enhancement: Incorporate volume indicators to complement EMA crossover signals for improved reliability.
- Position Management Improvement: Implement dynamic position sizing based on market risk levels.
Summary
This strategy builds a complete trend following trading system through the synergy of multiple technical indicators. Its main features are the combination of medium to long-term trend identification and dynamic risk control, suitable for trending market environments. Through continuous optimization and refinement, the strategy shows promise for improved performance in real trading conditions.
Source Pine Script
/*backtest
start: 2024-02-10 00:00:00
end: 2025-02-09 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Talbuaia Signal", overlay=true)

// Request EMAs on the daily timeframe
ema20_daily = request.security(syminfo.tickerid, "D", ta.ema(close, 20), lookahead=barmerge.lookahead_on)
ema30_daily = request.security(syminfo.tickerid, "D", ta.ema(close, 30), lookahead=barmerge.lookahead_on)
ema200_daily = request.security(syminfo.tickerid, "D", ta.ema(close, 200), lookahead=barmerge.lookahead_on)

// RSI Calculation
rsi = ta.rsi(close, 14)

// Plot daily EMAs
plot(ema20_daily, color=color.blue, title="Daily EMA 20")
plot(ema30_daily, color=color.orange, title="Daily EMA 30")
plot(ema200_daily, color=color.red, title="Daily EMA 200")

// Plot RSI
hline(50, "RSI Midline", color=color.gray)
plot(rsi, color=color.purple, title="RSI")

// Entry condition: 20 EMA crosses above 30 EMA, price is above 200 EMA, and RSI > 50
bullishEntry = ta.crossover(ema20_daily, ema30_daily) and close > ema200_daily and rsi > 50

// Variables to track entry price, take profit, and trailing stop
var float entryPriceLong = na
var float highestPriceSinceEntry = na
var float takeProfitLevel = na
var float trailingStopLevel = na

// Entry Logic
if bullishEntry
    strategy.entry("Long", strategy.long)
    entryPriceLong := close
    highestPriceSinceEntry := close  // Initialize the highest price since entry
    takeProfitLevel := entryPriceLong * 1.50  // Set take profit at 50% above entry price
    trailingStopLevel := na  // Reset trailing stop
    label.new(bar_index, close, "BUY", style=label.style_label_up, color=color.green, textcolor=color.white)

// Update highest price and trailing stop dynamically
if strategy.position_size > 0
    highestPriceSinceEntry := math.max(highestPriceSinceEntry, close)  // Track the highest price reached
    trailingStopLevel := highestPriceSinceEntry * (1 - 0.25)  // Set trailing stop at 25% below the highest price

// Exit Logic: Take profit or trailing stop
if strategy.position_size > 0 and (close >= takeProfitLevel or close <= trailingStopLevel)
    strategy.close("Long")
    label.new(bar_index, close, "EXIT LONG", style=label.style_label_down, color=color.red, textcolor=color.white)

// Plot trailing stop and take profit levels on the chart
plot(trailingStopLevel, "Trailing Stop", color=color.red, linewidth=2, style=plot.style_line)
plot(takeProfitLevel, "Take Profit", color=color.green, linewidth=2, style=plot.style_line)
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-EMA-Trend-Following-Strategy-with-Dynamic-Stop-Loss.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- Dynamic Multi Timeframe ATR Crossover Strategy Optimizing Trend Following and Risk Management with Flexible ParametersPine Script · Trend following · 1h