RSI and Bollinger Bands Quantitative Trading Strategy
This strategy combines Relative Strength Index (RSI) and Bollinger Bands to identify trading opportunities, belonging to mean reversion strategies in quantitative trading. It buys when RSI is below a threshold and…
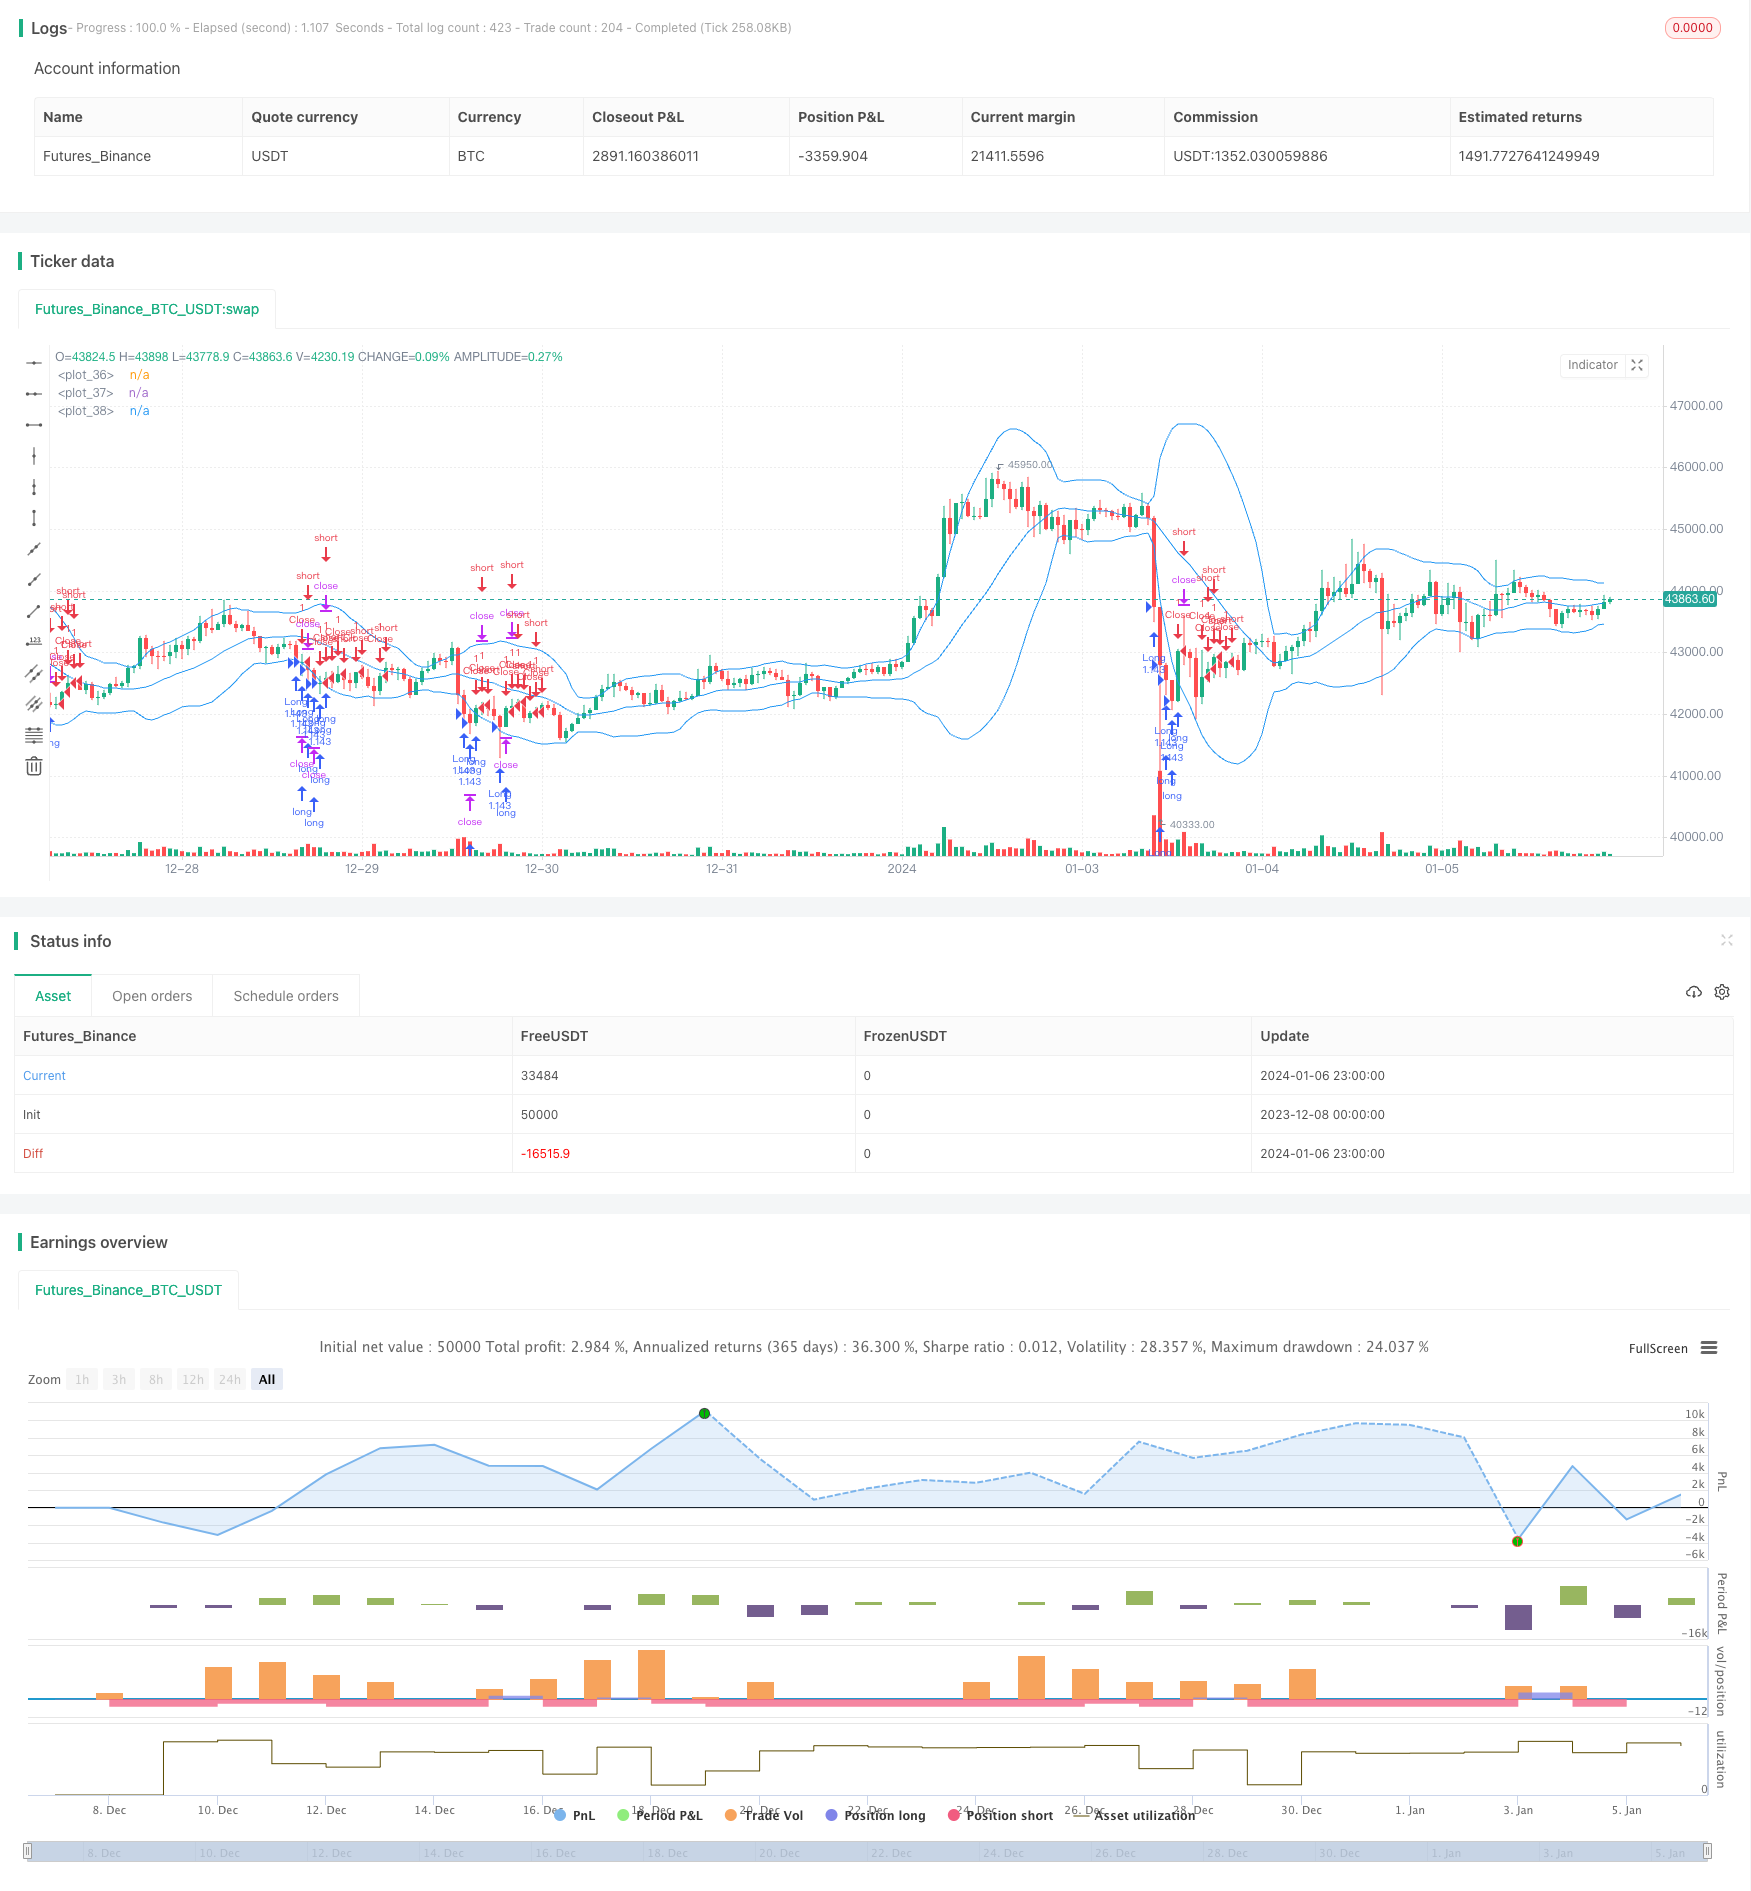
Overview
This strategy combines Relative Strength Index (RSI) and Bollinger Bands to identify trading opportunities, belonging to mean reversion strategies in quantitative trading. It buys when RSI is below a threshold and closes position when price breaks above the middle band of Bollinger Bands. There is no shorting opportunity.
Strategy Logic
Use RSI indicator to judge if the market is oversold. RSI below 30 is considered an oversold signal.
Use Bollinger Bands to determine if price starts rebounding upward. When price bounces from the lower band and breaks above the middle band, the long direction ends.
Combine the RSI oversold signal and Bollinger Bands breakout signal to set buy entry points. Buy when both signals trigger and close position when price breaks above the middle band to take profit.
Advantage Analysis
The strategy combines mean reversion indicator RSI and channel indicator Bollinger Bands to locate entry points more precisely.
The RSI indicator can filter out many false breakouts and reduce unnecessary trades.
The Bollinger Bands acts as a stop loss to control the risk of each trade.
Risk Analysis
RSI indicator may give wrong signals, leading to missing buy opportunities.
Improper parameter settings of Bollinger Bands can result in stop loss being too loose or strict.
Choosing improper trading instruments, such as trading small cap stocks with higher liquidity risk.
Optimization Direction
Test different parameter combinations like RSI period, Bollinger period and multiplier to find optimum parameters.
Incorporate other indicators like KD, MACD to set more strict buy conditions to filter signals.
Set stop loss based on volatility for different trading instruments, such as using volatility stop loss.
Conclusion
This strategy utilizes the logic of buying at RSI lows and selling at Bollinger highs, belonging to mean reversion strategies. Compared to using single indicators like RSI or Bollinger Bands, this strategy can locate entry and exit points more precisely, thus achieving better results. Next steps could be improving through parameter optimization, signal filtering, stop loss strategies etc.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 100 | Lot, % |
| v_input_2 | true | Use RSI |
| v_input_3 | true | Use BB |
| v_input_4 | true | Show BB Overlay |
| v_input_5 | 20 | BB period |
| v_input_6_ohlc4 | 0 | BB source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_7 | 2 | BB Mult |
| v_input_8 | 7 | RSI period |
| v_input_9_close | 0 | RSI source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_10 | 30 | RSI Limit |
| v_input_11 | 1900 | From Year |
| v_input_12 | 2100 | To Year |
| v_input_13 | true | From Month |
| v_input_14 | 12 | To Month |
| v_input_15 | true | From Day |
| v_input_16 | 31 | To Day |
Source Pine Script
/*backtest
start: 2023-12-08 00:00:00
end: 2024-01-07 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018

//@version=3
strategy(title = "Noro's BB + RSI Strategy v1.0", shorttitle = "BB+RSI str 1.0", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 5)

//Settings
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot, %")
rsiuse = input(true, defval = true, title = "Use RSI")
bbuse = input(true, defval = true, title = "Use BB")
showbb = input(true, defval = true, title = "Show BB Overlay")
bbperiod = input(20, defval = 20, minval = 2, maxval = 1000, title = "BB period")
bbsource = input(ohlc4, title = "BB source")
bbmult = input(2, defval = 2, minval = 1, maxval = 100, title = "BB Mult")
rsiperiod = input(7, defval = 7, minval = 2, maxval = 1000, title = "RSI period")
rsisource = input(close, title = "RSI source")
rsilimit = input(30, defval = 30, minval = 1, maxval = 49, title = "RSI Limit")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From Day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To Day")

//RSI
rsi = rsi(rsisource, rsiperiod)

//BB
basis = sma(bbsource, bbperiod)
dev = bbmult * stdev(bbsource, bbperiod)
upper = basis + dev
lower = basis - dev

//Overlay
col = showbb ? blue : na
plot(upper, color = col)
plot(basis, color = col)
plot(lower, color = col)

//Signals
up = (rsi < rsilimit or rsiuse == false) and (low < lower or bbuse == false)
cl = close > open

//Trading
lot = 0.0
lot := strategy.position_size == 0 ? strategy.equity / close * capital / 100 : lot[1]
if up
    strategy.entry("Long", strategy.long, lot)
if cl
    strategy.entry("Close", strategy.short, 0)
if time > timestamp(toyear, tomonth, today, 23, 59)
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-and-Bollinger-Bands-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Multi Indicator Bollinger Bands Trading StrategyPine Script · Breakout · 2h