Strategy vault / Trend following
RSI Moving Average Crossover Trend Strategy
The RSI Moving Average Crossover Trend Strategy is a strategy that uses the moving average crossover signals of the RSI indicator to determine the trend and issue trading signals. The strategy also incorporates the…
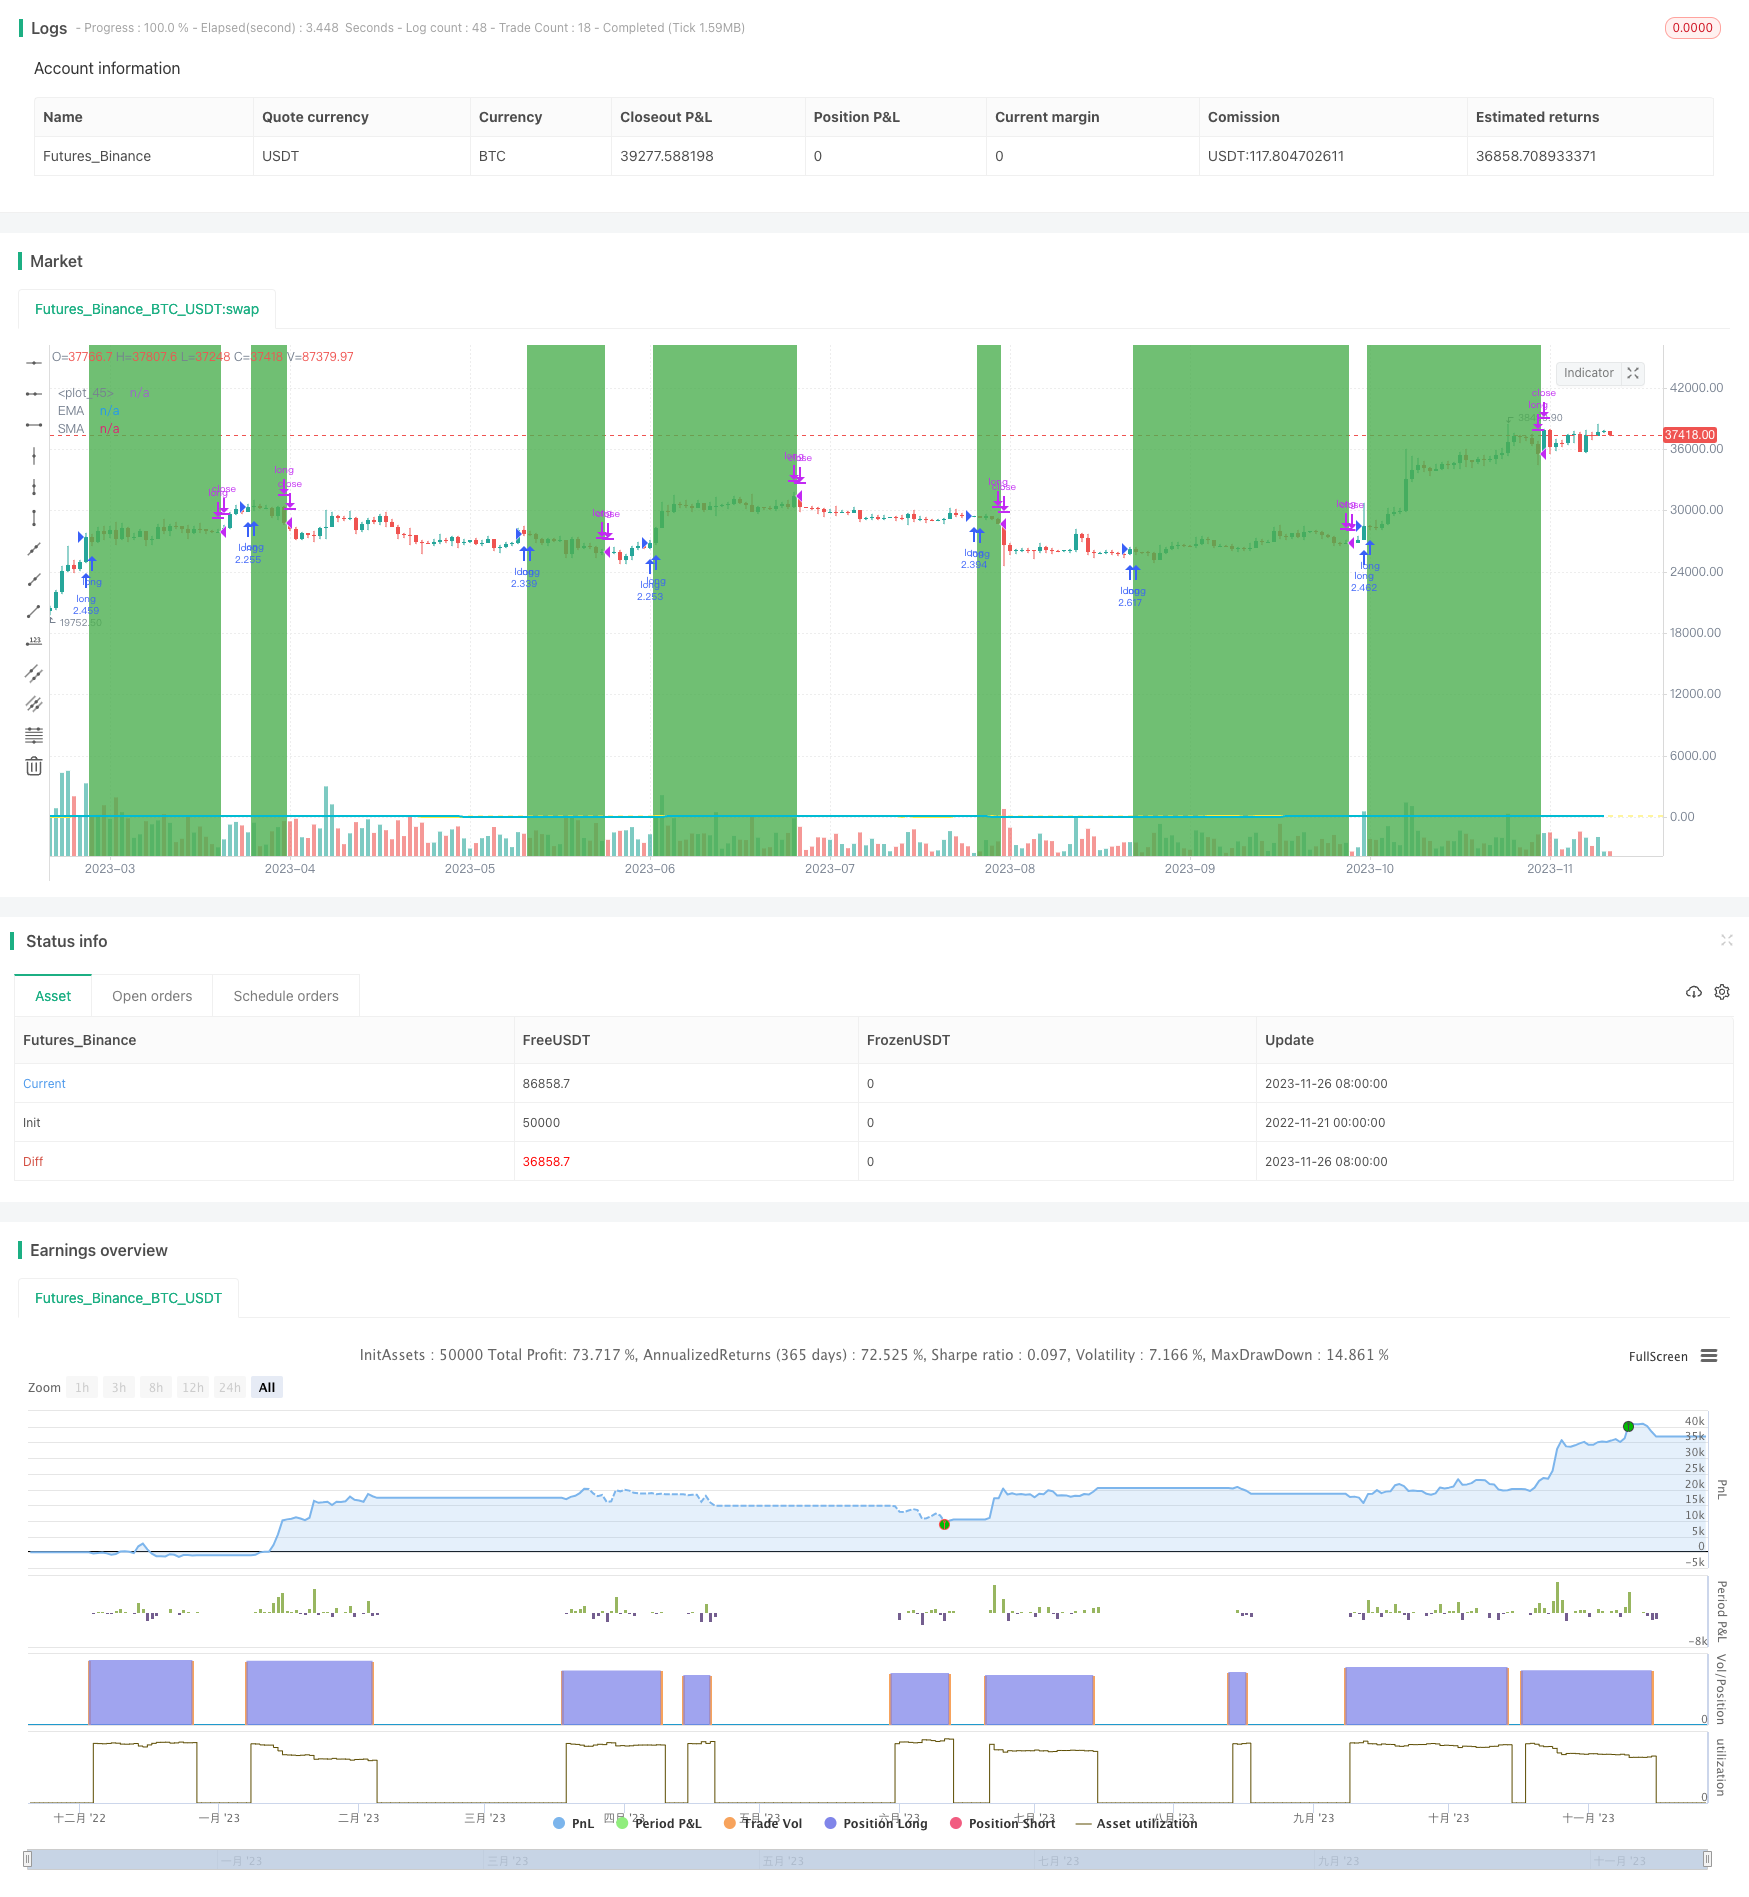
Overview
The RSI Moving Average Crossover Trend Strategy is a strategy that uses the moving average crossover signals of the RSI indicator to determine the trend and issue trading signals. The strategy also incorporates the price EMA, issuing buy signals only when the price is above the EMA.
Strategy Logic
The core indicator of this strategy is RSI. It calculates both the EMA and SMA of the RSI. Buy signals are only issued when the RSI EMA is above the SMA while the price is above the EMA. Sell signals are issued when the RSI EMA falls below the SMA to follow the trend.
The RSI indicator can effectively reflect overbought and oversold conditions in the market. Breaking above 70 on the RSI is regarded as overbought while breaking below 30 is oversold. This strategy utilizes the EMA and SMA to discover trends and turning points of the RSI indicator. The EMA reacts faster to recent price changes while the SMA relies more on older data. The two lines work together.
When the RSI EMA starts picking up, it signals stabilization in the market. The SMA then verifies the direction. When the SMA also starts rising, it confirms the RSI is in an uptrend. The strategy will now issue a buy signal given that the price is above EMA to follow the trend.
Advantage Analysis
This is a trend following strategy, capable of effectively catching directional opportunities over the medium to long term. Compared to single indicators, this strategy uses RSI EMA and SMA crossover for verification, reducing false signals and increasing stability.
The strategy also incorporates the price EMA to ensure buying only in a price uptrend, avoiding the risk of range-bound markets and improving profitability.
Risk Analysis
The strategy relies mainly on the RSI indicator. False RSI signals will lead to false strategy signals. Also, the RSI is more suitable for identifying overbought/oversold levels with some lag in catching mid-long term trends.
There can also be some time lag, especially when the RSI EMA and SMA are more range-bound. This period carries some loss risk before signals are triggered.
Optimization Directions
The RSI can be optimized by selecting more appropriate parameters to enhance effectiveness.
Stop loss logic can be added to exit positions after losses reach certain levels to effectively manage risk.
Parameters can be tested and optimized across different timeframes so that the strategy can run stable on more products and periods.
Summary
The RSI Moving Average Crossover Trend Strategy is a simple trend following strategy using RSI to determine trend direction and crossovers for verification. It incorporates price EMA to buy on uptrends. The strategy has high stability for mid-long term holding but lag risk needs to be managed. Further optimizations can improve strategy performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 5 | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2015 | From Year |
| v_input_4 | true | To Month |
| v_input_5 | true | To Day |
| v_input_6 | 9999 | To Year |
| v_input_7 | 16 | RSILength |
| v_input_8 | 12 | RSI EMA Length |
| v_input_9 | 29 | RSI SMA Length2 |
| v_input_10 | 8 | EMA price Length |
Source Pine Script
/*backtest
start: 2022-11-21 00:00:00
end: 2023-11-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//Created by Sv3nla 5-Jan-2021
strategy(title="Sv3nla RSI EMA SMA Strat", shorttitle="Sv3nla RSI EMA SMA Strat", overlay=true, initial_capital=1000, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// === BACKTEST RANGE ===
FromMonth = input(defval = 5, title = "From Month", minval = 1)
FromDay   = input(defval = 1, title = "From Day", minval = 1)
FromYear  = input(defval = 2015, title = "From Year", minval = 2015)
ToMonth   = input(defval = 1, title = "To Month", minval = 1)
ToDay     = input(defval = 1, title = "To Day", minval = 1)
ToYear    = input(defval = 9999, title = "To Year", minval = 2022)
// syminfo.mintick = 0.01$ for BTCUSDT

testPeriod() => true

//INPUTS
rsilen = input(defval = 16, minval=1, title="RSILength")
RSIemaLen = input(defval = 12, minval=1, title="RSI EMA Length")
RSIsmaLen2 = input(defval = 29, minval=1, title="RSI SMA Length2")
length = input(defval = 8, minval=1, title="EMA price Length")

// RSI
RSIsrc = close
RSIup = rma(max(change(RSIsrc), 0), rsilen)
RSIdown = rma(-min(change(RSIsrc), 0), rsilen)
rsi = RSIdown == 0 ? 100 : RSIup == 0 ? 0 : 100 - 100 / (1 + RSIup / RSIdown)
emavalue=ema(rsi,RSIemaLen)
smavalue=sma(rsi,RSIsmaLen2)

//EMA
ema=ema(close,length)

//PLOT
plot(ema(rsi, RSIemaLen), color=color.yellow, linewidth=2, title="EMA", transp=0)
plot(sma(rsi, RSIsmaLen2), color=color.aqua, linewidth=2, title="SMA", transp=0)

//ORDERS
if (testPeriod())
    strategy.entry("long",strategy.long, comment="RSIEMA", when=(emavalue > smavalue and close>ema))
    strategy.close(id="long", when=(emavalue < smavalue))

// Colour background when in a trade and 50 horizontal line
backgroundColour = (strategy.position_size > 0) ? color.green : na
bgcolor(color=backgroundColour, transp=85)
hline(50, color=color.yellow)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Moving-Average-Crossover-Trend-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- Dynamic Signal Line Trend Following and Volatility Filtering StrategyPine Script · Trend following · 1h
- EMA AROON ASHPine Script · Trend following · 3m