Strategy vault / Trend following
Super Moving Average and Upperband Crossover Strategy
The Super Moving Average and Upperband Crossover Strategy is a quantitative trading strategy based on technical indicators. The strategy utilizes the Exponential Moving Average (EMA) and Upperband indicators to…
Overview
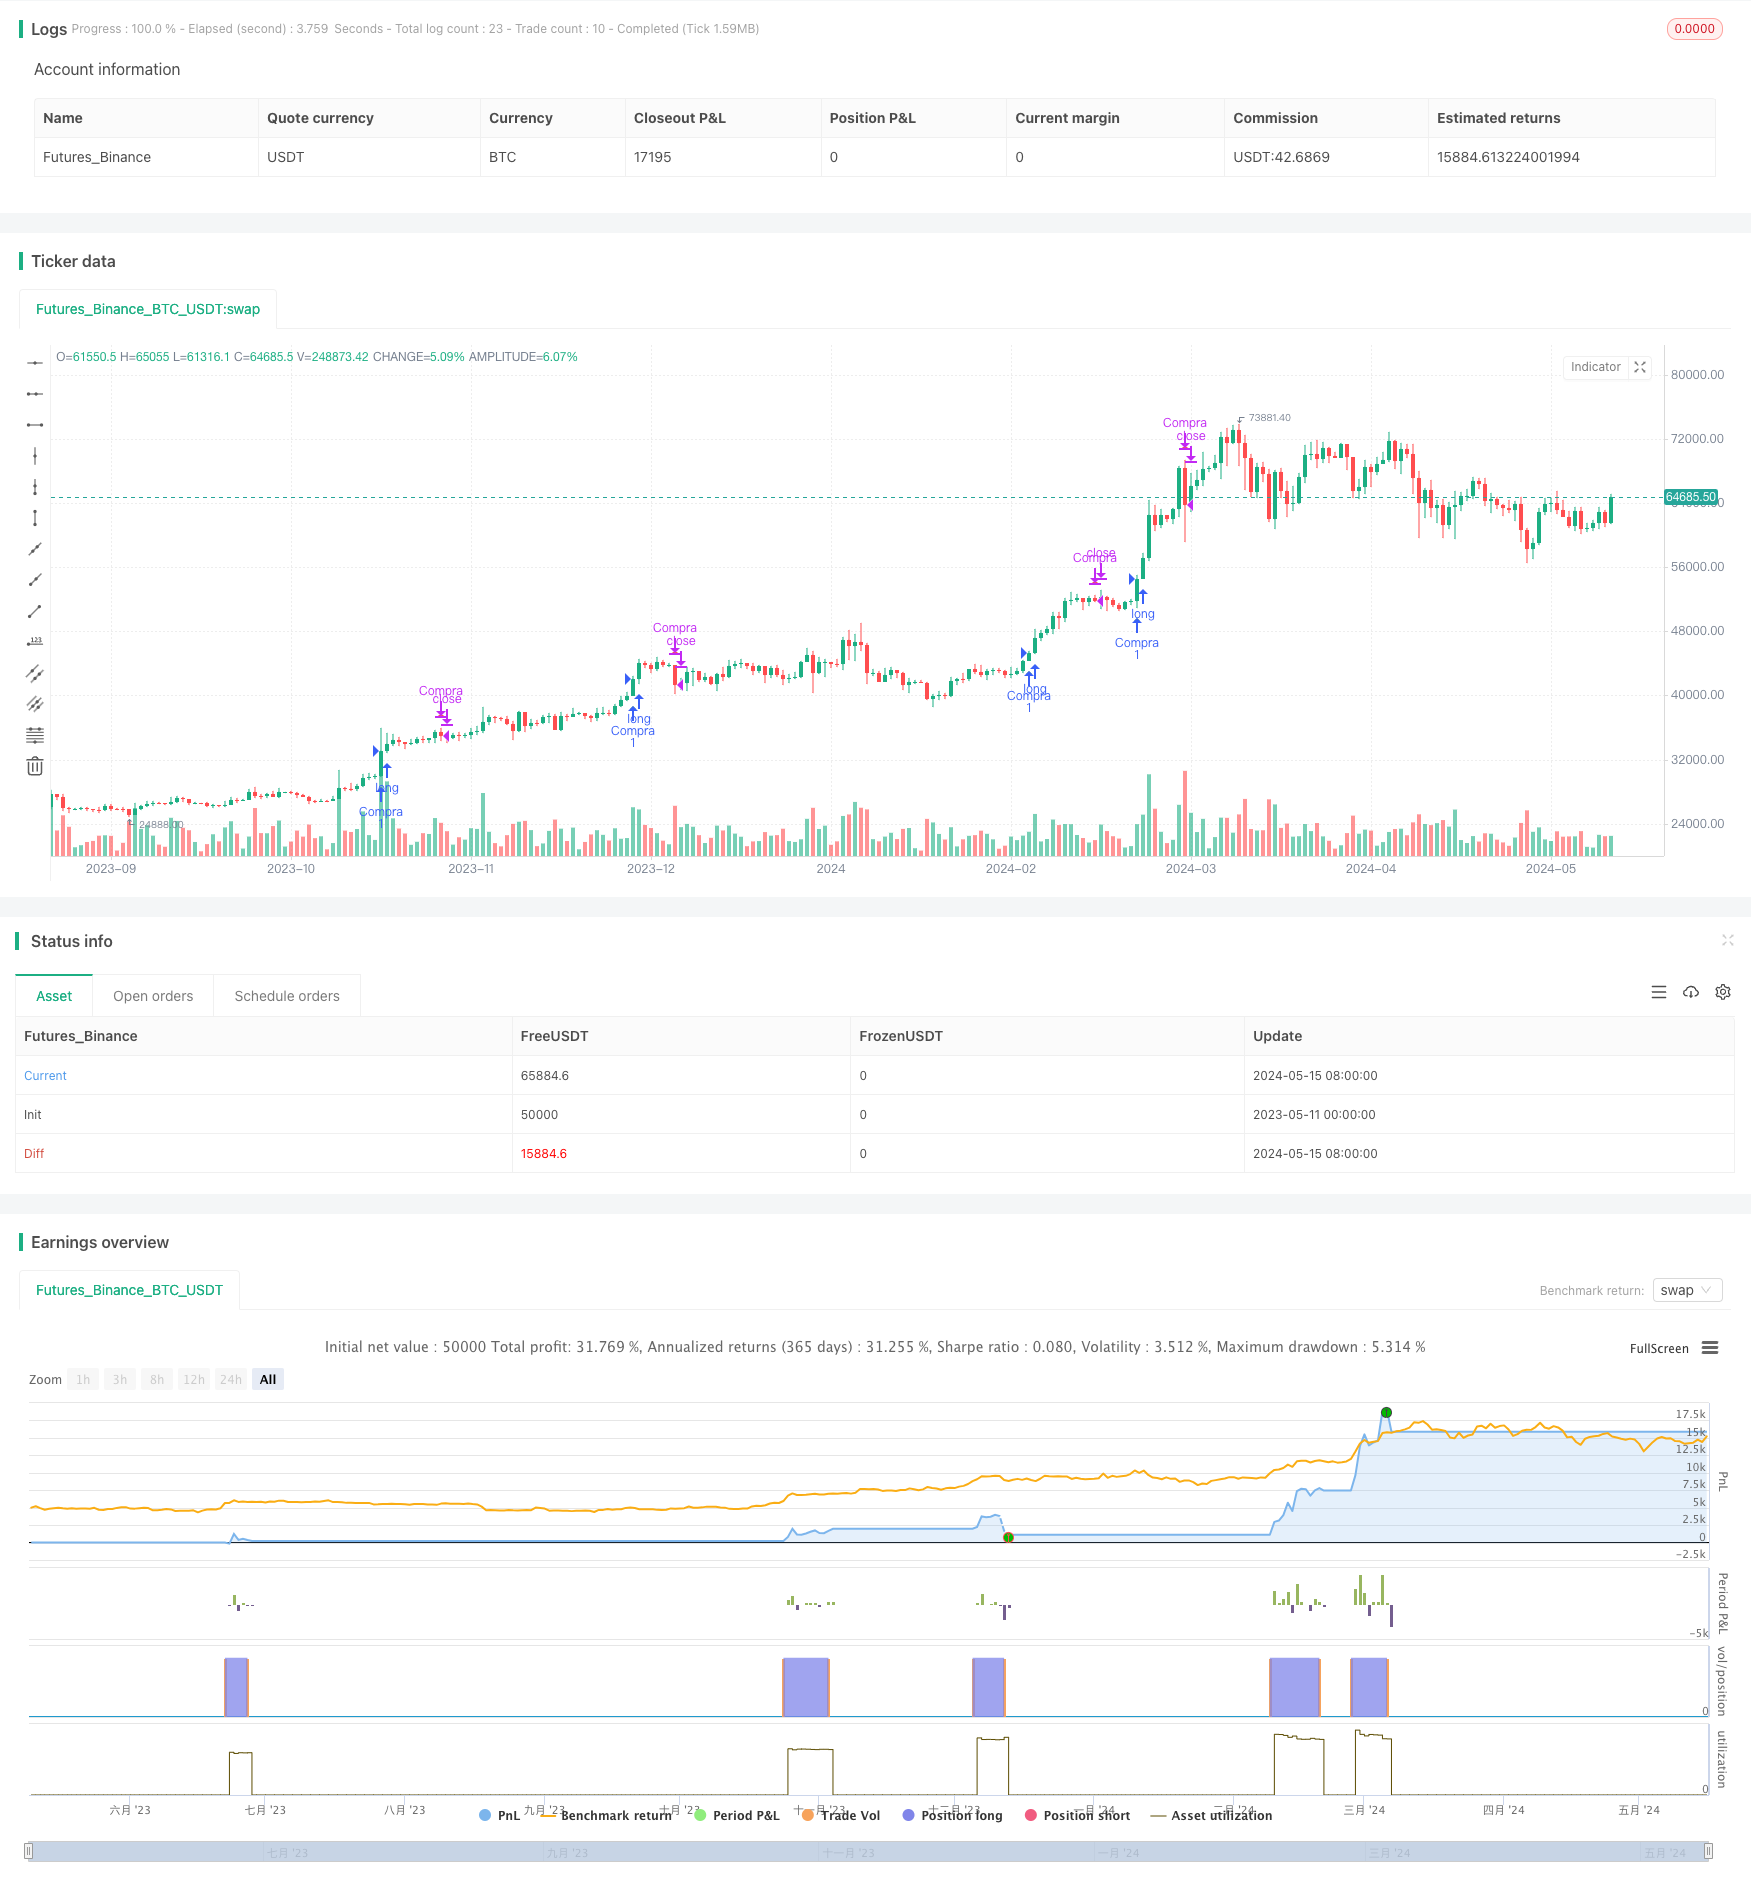
The Super Moving Average and Upperband Crossover Strategy is a quantitative trading strategy based on technical indicators. The strategy utilizes the Exponential Moving Average (EMA) and Upperband indicators to capture upward trends in the market. When the closing price breaks through the Upperband and meets certain conditions, the strategy generates a buy signal. When the closing price falls below the 3-day EMA, the strategy generates a sell signal. This strategy is suitable for markets with high trading volumes and clear trends, such as Bitcoin.
Strategy Principle
The core of this strategy is to use the EMA and Upperband technical indicators to determine market trends and timing for buying and selling. First, the strategy calculates the Upperband indicator, which takes into account price volatility. When the price deviation from the average price is large, the value of the Upperband will increase accordingly. Then, the strategy determines whether the closing price has broken through the moving average of the Upperband and whether it meets other buying conditions. If so, it generates a buy signal. After holding a position, when the closing price falls below the 3-day EMA, the strategy generates a sell signal.
Strategy Advantages
Suitable for markets with strong trends: This strategy performs well in upward trends and is especially suitable for instruments with high volatility and clear trends, such as Bitcoin.
Combines price and volatility: The Upperband indicator comprehensively considers price levels and price volatility, and can more fully reflect market conditions.
Simple and easy to use: The strategy logic is clear, and the indicators used are simple and easy to understand and implement.
Suitable for short-term trading: The strategy generates buy and sell signals frequently, making it suitable for short-term trading.
Strategy Risks
Oscillating market risk: In a highly volatile and trendless oscillating market, the strategy may trade frequently, resulting in large slippage and transaction costs.
Indicator parameter risk: The strategy is sensitive to indicator parameters, and improper parameter settings may lead to poor strategy performance.
Overfitting risk: The strategy performs well in specific markets but may not be able to adapt to changes in market conditions, leading to overfitting risk.
Strategy Optimization Directions
Introduce trend confirmation indicators: Trend confirmation indicators such as MACD can be introduced to filter out false signals in oscillating markets.
Optimize parameter selection: Optimal indicator parameter combinations can be found through optimization methods such as genetic algorithms.
Add risk control module: Risk control measures such as stop-loss and dynamic position management can be introduced to reduce strategy risk.
Multi-variety adaptation: Machine learning and other methods can be used to make the strategy adaptable to different varieties and market environments.
Summary
The Super Moving Average and Upperband Crossover Strategy is a simple and practical quantitative trading strategy suitable for markets with strong trends. The strategy uses EMA and Upperband indicators to capture upward trends, and its logic is clear and easy to implement. However, the strategy also has certain risks, such as oscillating market risk, parameter risk, and overfitting risk. In the future, the strategy can be optimized in terms of trend confirmation, parameter optimization, risk control, and multi-variety adaptation to improve the strategy's robustness and adaptability.
Source Pine Script
/*backtest
start: 2023-05-11 00:00:00
end: 2024-05-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Estratégia de Cruzamento de Bandas", overlay=true)

// Entradas
factor = input(0.001, title="Factor")
length = input(20, title="Length")

// Cálculo da Upperband
Upperband = high * (1 + 2 * ((((high - low) / ((high + low) / 2)) * 1000) * factor))

// Condição de Compra
buy_condition = close > ta.ema(close, 3)

// Variável para controlar se a compra foi feita
var bought = false

// Sinal de compra
buy_signal = (close[1] <= ta.sma(Upperband, length)[1]) and (close > ta.sma(Upperband, length)) and buy_condition

// Sinal de venda
sell_signal = close < ta.ema(close, 3) and bought

// Atualizar o status de compra
if buy_signal
    bought := true
    strategy.entry("Compra", strategy.long)
else if sell_signal
    bought := false
    strategy.close("Compra")

// Plotagem dos sinais de compra e venda no gráfico
plotshape(series=buy_signal, title="Compra", color=color.green, style=shape.triangleup, location=location.belowbar)
plotshape(series=sell_signal, title="Venda", color=color.red, style=shape.triangledown, location=location.abovebar)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-05-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Super-Moving-Average-and-Upperband-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d