Strategy vault / Trend following
Super Trend Tracking Stop Loss Strategy
This strategy opens and closes positions based on the Super Trend indicator and trailing stop loss. It uses 4 alerts to open and close long and short positions, and adopts a super trend strategy. The strategy is…
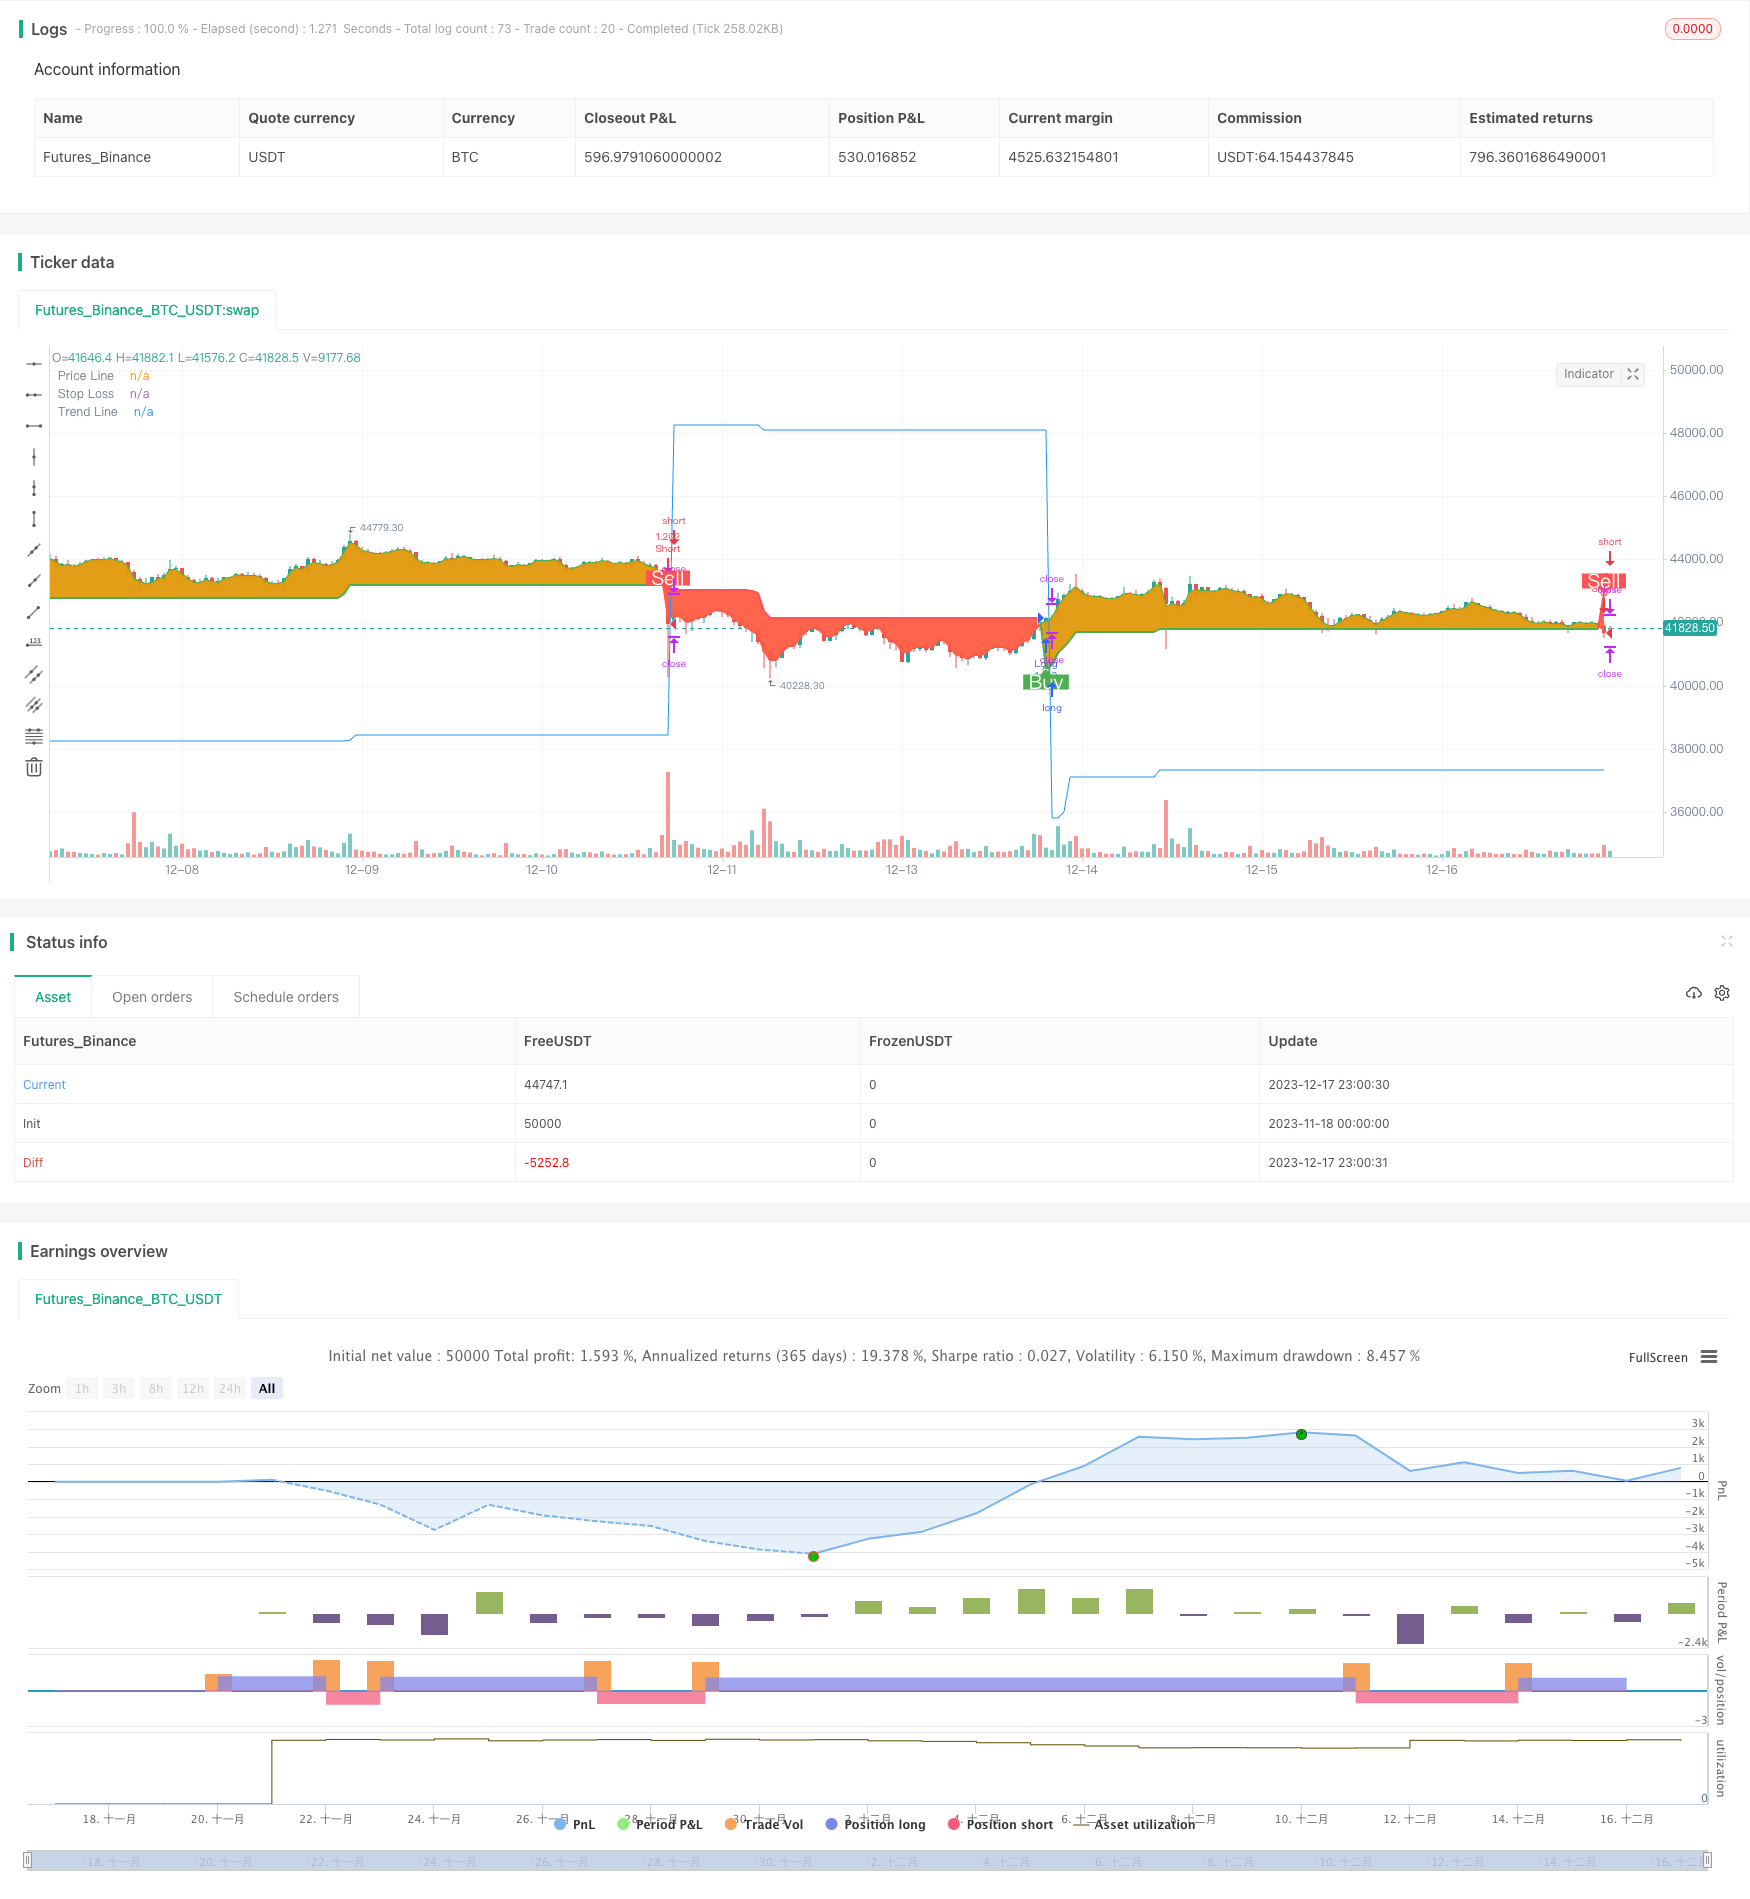
Overview
This strategy opens and closes positions based on the Super Trend indicator and trailing stop loss. It uses 4 alerts to open and close long and short positions, and adopts a super trend strategy. The strategy is designed specifically for robots with trailing stop loss functionality.
Strategy Logic
The strategy uses the ATR indicator to calculate the upper and lower bands. A buy signal is generated when the closing price breaks through the upper band, and a sell signal is generated when it breaks through the lower band. The strategy also uses a super trend line to determine the trend direction. When the super trend line goes up, it indicates the start of a bull market. When it goes down, it indicates the start of a bear market. The strategy opens positions when a signal is generated, and sets the initial stop loss price. It then adjusts the stop loss price based on price changes to lock in profits and achieve a trailing stop loss effect.
Advantage Analysis
The strategy combines the advantages of the Super Trend indicator for determining trend direction and the ATR indicator for setting stops. It can effectively filter out false breakouts. Trailing stops can lock in profits very well and reduce drawdowns. In addition, the strategy is designed specifically for robots, enabling automated trading.
Risk Analysis
The Super Trend indicator can easily generate more false signals. When the stop loss adjustment range is large, the probability of stop loss being hit increases. In addition, robot trading also faces technical risks such as server crashes and network interruptions.
To reduce the probability of false signals, the ATR parameters can be adjusted appropriately or other indicators can be added for filtration. When adjusting the trailing stop range, profit and risk need to be balanced. At the same time, prepare backup servers and networks to hedge against technical failure risks.
Optimization Directions
The following are some directions in which this strategy can be optimized:
Add indicators or conditions to filter entry signals and avoid false signals. For example, the MACD indicator can be added.
Test different ATR parameter combinations to find the optimal parameters.
Optimize the trailing stop loss range to find the best balance point.
Add more stop loss prices to achieve batch stopping of losses.
Build a dual-server architecture with primary and standby servers that can quickly switch when the main server fails.
Conclusion
This strategy integrates the advantages of the Super Trend indicator and trailing stop loss for automated opening and stopping of losses. Combined with the improvement measures in the optimization directions during live trading, it can become a very practical quantitative trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_5 | true | From Month |
| v_input_int_6 | true | From Day |
| v_input_int_7 | 2019 | From Year |
| v_input_int_8 | true | To Month |
| v_input_int_9 | true | To Day |
| v_input_int_10 | 9999 | To Year |
| v_input_float_1 | 4.5 | (?ATR)ATR Factor |
| v_input_int_1 | 59 | ATR Period |
| v_input_1 | true | (?stop loss)trailing stop ? |
| v_input_float_2 | 15 | trailing stop % |
| v_input_2 | true | (?take profit)Take profit1 On/Off ? |
| v_input_float_3 | 5 | TP1 % |
| v_input_int_2 | 10 | TP1 Amount % |
| v_input_3 | true | Take profit2 On/Off ? |
| v_input_float_4 | 10 | TP2 % |
| v_input_int_3 | 15 | TP2 Amount % |
| v_input_4 | true | Take profit3 On/Off ? |
| v_input_float_5 | 15 | TP3 % |
| v_input_int_4 | 20 | TP3 Amount % |
| v_input_5 | long | (?Alert Messages)Long Alert Message |
| v_input_6 | long | Long close Alert Message |
| v_input_7 | short | Short Alert Message |
| v_input_8 | short | Short close Alert Message |
Source Pine Script
/*backtest
start: 2023-11-18 00:00:00
end: 2023-12-18 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © arminomid1375
//@version=5
strategy('Mizar_BOT_super trend', overlay=true, default_qty_value=100, currency=currency.USD, default_qty_type=strategy.percent_of_equity, initial_capital=100, max_bars_back=4000)


//===== INPUTS ==========================================================================//

factor = input.float(4.5, title='ATR Factor', step=0.1,group = 'ATR')
period = input.int(59, minval=1, maxval=100, title='ATR Period',group = 'ATR')
up = (high + low) / 2 - factor * ta.atr(period)
down = (high + low) / 2 + factor * ta.atr(period)
trend_up = 0.0
trend_up := close[1] > trend_up[1] ? math.max(up, trend_up[1]) : up
trend_down = 0.0
trend_down := close[1] < trend_down[1] ? math.min(down, trend_down[1]) : down
trend = 0.0
trend := close > trend_down[1] ? 1 : close < trend_up[1] ? -1 : nz(trend[1], 1)
tsl = trend == 1 ? trend_up : trend_down
line_color = trend == 1 ? 'green' : 'red'
long_signal = trend == 1 and trend[1] == -1
short_signal = trend == -1 and trend[1] == 1
background = true


//ss =  input.float(defval=15.0, minval=0.0, title=' stop loss %',group = 'stop loss')
use_sl = input(title='trailing stop ?', defval=true,group = 'stop loss')
initial_sl_pct = input.float(defval=15.0, minval=0.0, title='trailing stop %',group = 'stop loss')

Tpactive1 = input(title='Take profit1 On/Off ?', defval=true, group='take profit')
tp1percent = input.float(5.0, title='TP1 %', group='take profit') *100
tp1amt = input.int(10, title='TP1 Amount %', group='take profit')
Tpactive2 = input(title='Take profit2 On/Off ?', defval=true, group='take profit')
tp2percent = input.float(10, title='TP2 %', group='take profit') *100
tp2amt = input.int(15, title='TP2 Amount %', group='take profit')
Tpactive3 = input(title='Take profit3 On/Off ?', defval=true, group='take profit')
tp3percent = input.float(15, title='TP3 %', group='take profit')*100
tp3amt = input.int(20, title='TP3 Amount %', group='take profit')

//===== TIMEFRAME ==========================================================================//

from_month = input.int(defval=1, title='From Month', minval=1, maxval=12)
from_day = input.int(defval=1, title='From Day', minval=1, maxval=31)
from_year = input.int(defval=2019, title='From Year', minval=2017)
to_month = input.int(defval=1, title='To Month', minval=1, maxval=12)
to_day = input.int(defval=1, title='To Day', minval=1, maxval=31)
to_year = input.int(defval=9999, title='To Year', minval=2017)
start = timestamp(from_year, from_month, from_day, 00, 00)

finish = timestamp(to_year, to_month, to_day, 23, 59)
window() =>
    time >= start and time <= finish ? true : false

//===== PLOTS ==========================================================================//

// Line
line_plot = plot(tsl, color=trend == 1 ? color.green : color.red, linewidth=2, title='Trend Line')
// Labels
plotshape(long_signal and window() ? up : na, title='Buy', text='Buy', location=location.absolute, style=shape.labelup, size=size.normal, color=color.new(color.green, 0), textcolor=color.new(color.white, 0))
plotshape(short_signal and window() ? down : na, title='Sell', text='Sell', location=location.absolute, style=shape.labeldown, size=size.normal, color=color.new(color.red, 0), textcolor=color.new(color.white, 0))
// Circles
plotshape(long_signal and window() ? up : na, title='Uptrend starts', location=location.absolute, style=shape.circle, size=size.tiny, color=color.new(color.green, 0))
plotshape(short_signal and window() ? down : na, title='Downtrend starts', location=location.absolute, style=shape.circle, size=size.tiny, color=color.new(color.red, 0))
// Background
long_fill = background ? trend == 1 ? color.green : na : na
short_fill = background ? trend == -1 ? color.red : na : na
candle_plot = plot(ohlc4, title='Price Line', color=trend == 1 ? long_fill : short_fill, linewidth=2, transp=90)
fill(candle_plot, line_plot, title='Long Background', color=long_fill, transp=90)
fill(candle_plot, line_plot, title='Short Background', color=short_fill, transp=90)

//===== GLOBAL ==========================================================================//

var entry_price = 0.0
var updated_entry_price = 0.0
var sl_price = 0.0

longString = "Input your custom alert message here.\nAnd put {{strategy.order.alert_message}} in the message box."
longclose = "Input your custom alert message here.\nAnd put {{strategy.order.alert_message}} in the message box."
shortString = "Input your custom alert message here.\nAnd put {{strategy.order.alert_message}} in the message box."
shortclose = "Input your custom alert message here.\nAnd put {{strategy.order.alert_message}} in the message box."


longAlertMessage = input(title="Long Alert Message", defval="long", group="Alert Messages", tooltip=longString)
longcloseAlertMessage = input(title="Long close Alert Message", defval="long", group="Alert Messages", tooltip=longclose)
shortAlertMessage = input(title="Short Alert Message", defval="short", group="Alert Messages", tooltip=shortString)
shortcloseAlertMessage = input(title="Short close Alert Message", defval="short", group="Alert Messages", tooltip=shortclose)


has_open_trade() =>
    strategy.position_size != 0
has_no_open_trade() =>
    strategy.position_size == 0

is_long() =>
    strategy.position_size > 0 ? true : false
is_short() =>
    strategy.position_size < 0 ? true : false

plot(use_sl ? has_no_open_trade() ? close : sl_price : na, color=has_no_open_trade() ? na : color.blue, title='Stop Loss')

strategy_close() =>
    if is_long()
        strategy.close('Long')
        alert(longcloseAlertMessage)
    if is_short()
        strategy.close('Short')
        alert(shortcloseAlertMessage)


strategy_long() =>
    strategy.entry('Long', strategy.long)


strategy_short() =>
    strategy.entry('Short', strategy.short)

sl_pct = initial_sl_pct
if long_signal or is_long() and not(short_signal or is_short())
    sl_pct := initial_sl_pct * -1
    sl_pct

//===== STRATEGY ==========================================================================//


crossed_sl = false
if is_long() and use_sl
    crossed_sl := close <= sl_price
    crossed_sl
if is_short() and use_sl
    crossed_sl := close >= sl_price
    crossed_sl

terminate_operation = window() and has_open_trade() and crossed_sl

if terminate_operation and not(long_signal or short_signal)  // Do not close position if trend is flipping anyways.
    entry_price := 0.0
    updated_entry_price := entry_price
    sl_price := 0.0
    strategy_close()


start_operation = window() and (long_signal or short_signal)

if start_operation
    entry_price := close
    updated_entry_price := entry_price
    sl_price := entry_price + entry_price * sl_pct / 100
    if long_signal
        strategy_long()
        if Tpactive1==true
            strategy.exit('TPL1','Long', qty_percent=tp1amt,profit =tp1percent)

        alert(shortcloseAlertMessage)
        alert(longAlertMessage)


    if short_signal
        strategy_short()
        if Tpactive1==true
            strategy.exit('TPL1','Short', qty_percent=tp1amt,profit =tp1percent)

        alert(longcloseAlertMessage)
        alert(shortAlertMessage)


//===== TRAILING ==========================================================================//

if is_long() and use_sl
    strategy_pct = (close - updated_entry_price) / updated_entry_price * 100.00
    if strategy_pct > 1
        sl_pct += strategy_pct - 1.0
        new_sl_price = updated_entry_price + updated_entry_price * sl_pct / 100
        sl_price := math.max(sl_price, new_sl_price)
        updated_entry_price := sl_price
        updated_entry_price


if is_short() and use_sl
    strategy_pct = (close - updated_entry_price) / updated_entry_price * 100.00
    if strategy_pct < -1
        sl_pct += strategy_pct + 1.0
        new_sl_price = updated_entry_price + updated_entry_price * sl_pct / 100
        sl_price := math.min(sl_price, new_sl_price)
        updated_entry_price := sl_price
        updated_entry_price
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Super-Trend-Tracking-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Indicator Dynamic Trend Trading Strategy Multi dimensional Technical Analysis System Based on RSI and MACDPine Script · Trend following
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h