Strategy vault / Trend following
Trend Trading Strategy Based on Dynamic Moving Average
This strategy generates trading signals based on the dynamic moving average to go long when stock prices rise and close positions when prices fall. By combining the advantages of momentum indicators and moving…
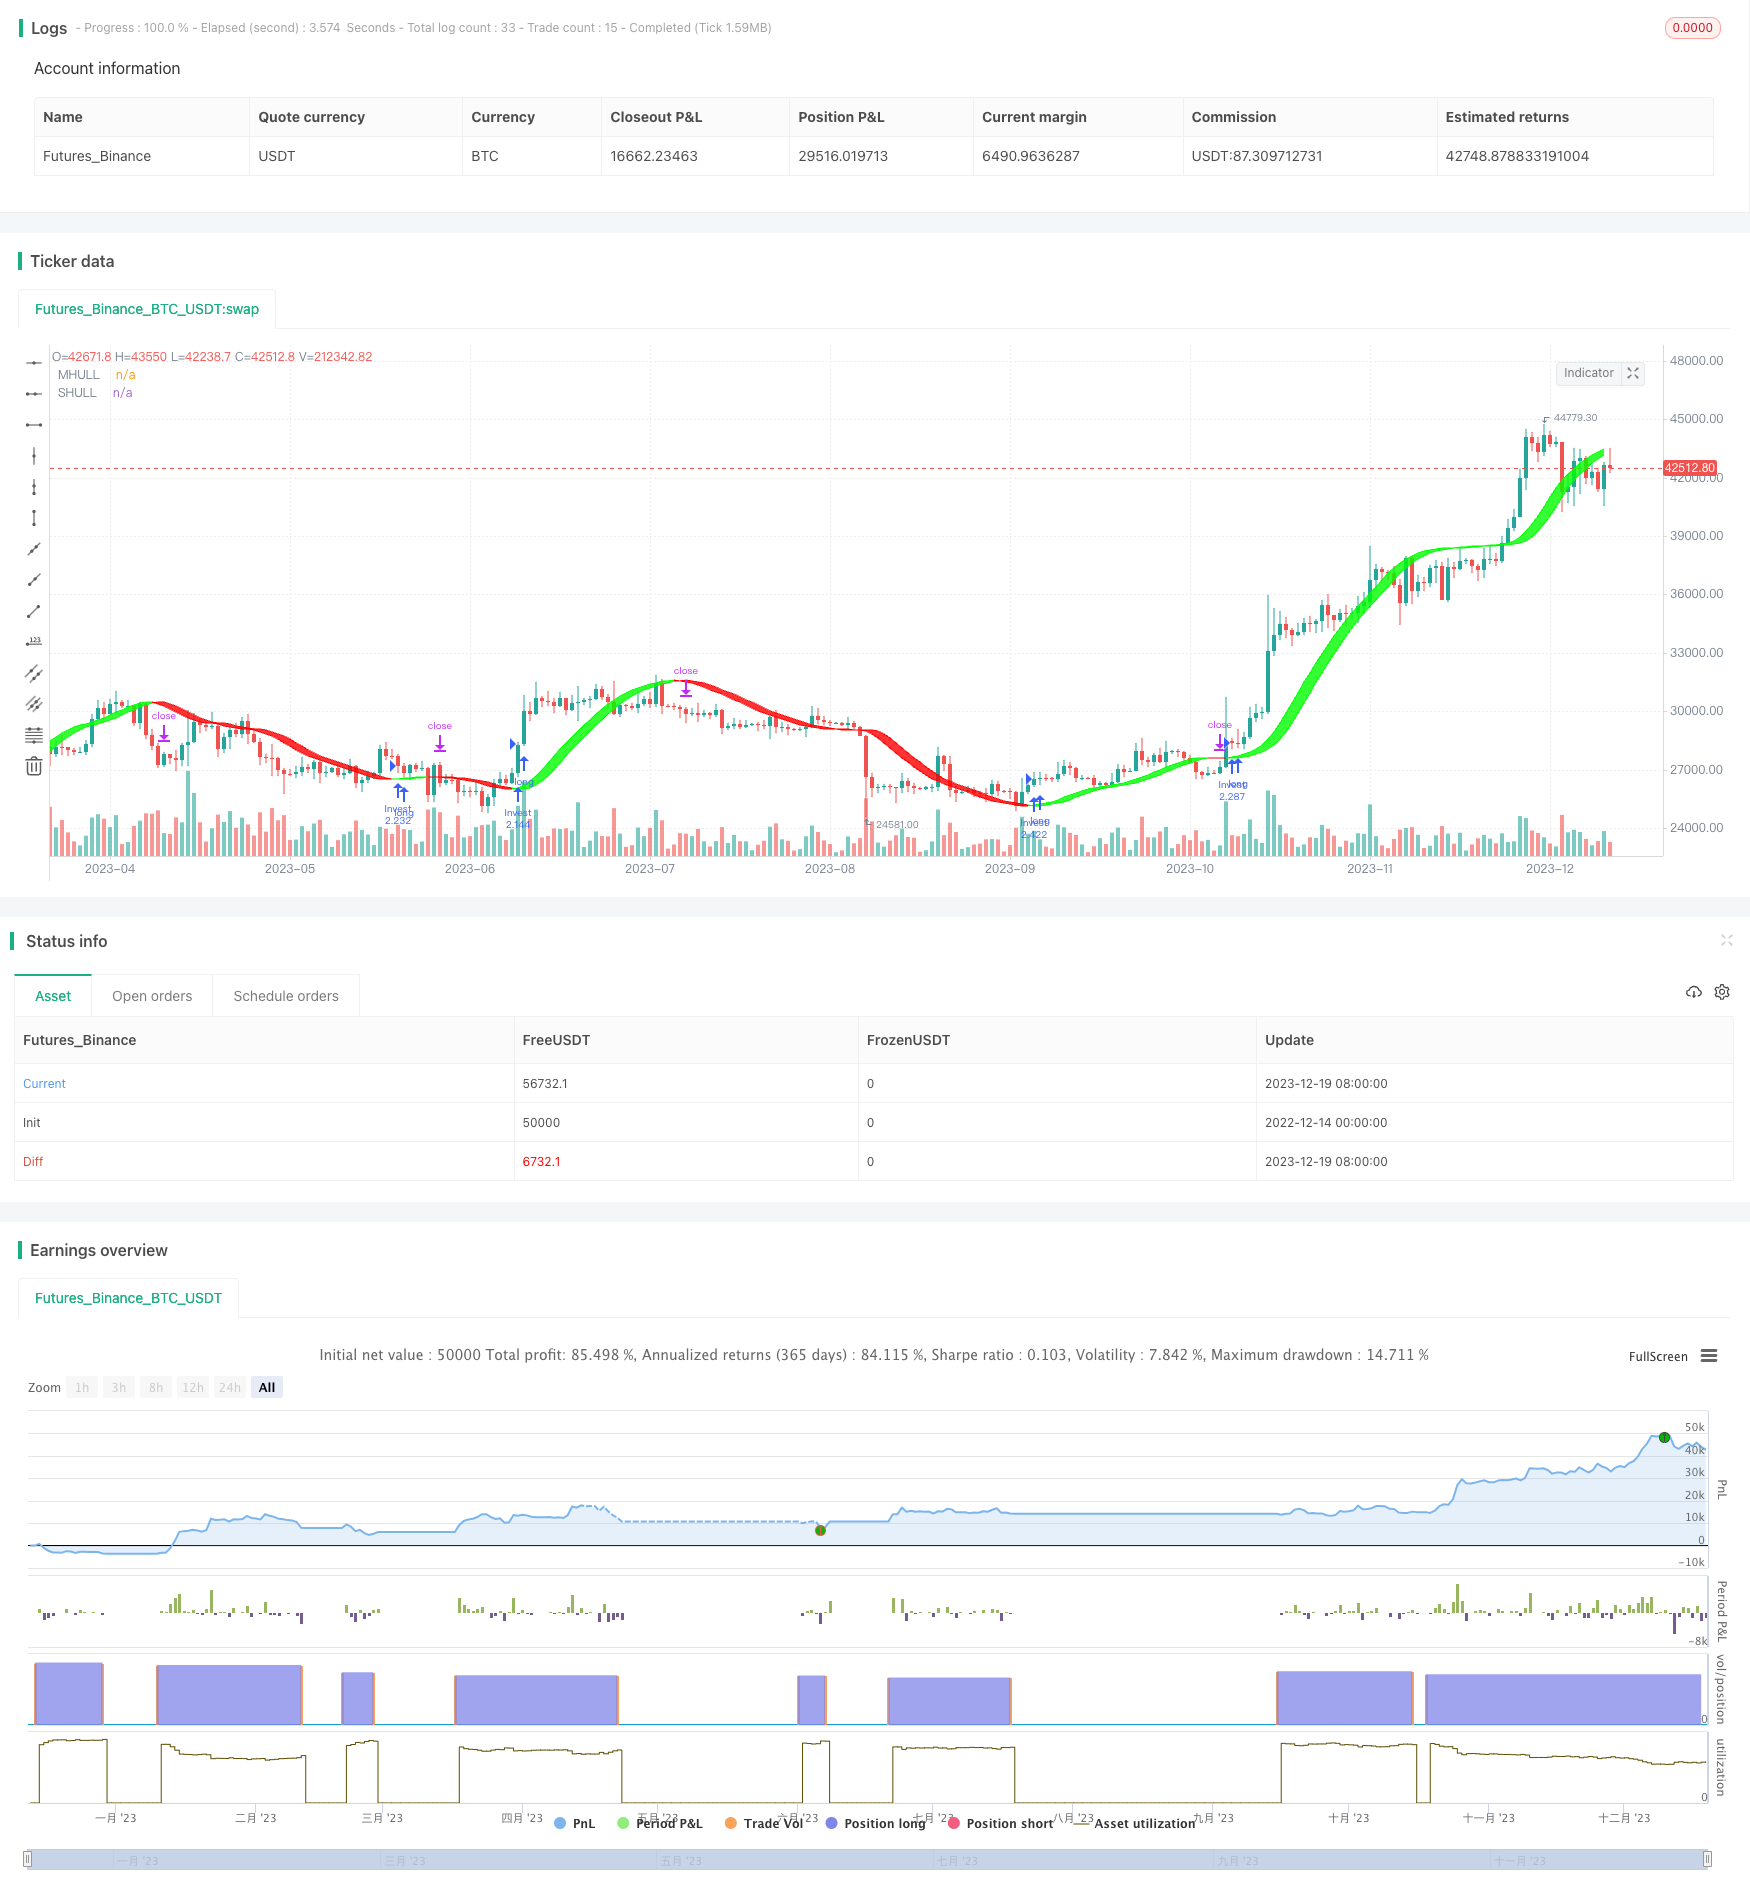
Overview
This strategy generates trading signals based on the dynamic moving average to go long when stock prices rise and close positions when prices fall. By combining the advantages of momentum indicators and moving averages, it aims at tracking medium-term price trends for steady profits.
Principle
The strategy mainly relies on three Hull Moving Average (HMA) variants – regular HMA, Weighted HMA (WHMA) and Exponential HMA (EHMA). As the code shows, it allows users to switch between the three Hull MAs.
The formula for HMA is:
HMA = WMA(2*WMA(close, n/2)-WMA(close, n), sqrt(n))
Where WMA is the Weighted Moving Average and n is the period parameter. Compared to SMA, HMA responds faster to price changes.
The formulas for WHMA and EHMA are similar. HMA is chosen as the default option.
After calculating the HMA, the strategy uses the midline value of HMA as trading signals. It goes long when the price crosses above the HMA midline and closes positions when the price falls below the line. Thus it tracks medium-term trends using the HMA midline for profits.
Advantages
Compared to traditional MA strategies, this strategy has the following edges:
- Faster response and stronger trend-following ability for timely entries and stops
- Lower unnecessary trade frequency, avoiding chasing surges and stops
- Flexible HMA parameters for adapting to more market environments
- Switchable HMA variants to expand applicability
Risks
There are also some risks:
- Generating multiple false signals during range-bound markets, increasing trade frequency and slippage costs
- Missing trend reversal points if HMA parameters are not set properly, leading to greater loss risks
- Liquidity risk and huge slippage when trading low liquidity stocks
Solutions:
- Optimize HMA parameters for best values
- Add other indicators to determine trend reversal points
- Select liquid stocks with large average daily volume
Improvements
The strategy can also be enhanced from the following aspects:
- Add volume or other filters to ensure signal reliability
- Combine MACD, KDJ for better timing, improving win rate
- Adjust HMA periods based on real-trade backtests
- Switch to WHMA or EHMA that performs the best for specific stocks
- Add stop loss mechanisms to control single trade loss
Summary
The dynamic MA trading strategy integrates the fast response of HMA to effectively track medium-term price trends. By opening long positions at appropriate timing and closing stops, it has demonstrated good backtest results. Further improvements in parameter tuning and stock filtering would lead to more steady excess returns. It is an easy-to-implement, risk-controllable quantitative strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_string_1 | 0 | Strategy Direction: long | short | all |
| v_input_1 | 2000 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2030 | Backtest Stop Year |
| v_input_5 | 12 | Backtest Stop Month |
| v_input_6 | 30 | Backtest Stop Day |
| v_input_7_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_string_2 | 0 | Hull Variation: Hma | Thma | Ehma |
| v_input_8 | 55 | Length(180-200 for floating S/R , 55 for swing entry) |
| v_input_9 | true | Color Hull according to trend? |
| v_input_10 | false | Color candles based on Hull's Trend? |
| v_input_11 | true | Show as a Band? |
| v_input_12 | true | Line Thickness |
| v_input_int_1 | 40 | Band Transparency |
Source Pine Script
/*backtest
start: 2022-12-14 00:00:00
end: 2023-12-20 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy('Position Investing by SirSeff', overlay=true, pyramiding=1, default_qty_type=strategy.percent_of_equity, default_qty_value=100, calc_on_order_fills=false, slippage=0, commission_type=strategy.commission.percent, commission_value=0)
strat_dir_input = input.string(title='Strategy Direction', defval='long', options=['long', 'short', 'all'])
strat_dir_value = strat_dir_input == 'long' ? strategy.direction.long : strat_dir_input == 'short' ? strategy.direction.short : strategy.direction.all
strategy.risk.allow_entry_in(strat_dir_value)
//////////////////////////////////////////////////////////////////////
// Testing Start dates
testStartYear = input(2000, 'Backtest Start Year')
testStartMonth = input(1, 'Backtest Start Month')
testStartDay = input(1, 'Backtest Start Day')
testPeriodStart = timestamp(testStartYear, testStartMonth, testStartDay, 0, 0)
//Stop date if you want to use a specific range of dates
testStopYear = input(2030, 'Backtest Stop Year')
testStopMonth = input(12, 'Backtest Stop Month')
testStopDay = input(30, 'Backtest Stop Day')
testPeriodStop = timestamp(testStopYear, testStopMonth, testStopDay, 0, 0)


testPeriod() => true
// Component Code Stop
//////////////////////////////////////////////////////////////////////
//INPUT
src = input(close, title='Source')
modeSwitch = input.string('Hma', title='Hull Variation', options=['Hma', 'Thma', 'Ehma'])
length = input(55, title='Length(180-200 for floating S/R , 55 for swing entry)')
switchColor = input(true, 'Color Hull according to trend?')
candleCol = input(false, title='Color candles based on Hull\'s Trend?')
visualSwitch = input(true, title='Show as a Band?')
thicknesSwitch = input(1, title='Line Thickness')
transpSwitch = input.int(40, title='Band Transparency', step=5)

//FUNCTIONS
//HMA
HMA(_src, _length) =>
    ta.wma(2 * ta.wma(_src, _length / 2) - ta.wma(_src, _length), math.round(math.sqrt(_length)))
//EHMA
EHMA(_src, _length) =>
    ta.ema(2 * ta.ema(_src, _length / 2) - ta.ema(_src, _length), math.round(math.sqrt(_length)))
//THMA
THMA(_src, _length) =>
    ta.wma(ta.wma(_src, _length / 3) * 3 - ta.wma(_src, _length / 2) - ta.wma(_src, _length), _length)

//SWITCH
Mode(modeSwitch, src, len) =>
    modeSwitch == 'Hma' ? HMA(src, len) : modeSwitch == 'Ehma' ? EHMA(src, len) : modeSwitch == 'Thma' ? THMA(src, len / 2) : na

//OUT
HULL = Mode(modeSwitch, src, length)
MHULL = HULL[0]
SHULL = HULL[2]

//COLOR
hullColor = switchColor ? HULL > HULL[2] ? #00ff00 : #ff0000 : #ff9800

//PLOT
///< Frame
Fi1 = plot(MHULL, title='MHULL', color=hullColor, linewidth=thicknesSwitch, transp=50)
Fi2 = plot(visualSwitch ? SHULL : na, title='SHULL', color=hullColor, linewidth=thicknesSwitch, transp=50)
///< Ending Filler
fill(Fi1, Fi2, title='Band Filler', color=hullColor, transp=transpSwitch)
///BARCOLOR
barcolor(color=candleCol ? switchColor ? hullColor : na : na)


if HULL[0] > HULL[2] and testPeriod()
    strategy.entry('Invest', strategy.long)
if HULL[0] < HULL[2] and testPeriod()
    strategy.entry('Pause', strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Trading-Strategy-Based-on-Dynamic-Moving-Average.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d