Strategy vault / Trend following
Volume Weighted Moving Average Convergence Divergence
This strategy is an improved version of the classic MACD indicator, using 11 different types of moving averages to smooth the price curve and reduce misleading signals. The indicator consists of the fast line, slow…
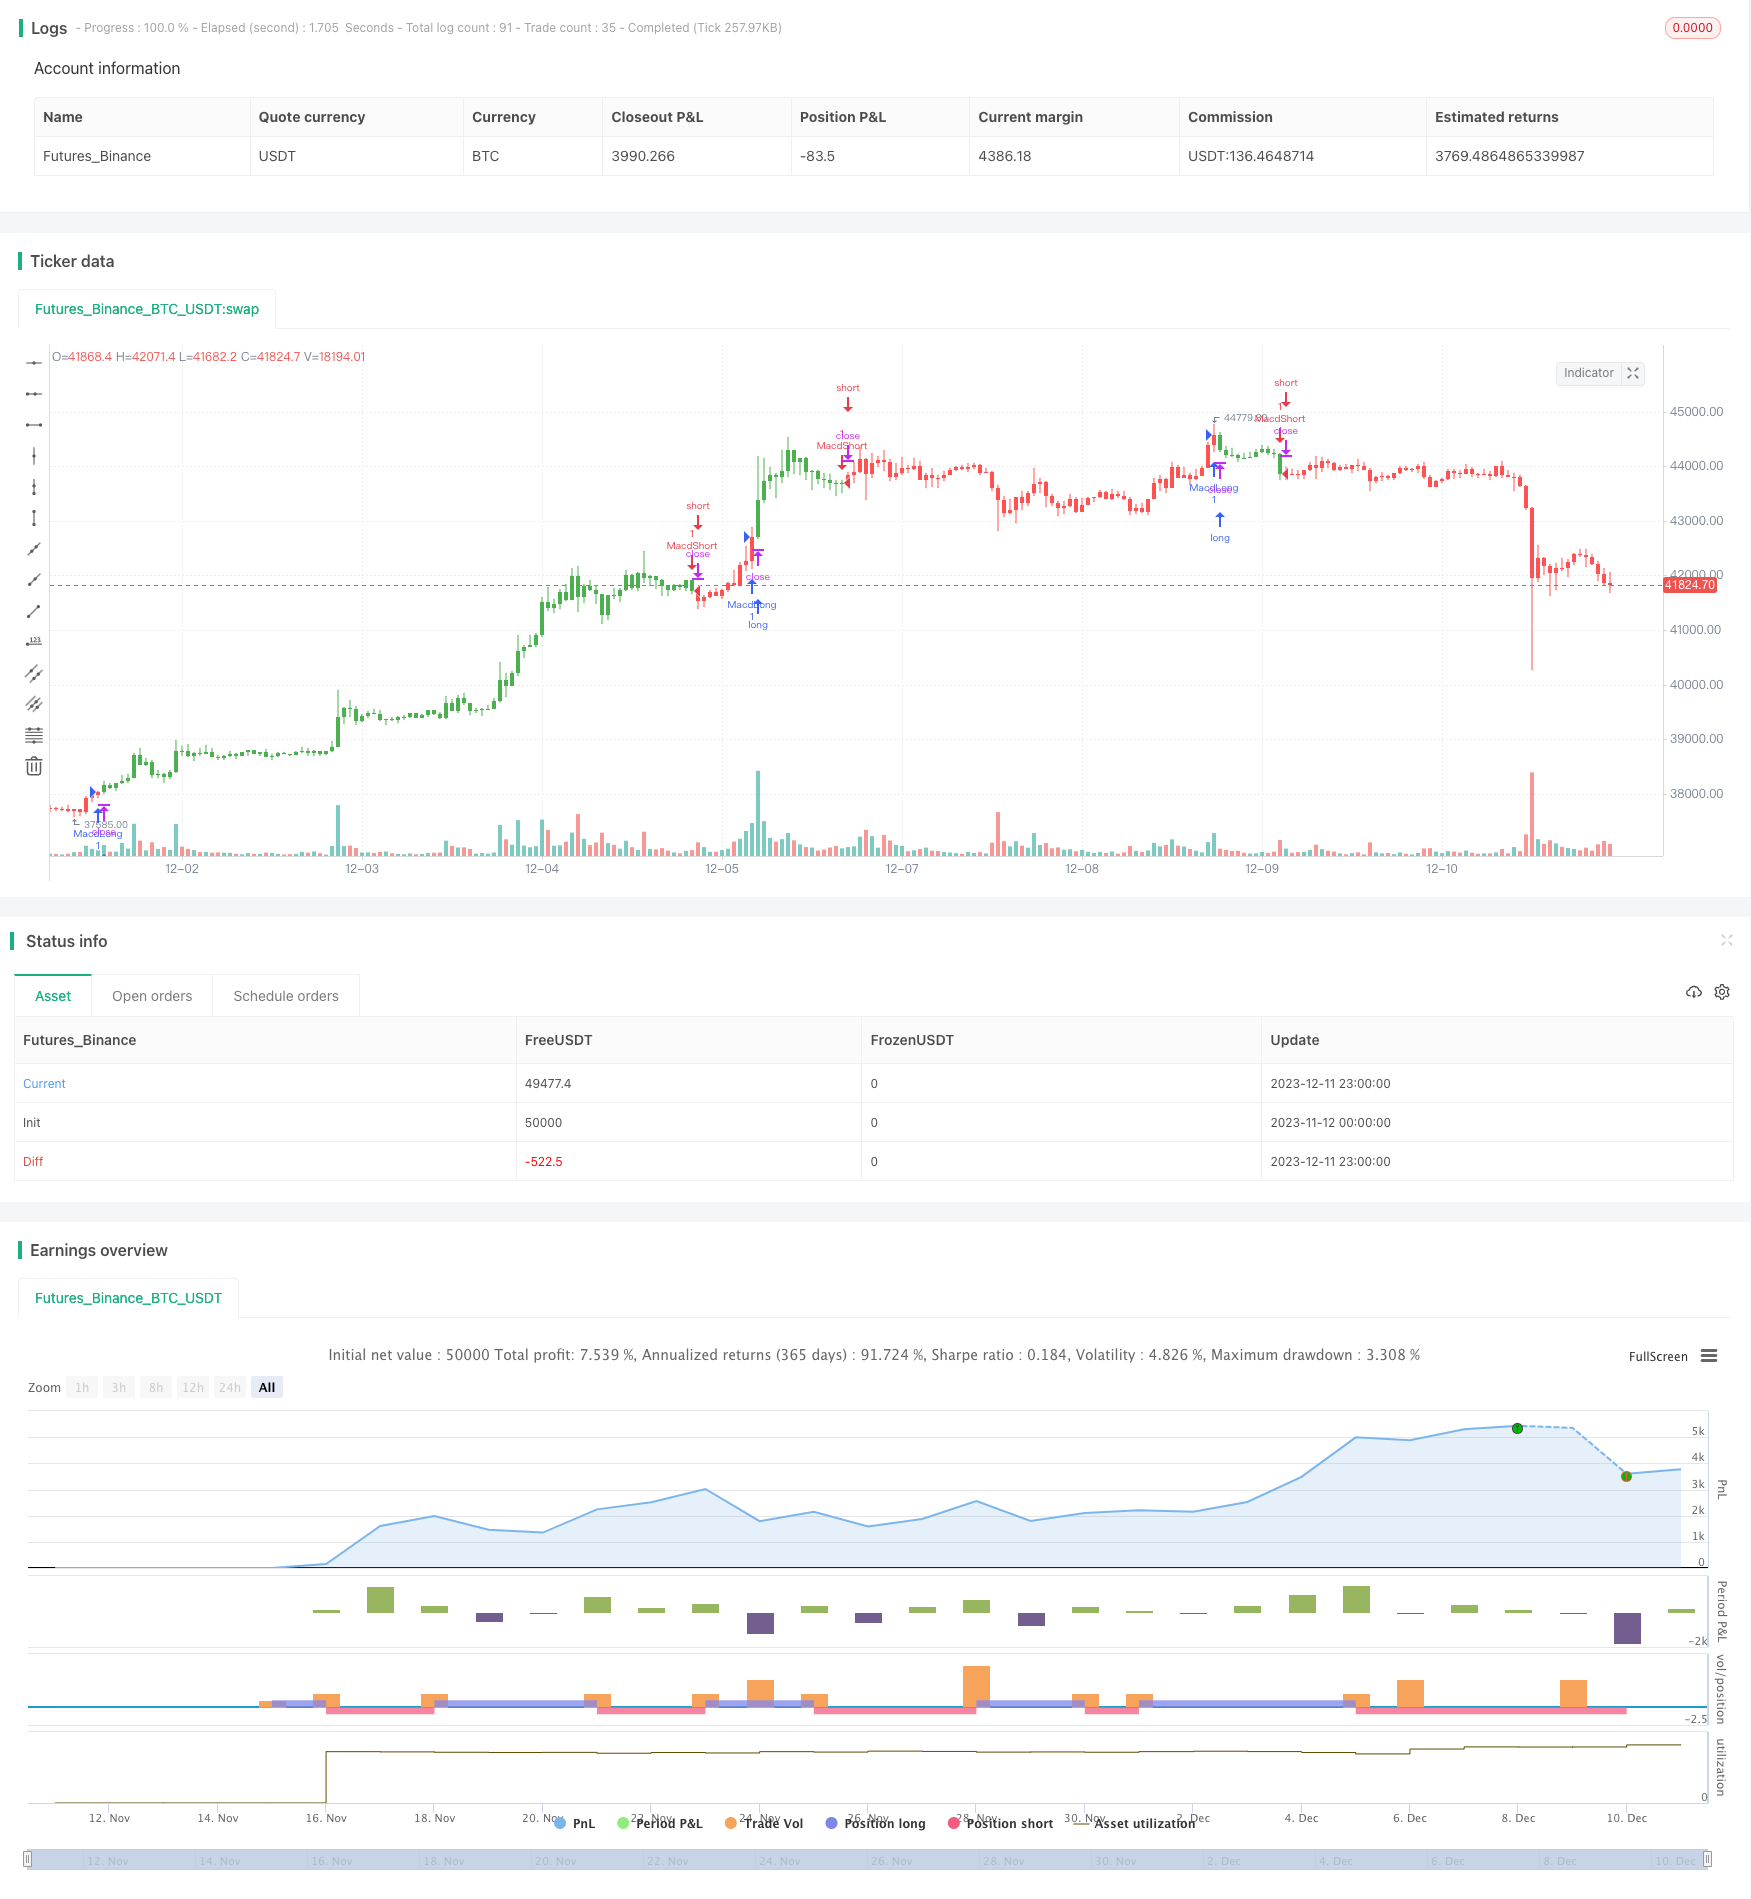
Overview
This strategy is an improved version of the classic MACD indicator, using 11 different types of moving averages to smooth the price curve and reduce misleading signals. The indicator consists of the fast line, slow line and histogram. The fast line and slow line respectively adopt the fast moving average and slow moving average of prices. The histogram represents the difference between the fast line and slow line. Buying signals are generated when the fast line crosses the slow line from bottom to top, while selling signals are generated from top to bottom.
Strategy Principles
Calculate the fast moving average line MA12. 11 different calculation methods for moving average lines are available for selection, with Volume Variability Rate line VAR as default.
Calculate the slow moving average line MA26. 11 different calculation methods for moving average lines are available for selection, with Volume Variability Rate line VAR as default.
Calculate the difference between the fast and slow lines SRC2 = MA12 - MA26.
Calculate the trigger line MATR for SRC2 using a moving average line with length of 9. 11 different calculation methods are available for selection, with Volume Variability Rate line VAR as default.
Calculate the MACD histogram HIST = SRC2 - MATR. Buying signals are generated when the histogram changes from negative to positive. Selling signals are generated when the histogram changes from positive to negative.
Analysis of Advantages
11 different types of moving average lines can be selected to calculate the fast line, slow line and trigger line, which largely reduces the lagging of common moving averages and improves the accuracy of prediction signals.
The Volume Variability Rate line VAR can automatically adjust the weights of the moving average to better adapt to market changes.
The double moving average lines with buffer zone can effectively filter out market noise.
The MACD histogram as the triggering signal can overcome the lagging problem brought by the traditional crossing of fast and slow MACD lines.
Risk Analysis
MACD indicator has weak capability in judging the trending or consolidating market.
The moving average itself has a certain degree of lagging. VAR partially reduces but cannot completely solve the problem.
Error accumulation may lead to wrong signals or missing effective signals.
Direction for Optimization
Choose matching moving average calculation methods for specific market conditions based on backtest results.
Optimize the length parameters of the fast line, slow line and trigger line to find the best parameter combinations to reduce wrong signals.
Add auxiliary indicators such as RSI and Bollinger Bands to confirm buy/sell signals.
Conclusion
This strategy is an optimized version for the classic MACD indicator. By using multiple moving average patterns to compute the MACD fast line, slow line and histogram, it greatly enhances the utility of this indicator. Meanwhile, it also has certain limitations. Continuous optimization catered to actual market conditions is needed to maximize the efficacy in trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 12 | Short Moving Average Length |
| v_input_3 | 26 | Long Moving Average Length |
| v_input_4 | 9 | Trigger Length |
| v_input_5 | 0.7 | TILLSON T3 Volume Factor |
| v_input_6 | true | Bar Coloring On/Off ? |
| v_input_7 | 0 | Moving Average Type: VAR | EMA | WMA | DEMA | TMA | SMA | WWMA | ZLEMA | TSF | HULL | TILL |
| v_input_8 | 9 | From Month |
| v_input_9 | true | From Day |
| v_input_10 | 2018 | From Year |
| v_input_11 | true | To Month |
| v_input_12 | true | To Day |
| v_input_13 | 9999 | To Year |
Source Pine Script
/*backtest
start: 2023-11-12 00:00:00
end: 2023-12-12 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © KivancOzbilgic


//developer: Gerald Appel
//author: @kivancozbilgic

strategy("MACD ReLoaded","MACDRe", overlay=true)
src = input(close, title="Source")
length=input(12, "Short Moving Average Length", minval=1)
length1=input(26, "Long Moving Average Length", minval=1)
length2=input(9, "Trigger Length", minval=1)
T3a1 = input(0.7, "TILLSON T3 Volume Factor", step=0.1)
barcoloring = input(title="Bar Coloring On/Off ?", type=input.bool, defval=true)

mav = input(title="Moving Average Type", defval="VAR", options=["SMA", "EMA", "WMA", "DEMA", "TMA", "VAR", "WWMA", "ZLEMA", "TSF", "HULL", "TILL"])
Var_Func(src,length)=>
    valpha=2/(length+1)
    vud1=src>src[1] ? src-src[1] : 0
    vdd1=src<src[1] ? src[1]-src : 0
    vUD=sum(vud1,9)
    vDD=sum(vdd1,9)
    vCMO=nz((vUD-vDD)/(vUD+vDD))
    VAR=0.0
    VAR:=nz(valpha*abs(vCMO)*src)+(1-valpha*abs(vCMO))*nz(VAR[1])
VAR=Var_Func(src,length)
DEMA = ( 2 * ema(src,length)) - (ema(ema(src,length),length) )
Wwma_Func(src,length)=>
    wwalpha = 1/ length
    WWMA = 0.0
    WWMA := wwalpha*src + (1-wwalpha)*nz(WWMA[1])
WWMA=Wwma_Func(src,length)
Zlema_Func(src,length)=>
    zxLag = length/2==round(length/2) ? length/2 : (length - 1) / 2
    zxEMAData = (src + (src - src[zxLag]))
    ZLEMA = ema(zxEMAData, length)
ZLEMA=Zlema_Func(src,length)
Tsf_Func(src,length)=>
    lrc = linreg(src, length, 0)
    lrc1 = linreg(src,length,1)
    lrs = (lrc-lrc1)
    TSF = linreg(src, length, 0)+lrs
TSF=Tsf_Func(src,length)
HMA = wma(2 * wma(src, length / 2) - wma(src, length), round(sqrt(length)))
T3e1=ema(src, length)
T3e2=ema(T3e1,length)
T3e3=ema(T3e2,length)
T3e4=ema(T3e3,length)
T3e5=ema(T3e4,length)
T3e6=ema(T3e5,length)
T3c1=-T3a1*T3a1*T3a1
T3c2=3*T3a1*T3a1+3*T3a1*T3a1*T3a1
T3c3=-6*T3a1*T3a1-3*T3a1-3*T3a1*T3a1*T3a1
T3c4=1+3*T3a1+T3a1*T3a1*T3a1+3*T3a1*T3a1
T3=T3c1*T3e6+T3c2*T3e5+T3c3*T3e4+T3c4*T3e3


getMA(src, length) =>
    ma = 0.0
    if mav == "SMA"
        ma := sma(src, length)
        ma

    if mav == "EMA"
        ma := ema(src, length)
        ma

    if mav == "WMA"
        ma := wma(src, length)
        ma

    if mav == "DEMA"
        ma := DEMA
        ma

    if mav == "TMA"
        ma := sma(sma(src, ceil(length / 2)), floor(length / 2) + 1)
        ma

    if mav == "VAR"
        ma := VAR
        ma

    if mav == "WWMA"
        ma := WWMA
        ma

    if mav == "ZLEMA"
        ma := ZLEMA
        ma

    if mav == "TSF"
        ma := TSF
        ma

    if mav == "HULL"
        ma := HMA
        ma

    if mav == "TILL"
        ma := T3
        ma
    ma

MA12=getMA(src, length)


Var_Func1(src,length1)=>
    valpha1=2/(length1+1)
    vud11=src>src[1] ? src-src[1] : 0
    vdd11=src<src[1] ? src[1]-src : 0
    vUD1=sum(vud11,9)
    vDD1=sum(vdd11,9)
    vCMO1=nz((vUD1-vDD1)/(vUD1+vDD1))
    VAR1=0.0
    VAR1:=nz(valpha1*abs(vCMO1)*src)+(1-valpha1*abs(vCMO1))*nz(VAR1[1])
VAR1=Var_Func1(src,length1)
DEMA1 = ( 2 * ema(src,length1)) - (ema(ema(src,length1),length1) )
Wwma_Func1(src,length1)=>
    wwalpha1 = 1/ length1
    WWMA1 = 0.0
    WWMA1 := wwalpha1*src + (1-wwalpha1)*nz(WWMA1[1])
WWMA1=Wwma_Func1(src,length1)
Zlema_Func1(src,length1)=>
    zxLag1 = length1/2==round(length1/2) ? length1/2 : (length1 - 1) / 2
    zxEMAData1 = (src + (src - src[zxLag1]))
    ZLEMA1 = ema(zxEMAData1, length1)
ZLEMA1=Zlema_Func1(src,length1)
Tsf_Func1(src,length1)=>
    lrc1 = linreg(src, length1, 0)
    lrc11 = linreg(src,length1,1)
    lrs1 = (lrc1-lrc11)
    TSF1 = linreg(src, length1, 0)+lrs1
TSF1=Tsf_Func1(src,length1)
HMA1 = wma(2 * wma(src, length1 / 2) - wma(src, length1), round(sqrt(length1)))
T3e11=ema(src, length1)
T3e21=ema(T3e11,length1)
T3e31=ema(T3e21,length1)
T3e41=ema(T3e31,length1)
T3e51=ema(T3e41,length1)
T3e61=ema(T3e51,length1)
T3c11=-T3a1*T3a1*T3a1
T3c21=3*T3a1*T3a1+3*T3a1*T3a1*T3a1
T3c31=-6*T3a1*T3a1-3*T3a1-3*T3a1*T3a1*T3a1
T3c41=1+3*T3a1+T3a1*T3a1*T3a1+3*T3a1*T3a1
T31=T3c11*T3e61+T3c21*T3e51+T3c31*T3e41+T3c41*T3e31


getMA1(src, length1) =>
    ma1 = 0.0
    if mav == "SMA"
        ma1 := sma(src, length1)
        ma1

    if mav == "EMA"
        ma1 := ema(src, length1)
        ma1

    if mav == "WMA"
        ma1 := wma(src, length1)
        ma1

    if mav == "DEMA"
        ma1 := DEMA1
        ma1

    if mav == "TMA"
        ma1 := sma(sma(src, ceil(length1 / 2)), floor(length1 / 2) + 1)
        ma1

    if mav == "VAR"
        ma1 := VAR1
        ma1

    if mav == "WWMA"
        ma1:= WWMA1
        ma1

    if mav == "ZLEMA"
        ma1 := ZLEMA1
        ma1

    if mav == "TSF"
        ma1 := TSF1
        ma1

    if mav == "HULL"
        ma1 := HMA1
        ma1

    if mav == "TILL"
        ma1 := T31
        ma1
    ma1

MA26=getMA1(src, length1)


src2=MA12-MA26

Var_Func2(src2,length2)=>
    valpha2=2/(length2+1)
    vud12=src2>src2[1] ? src2-src2[1] : 0
    vdd12=src2<src2[1] ? src2[1]-src2 : 0
    vUD2=sum(vud12,9)
    vDD2=sum(vdd12,9)
    vCMO2=nz((vUD2-vDD2)/(vUD2+vDD2))
    VAR2=0.0
    VAR2:=nz(valpha2*abs(vCMO2)*src2)+(1-valpha2*abs(vCMO2))*nz(VAR2[1])
VAR2=Var_Func2(src2,length2)
DEMA2 = ( 2 * ema(src2,length2)) - (ema(ema(src2,length2),length2) )
Wwma_Func2(src2,length2)=>
    wwalpha2 = 1/ length2
    WWMA2 = 0.0
    WWMA2 := wwalpha2*src2 + (1-wwalpha2)*nz(WWMA2[1])
WWMA2=Wwma_Func2(src2,length2)
Zlema_Func2(src2,length2)=>
    zxLag2 = length2/2==round(length2/2) ? length2/2 : (length2 - 1) / 2
    zxEMAData2 = (src2 + (src2 - src2[zxLag2]))
    ZLEMA2 = ema(zxEMAData2, length2)
ZLEMA2=Zlema_Func2(src2,length2)
Tsf_Func2(src2,length2)=>
    lrc2 = linreg(src2, length2, 0)
    lrc12 = linreg(src2,length2,1)
    lrs2 = (lrc2-lrc12)
    TSF2 = linreg(src2, length2, 0)+lrs2
TSF2=Tsf_Func2(src2,length2)
HMA2 = wma(2 * wma(src2, length2 / 2) - wma(src2, length2), round(sqrt(length2)))
T3e12=ema(src2, length2)
T3e22=ema(T3e12,length2)
T3e32=ema(T3e22,length2)
T3e42=ema(T3e32,length2)
T3e52=ema(T3e42,length2)
T3e62=ema(T3e52,length2)
T3c12=-T3a1*T3a1*T3a1
T3c22=3*T3a1*T3a1+3*T3a1*T3a1*T3a1
T3c32=-6*T3a1*T3a1-3*T3a1-3*T3a1*T3a1*T3a1
T3c42=1+3*T3a1+T3a1*T3a1*T3a1+3*T3a1*T3a1
T32=T3c12*T3e62+T3c22*T3e52+T3c32*T3e42+T3c42*T3e32


getMA2(src2, length2) =>
    ma2 = 0.0
    if mav == "SMA"
        ma2 := sma(src2, length2)
        ma2

    if mav == "EMA"
        ma2 := ema(src2, length2)
        ma2

    if mav == "WMA"
        ma2 := wma(src2, length2)
        ma2

    if mav == "DEMA"
        ma2 := DEMA2
        ma2

    if mav == "TMA"
        ma2 := sma(sma(src2, ceil(length2 / 2)), floor(length2 / 2) + 1)
        ma2

    if mav == "VAR"
        ma2 := VAR2
        ma2

    if mav == "WWMA"
        ma2 := WWMA2
        ma2

    if mav == "ZLEMA"
        ma2 := ZLEMA2
        ma2

    if mav == "TSF"
        ma2 := TSF2
        ma2

    if mav == "HULL"
        ma2 := HMA2
        ma2

    if mav == "TILL"
        ma2 := T32
        ma2
    ma2


MATR=getMA2(MA12-MA26, length2)
hist = src2 - MATR

FromMonth = input(defval = 9, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2018, title = "From Year", minval = 999)
ToMonth   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 9999, title = "To Year", minval = 999)
start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)
window()  => time >= start and time <= finish ? true : false
buySignal = crossover(hist, 0)
if (crossover(hist, 0))
	strategy.entry("MacdLong", strategy.long, comment="MacdLong")
sellSignal = crossunder(hist, 0)
if (crossunder(hist, 0))
	strategy.entry("MacdShort", strategy.short, comment="MacdShort")
buy1= barssince(buySignal)
sell1 = barssince(sellSignal)
color1 = buy1[1] < sell1[1] ? color.green : buy1[1] > sell1[1] ? color.red : na
barcolor(barcoloring ? color1 : na)


//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Volume-Weighted-Moving-Average-Convergence-Divergence.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d