Strategy vault / Trend following
Dual EMA Golden Cross Profit Taking Strategy
This strategy calculates two groups of EMA indicators with different parameters and sets the buy signal when the two groups of EMA indicators have a golden cross and the sell signal when another two groups of EMA…
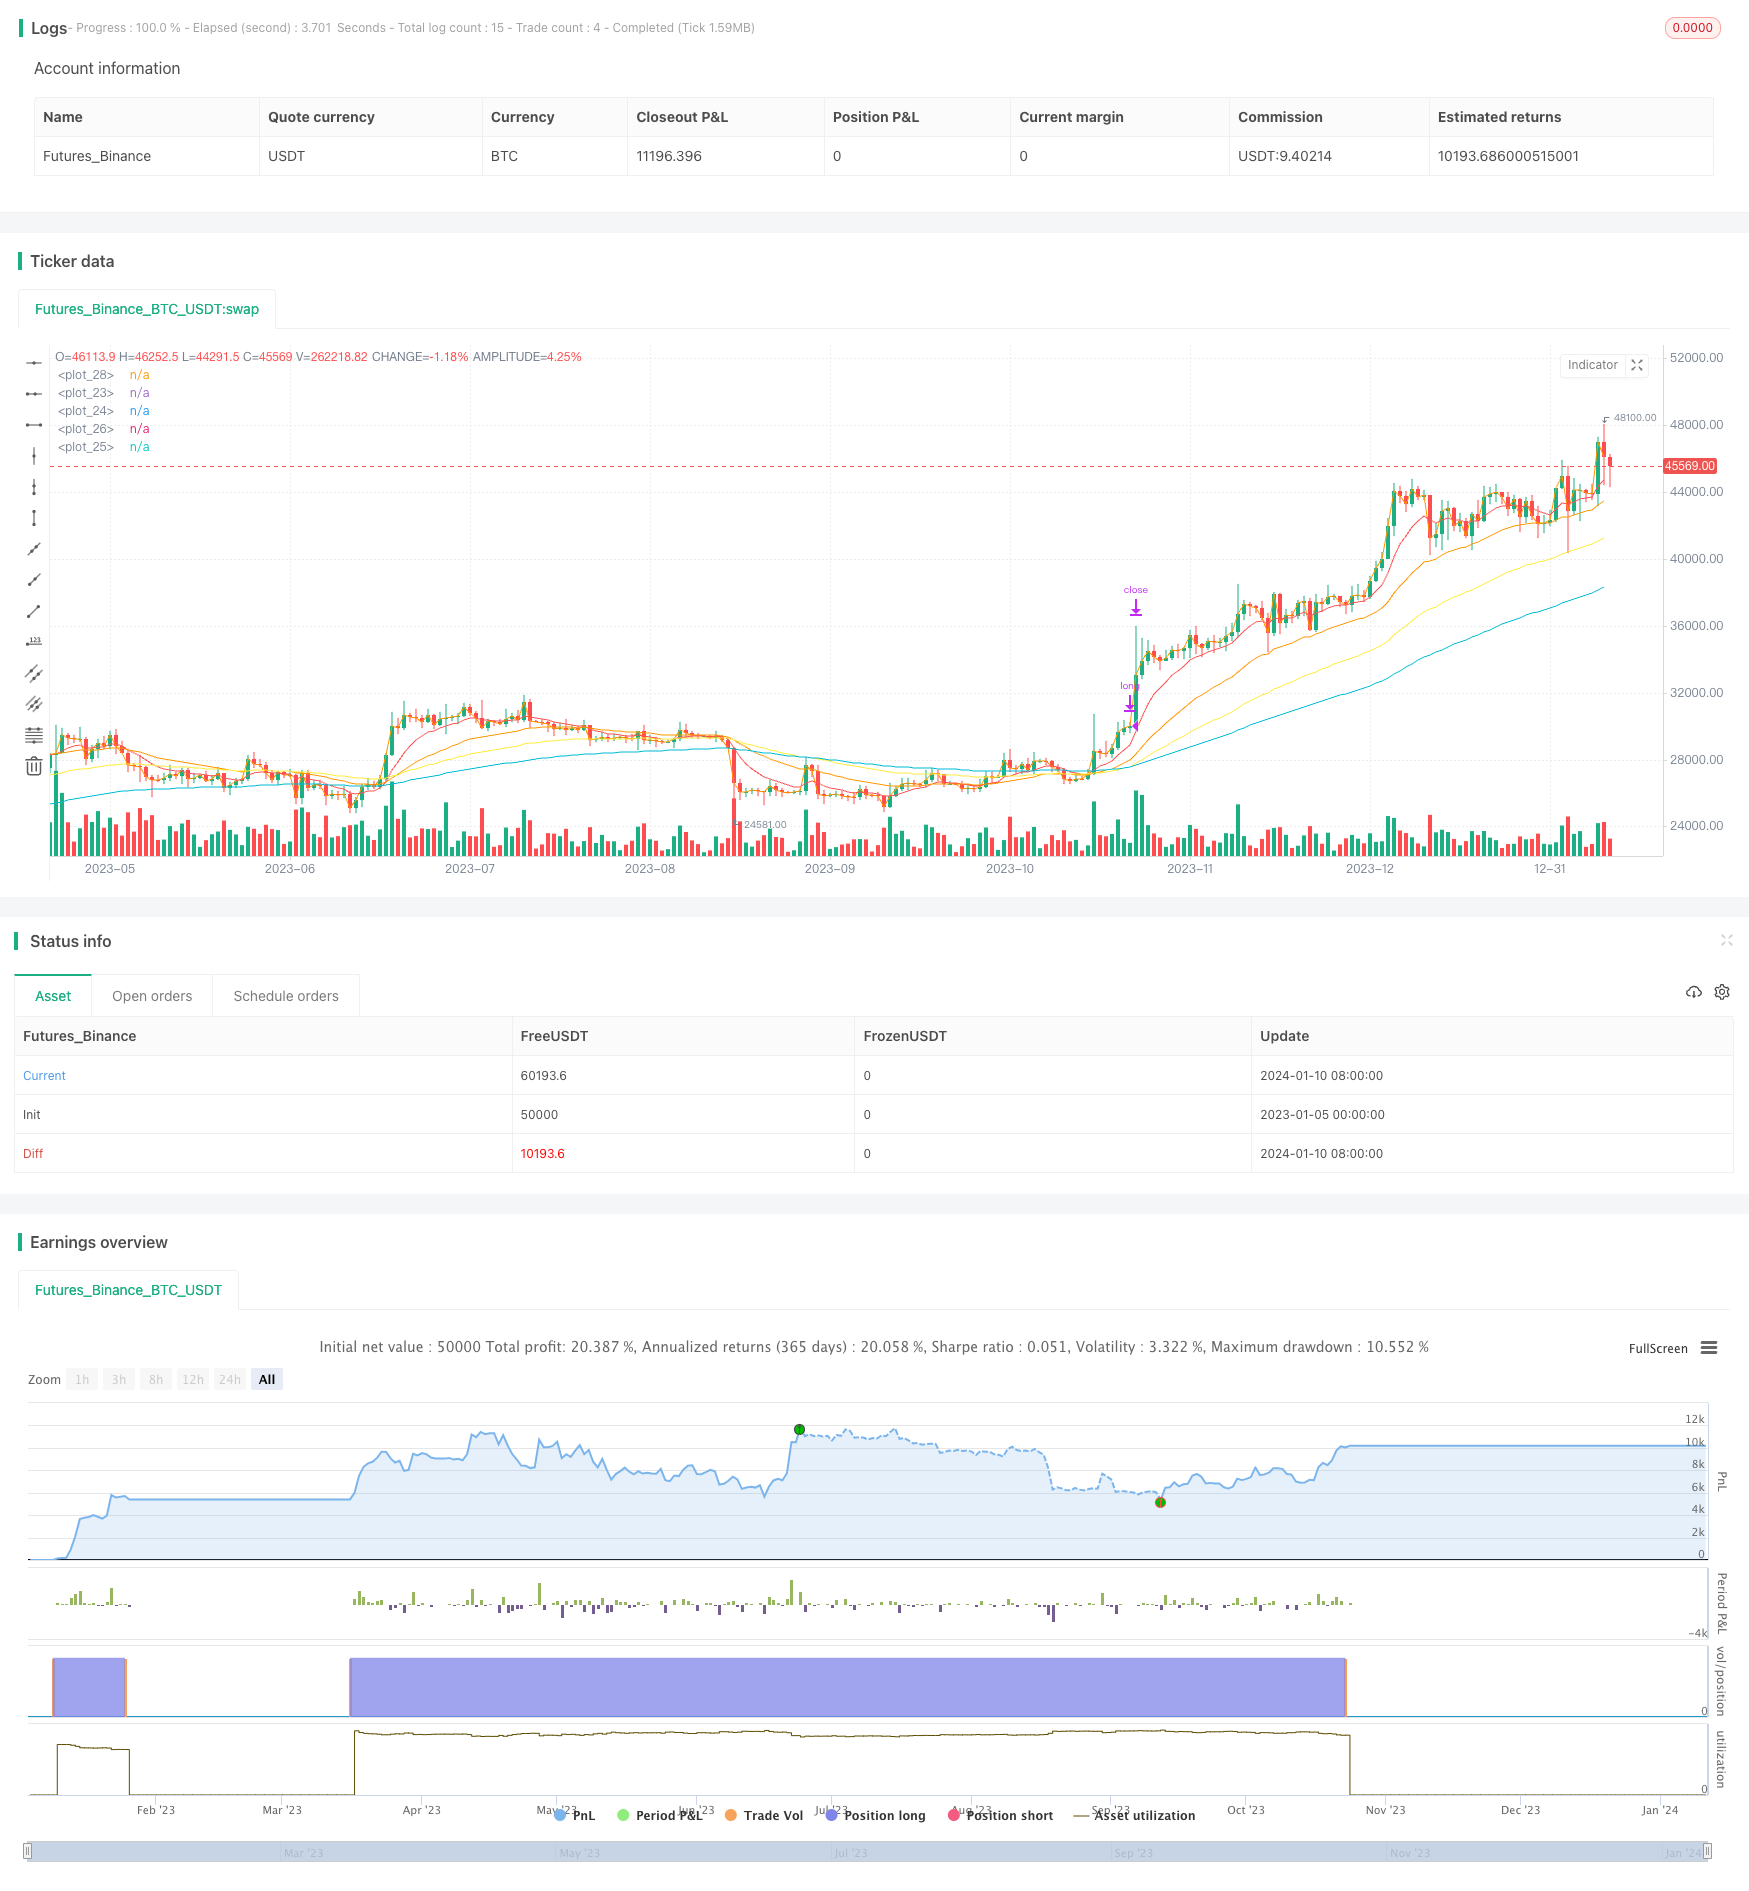
Overview
This strategy calculates two groups of EMA indicators with different parameters and sets the buy signal when the two groups of EMA indicators have a golden cross and the sell signal when another two groups of EMA indicators have a death cross, so as to achieve an efficient short-term trading strategy.
Strategy Principle
The strategy uses 4 EMA indicators, EMA1 with a period of 9, EMA2 with a period of 26, EMA3 with a period of 100, and EMA4 with a period of 55. The buy signal is set when EMA1 crosses over EMA2, indicating that the short-term EMA crosses over the long-term EMA, which is a typical golden cross signal. The sell signal is set when EMA3 crosses below EMA4, which is a death cross signal. This allows fast entry when the short-term EMA indicator has a golden cross and fast stop loss when the long-term EMA indicator has a death cross to achieve efficient short-term trading.
Advantage Analysis
- Use dual EMA cross for fast entry and exit to quickly lock short-term profits
- Clear and simple trading signals, easy to implement
- Adjustable parameters to suit different markets
- Large profit range, suitable for short-term scalping trading
Risk Analysis
- Dual EMA cross may have false signals, needs to be filtered with other indicators
- Improper EMA parameter settings may cause too sensitive or dull
- Need to closely monitor larger cycles for timely profit-taking
Optimization Direction
- Can add MACD, KDJ and other indicators for signal filtering to improve signal accuracy
- Can test more combinations to find the optimal EMA parameters
- Can set moving stop loss to lock in profits
Summary
Overall, this is a very typical and effective short-term trading strategy. The advantages are fast entry and exit, suitable for scalping and large profit range. There are also some risks that need attention and prevention. With proper parameter adjustment and assistance of other indicators for signal filtering, it can become a very practical short-term trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 9 | EMA_L |
| v_input_int_2 | 26 | EMA_L2 |
| v_input_int_3 | 100 | EMA_S |
| v_input_int_4 | 55 | EMA_S2 |
Source Pine Script
/*backtest
start: 2023-01-05 00:00:00
end: 2024-01-11 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © YukalMoon

//@version=5
strategy(title="EMA SCALPEUR", overlay=true, initial_capital = 1000)


//// input controls

EMA_L = input.int (title = "EMA_L", defval = 9, minval = 1, maxval = 100, step =1)
EMA_L2 = input.int (title = "EMA_L2", defval = 26, minval = 1, maxval = 100, step =1)
EMA_S = input.int (title = "EMA_S", defval = 100, minval = 1, maxval = 100, step =1)
EMA_S2 = input.int (title = "EMA_S2", defval = 55, minval = 1, maxval = 100, step =1)


/// mise en place de ema

shortest = ta.ema(close, 9)
short = ta.ema(close, 26)
longer = ta.ema(close, 100)
longest = ta.ema(close, 55)

plot(shortest, color = color.red)
plot(short, color = color.orange)
plot(longer, color = color.aqua)
plot(longest, color = color.yellow)

plot(close)

//// trading indicators

EMA1 = ta.ema (close,EMA_L)
EMA2 = ta.ema (close,EMA_L2)
EMA3 = ta.ema (close, EMA_S)
EMA4 = ta.ema (close, EMA_S2)


buy = ta.crossover(EMA1, EMA2)
//sell = ta.crossunder(EMA1, EMA2)

buyexit = ta.crossunder(EMA3, EMA4)
//sellexit = ta.crossover(EMA3, EMA4)

/////strategy

strategy.entry ("long", strategy.long, when = buy, comment = "EXIT-LONG")
//strategy.entry ("short", strategy.short, when = sell, comment = "ENTER-SHORT")


///// market exit

strategy.close ("long", when = buyexit, comment = "ENTER-LONG")
//strategy.close ("short",  when = sellexit, comment = "EXIT-SHORT")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Golden-Cross-Profit-Taking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crossover EMA Short term Trading StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover Oscillation Tracking StrategyPine Script · Trend following · 5m