Strategy vault / Trend following
MACD Trend Following Strategy 433124
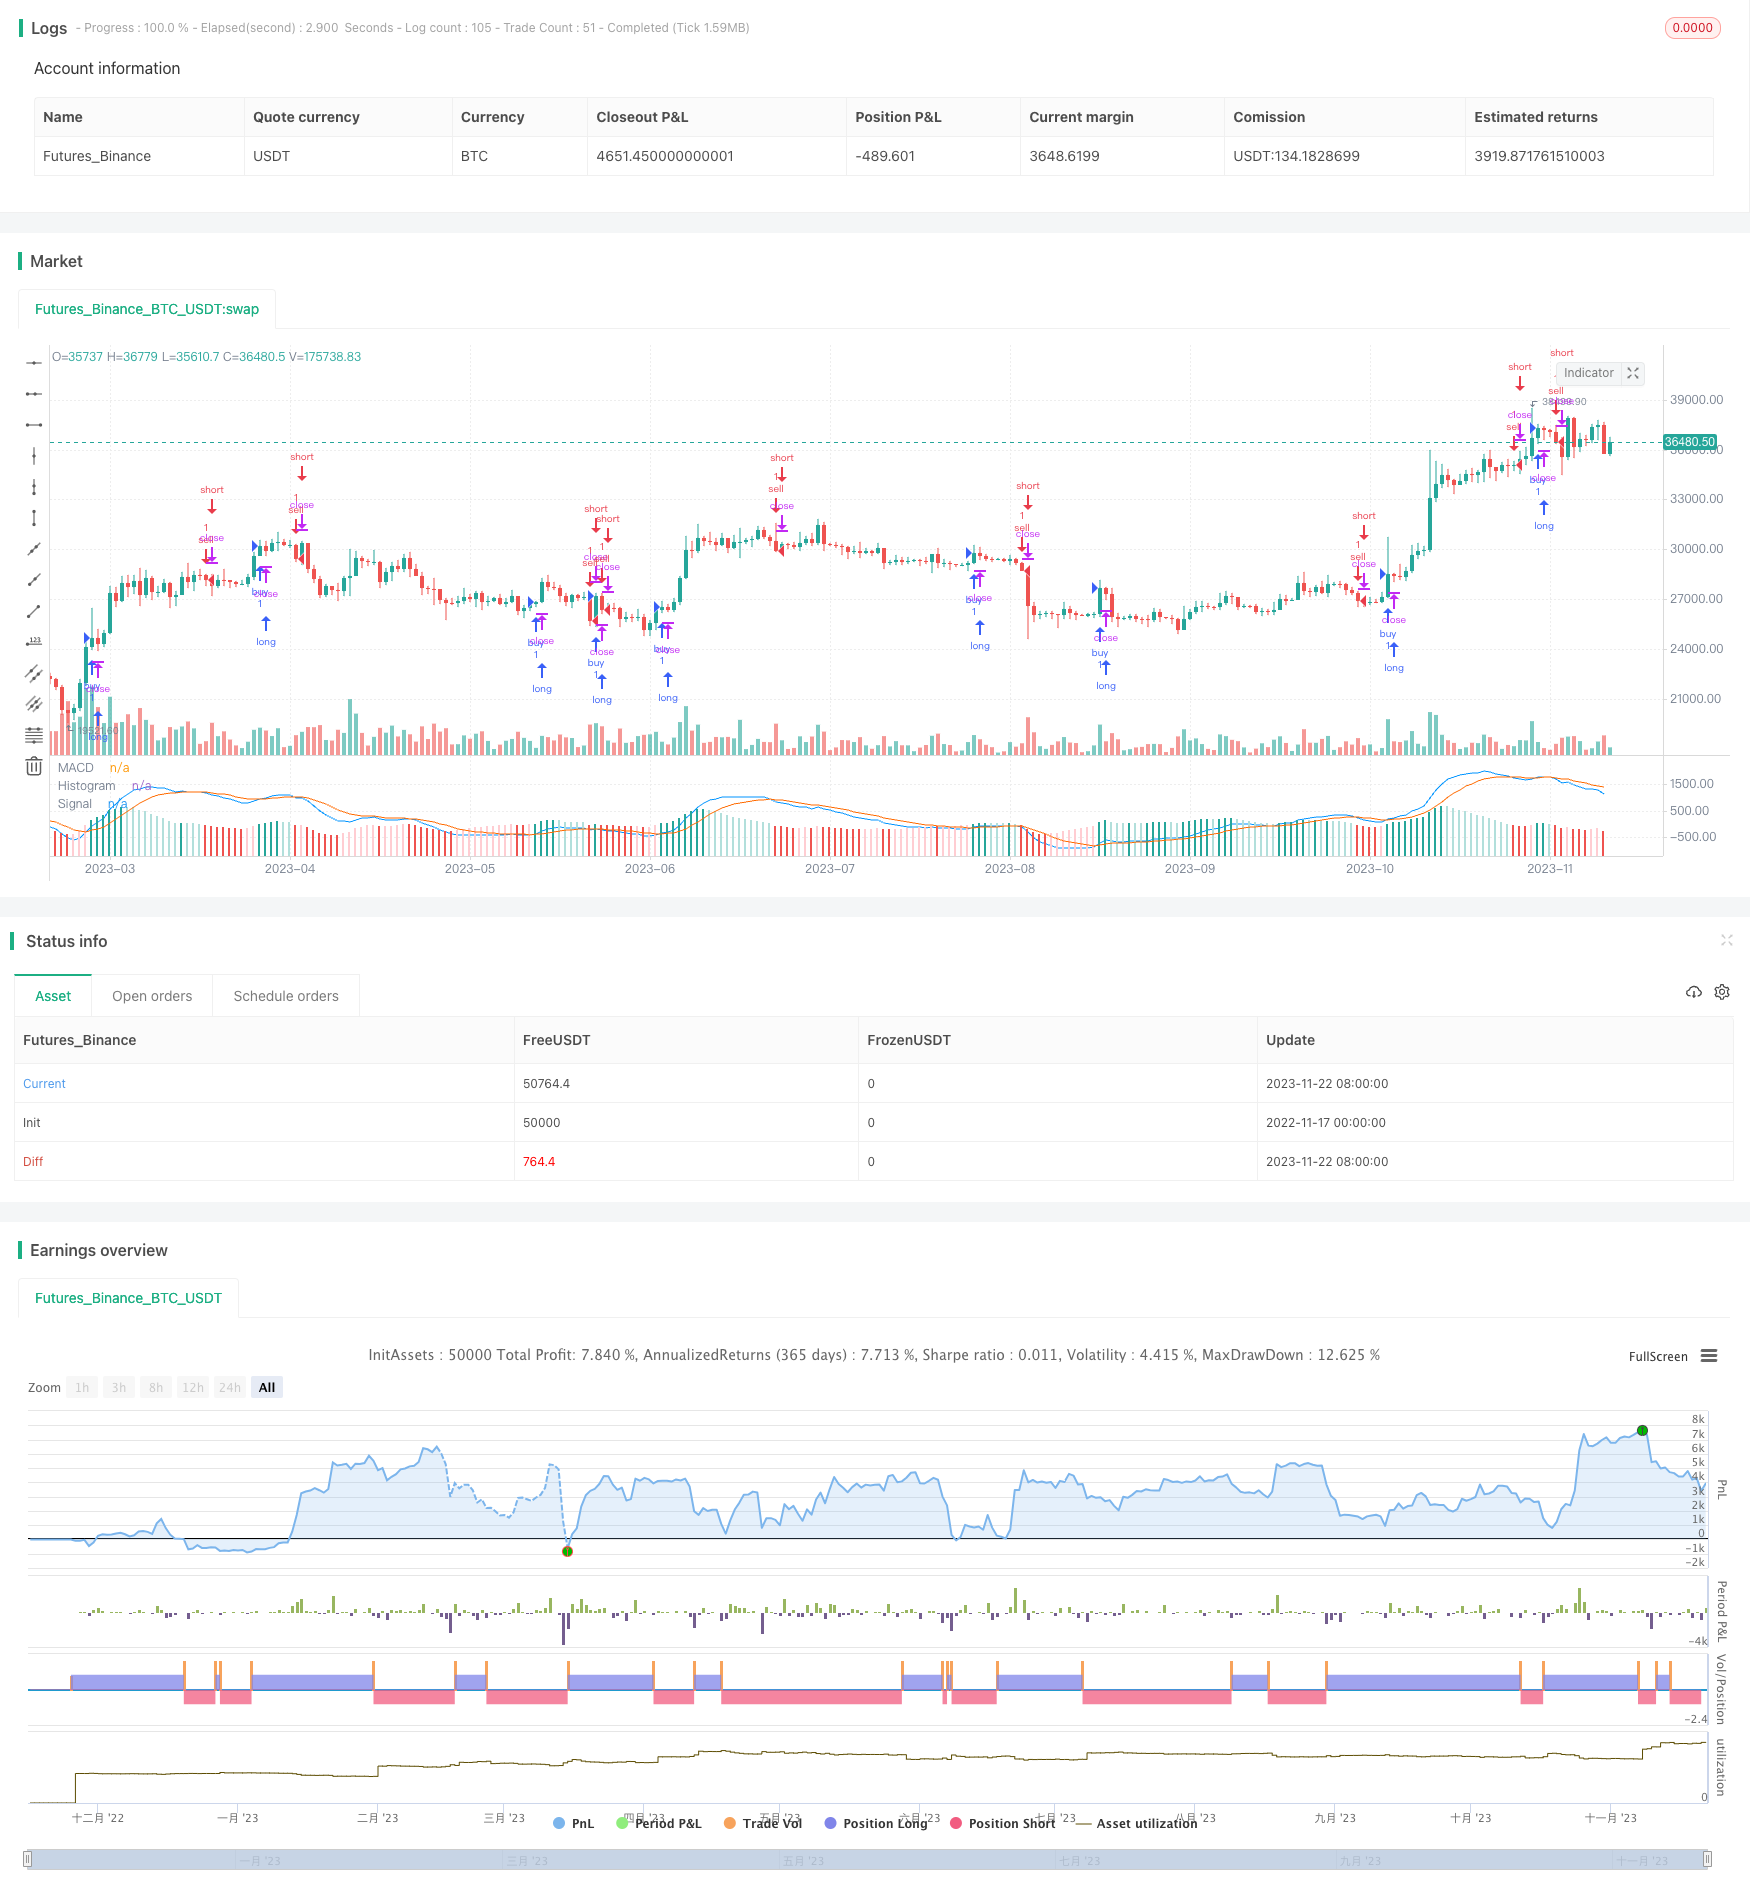
The MACD trend following strategy judges the trend by calculating the golden cross and dead cross of the MACD indicator and its signal line to follow the trend for profit.
Overview
The MACD trend following strategy judges the trend by calculating the golden cross and dead cross of the MACD indicator and its signal line to follow the trend for profit.
Strategy Principle
This strategy is based on the MACD indicator to determine the trend direction. The MACD indicator is a trend-following momentum indicator, consisting of the MACD line, Signal line and Histogram. The golden cross of the MACD and Signal lines suggests a potential bull market, while the dead cross suggests a potential bear market. The Histogram represents the difference between the two lines, indicating their divergence and changing speed through color change.
When the Histogram rises from negative to positive, a golden cross signal is generated, indicating the uptrend may just begin, and long positions can be built. When the Histogram turns from positive to negative, a dead cross signal is generated, indicating the uptrend may be topping, and long positions can be exited or short positions can be built.
Advantage Analysis
- Utilize golden/dead cross of double smoothing lines to judge trend with relatively high win rate
- Histogram clearly indicates the progress and speed of MACD indicator
- Large parameter tuning space for optimization
- Can be combined with other indicators to filter fake signals
Risk and Optimization
- There is some degree of lagging
- May generate fake signals
- Try confirming trends with MA, KD etc.
- Adjust parameters for best configuration
Conclusion
The MACD trend following strategy overall is a relatively reliable way to determine trends. By optimizing parameters and confirming with other indicators, the fake signal rate can be largely reduced, resulting in higher strategy profit. The strategy logic is simple and easy to understand, making it the first choice for algorithmic trading starters.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Fast Length |
| v_input_2 | 26 | Slow Length |
| v_input_3_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 9 | Signal Smoothing |
Source Pine Script
/*backtest
start: 2022-11-17 00:00:00
end: 2023-11-23 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("MACD")

// Getting inputs
fastLength = input(title="Fast Length",  defval=12)
slowlength = input(title="Slow Length",  defval=26)
src = input(title="Source",  defval=close)
signalLength = input(title="Signal Smoothing",  minval = 1, maxval = 50, defval = 9)

// Calculating
macd = ema(close, fastLength) - ema(close, slowlength)
signal = ema(macd, signalLength)
delta = macd - signal

// Plot colors
col_grow_above = #26A69A
col_grow_below = #FFCDD2
col_fall_above = #B2DFDB
col_fall_below = #EF5350
col_macd = #0094ff
col_signal = #ff6a00

// Plot histogram
plot(delta, title="Histogram", style=columns, color=(delta>=0 ? (delta[1] < delta ? col_grow_above : col_fall_above) : (delta[1] < delta ? col_grow_below : col_fall_below) ), transp=0 )
plot(macd, title="MACD", color=col_macd, transp=0)
plot(signal, title="Signal", color=col_signal, transp=0)

// Plot orders
if (crossover(delta, 0))
    strategy.entry("buy", strategy.long)
if (crossunder(delta, 0))
    strategy.entry("sell", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Trend-Following-Strategy-433124.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crossover EMA Short term Trading StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover Oscillation Tracking StrategyPine Script · Trend following · 5m