Strategy vault / Trend following
Moving Average Crossover MACD Trading Strategy
The moving average crossover MACD trading strategy is a quantitative trading strategy that tracks the crossover situations of short-term and long-term exponential moving averages (EMA) and makes buy and sell…
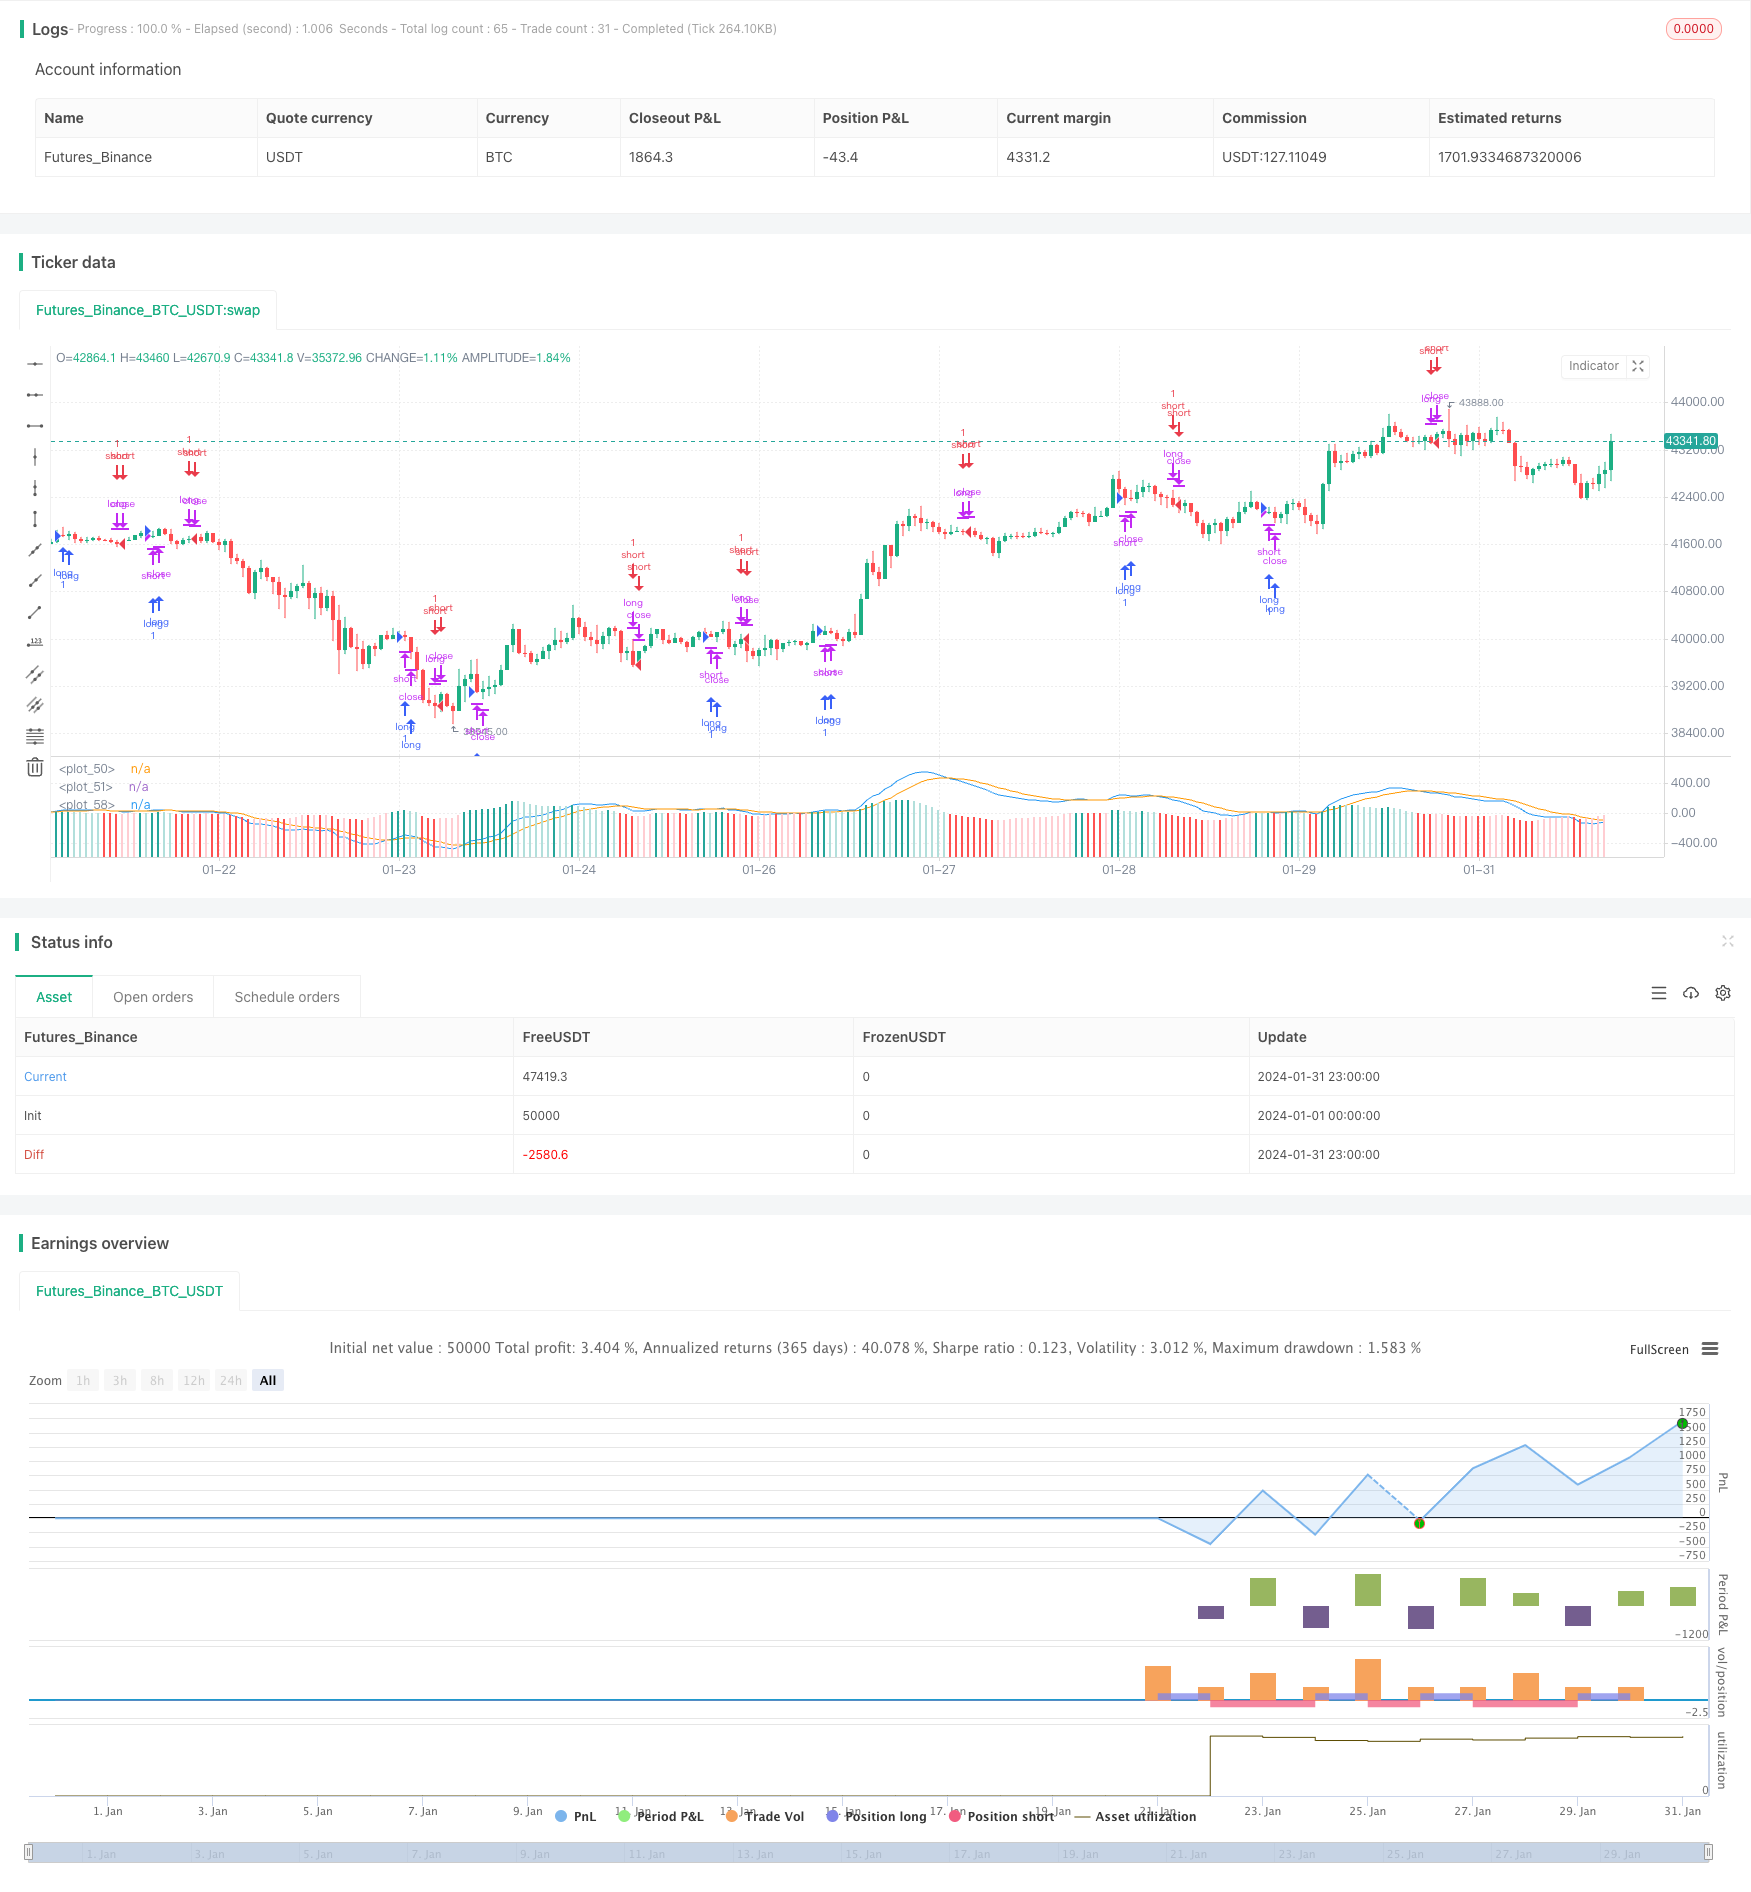
Overview
The moving average crossover MACD trading strategy is a quantitative trading strategy that tracks the crossover situations of short-term and long-term exponential moving averages (EMA) and makes buy and sell operations when golden cross and dead cross occur. This strategy combines the MACD indicator for trading signal judgment.
Strategy Logic
This strategy mainly relies on 12-day EMA, 26-day EMA and MACD indicator. The specific logic is:
- Calculate the 12-day EMA and 26-day EMA.
- Calculate the MACD (that is, the 12-day EMA minus the 26-day EMA).
- Calculate the 9-day EMA of MACD as the signal line.
- When the MACD goes above the signal line, a buy signal is generated.
- When the MACD falls below the signal line, a sell signal is generated.
- Make the corresponding buy or sell operation at the close of the second candlestick after the signal is generated.
Additionally, this strategy also sets some filtering conditions:
- The trading time is the non-closing time of each trading day.
- The absolute value of the difference between the MACD and signal line needs to be greater than 0.08.
- Only one direction of position is allowed at a time.
Advantage Analysis
This strategy combines moving average crossover and MACD indicator, which can effectively capture the inflection points of market short-term and medium-term trends. The main advantages are:
- The strategy rules are simple and clear, easy to understand and implement.
- The indicator parameters are optimized for relatively stable performance.
- It takes into account tracking medium and short term trends and timely stop loss exit.
- The trading logic is rigorous to avoid invalid trading.
Risk Analysis
This strategy also has some risks:
- Backtesting data overfitting risk. Actual application may require parameter and threshold adjustment.
- High slippage cost risk from frequent trading.
- Loss risk from failure to exit timely when trend reverses.
- Leverage risk amplification inherent in quantitative trading itself.
Corresponding mitigation methods:
- Dynamically optimize parameters and adjust thresholds.
- Appropriately relax trading rules to reduce unnecessary trading.
- Combine more indicators to judge reversal signals.
- Strictly control positions and leverage.
Optimization Directions
The main aspects for optimizing this strategy include:
- Test longer cycle moving average combinations to find optimal parameters.
- Add fundamentals like financial performance, significant events etc. as filters.
- Incorporate more indicators to determine trend reversal timing, like Bollinger Bands, KDJ etc.
- Develop stop loss mechanisms. Actively cut losses when losses reach pre-set stop loss points.
- Add drawdown ratio to control maximum drawdown.
Summary
The moving average crossover MACD trading strategy generates trading signals through simple trend tracking and effectively controls risks with appropriate filtering conditions. It is an effective quantitative trading strategy. The strategy can be improved in ways like parameter optimization, adding stop loss mechanisms, incorporating more auxiliary indicators etc.
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMMA", max_bars_back = 200)

var up1 = #26A69A
var up2 = #B2DFDB
var down1 = #FF5252
var down2 = #FFCDD2
var confirmationLength = 2

var earliest = timestamp("20 Jan 2024 00:00 +0000")

// Regn u
shortEMA = ta.ema(close, 12)
longEMA = ta.ema(close, 26)
macd = shortEMA - longEMA
signal = ta.ema(macd, 9)
delta = macd - signal
absDelta = math.abs(delta)
previousDelta = delta[1]

signalCrossover = ta.crossover(macd, signal)
signalCrossunder = ta.crossunder(macd, signal)

harskiftetdag = hour(time[confirmationLength]) > hour(time)

enterLongSignal = signalCrossover[confirmationLength] and (macd > signal) and (absDelta >= 0.08)
exitLongSignal = signalCrossunder[confirmationLength] and (macd < signal)

enterShortSignal = signalCrossunder[confirmationLength] and (macd < signal) and (absDelta >= 0.08)
exitShortSignal = signalCrossover[confirmationLength] and (macd > signal)

// Så er det tid til at købe noe
qty = math.floor(strategy.equity / close)

if time >= earliest and not harskiftetdag
    if exitLongSignal
        strategy.close("long")
    else if enterLongSignal
        strategy.close("short")
        strategy.entry("long", strategy.long, qty = qty)

    if exitShortSignal
        strategy.close("short")
    else if enterShortSignal
        strategy.close("long")
        strategy.entry("short", strategy.short, qty = qty)

// Så er det tid til at vise noe

plot(macd, color=color.blue)
plot(signal, color=color.orange)

// bgcolor(color = delta > 0.1 ? color.new(color.green, 90) : color.new(color.green, 100))
// bgcolor(color = signalCrossover ? color.purple : signalCrossunder ? color.aqua : color.new(color.green, 100))

histogramColor = delta > 0 ? (previousDelta < delta ? up1 : up2) : (previousDelta > delta ? down1 : down2)

plot(
     delta,
     style=plot.style_columns,
     color=histogramColor
)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-MACD-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crossover EMA Short term Trading StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual EMA Crossover Oscillation Tracking StrategyPine Script · Trend following · 5m